|
시장보고서
상품코드
2123618
FFS(Form Fill and Sealing) 포장 기계 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Form-Fill-Seal (FFS) Packaging Machine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
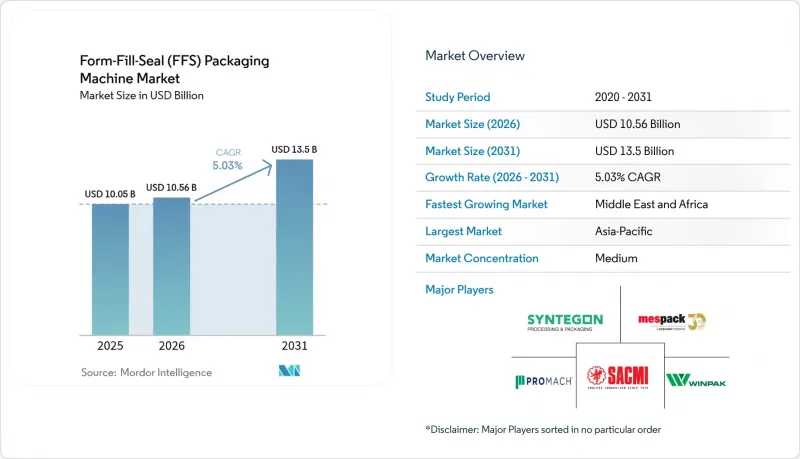
에 의하면, FFS(Form Fill and Sealing) 포장 기계 시장 규모는 2025년 100억 5,000만 달러로 평가되었고, 2026년에는 105억 6,000만 달러로 추정되고, 2026-2031년 CAGR 5.03%로 성장을 지속할 전망이며, 2031년에는 135억 달러에 이를 것으로 예측됩니다.
본 보고서는 장비 유형별(수직형 성형·충진·밀봉기, 수평형 성형·충진·밀봉기), 자동화 수준별(완전 자동, 반자동), 적용 소재별(폴리에틸렌 필름, 기타), 포장 유형별(봉지·파우치, 소포장·스틱팩, 기타), 최종 사용자 산업별(식음료, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 FFS(Form Fill and Sealing) 포장 기계 시장 동향 및 인사이트
바이오의약품 및 세포 및 유전자 치료 분야에서 무균 포장에 대한 수요 증가
각 제약사는 극도로 민감한 바이오의약품 및 세포 및 유전자 치료제의 무균성을 유지하는 FFS(Form-Fill-Seal) 시스템 도입을 확대되고 있습니다. 즉시 사용 가능한 용기는 기존 충전 방식에 비해 오염 위험을 50% 감소시켜 배치의 재가공이나 폐기를 줄여줍니다. Syntegon의 SynTiso 액체 라인은 비접촉 이송 및 실시간 입자 모니터링을 채택하여 분당 600개의 용기를 처리하며, OEM 업체들이 유럽 부속서 1의 최신 요구 사항을 기계 설계에 어떻게 반영하고 있는지 입증하고 있습니다. 이러한 자본 동향은 당초 북미와 유럽에서 탄력을 받았으나, 규제 조화가 가속화됨에 따라 현재는 아시아의 수탁 제조 거점으로까지 확산되고 있습니다. 이러한 설비에서는 일반적으로 아이솔레이터 기술과 인라인 육안 검사를 결합하여 검증 주기를 단축하고, FDA 및 EMA 감사에 대한 대응을 용이하게 하고 있습니다. 바이오의약품 처리 능력 향상으로 인해 고속 시스템의 재주문이 증가하고 있으며, 주요 공급업체의 애프터마켓용 부품 및 서비스 수주 잔고가 확대되고 있습니다.
반려동물사료 및 수의학용 영양 보조제 브랜드의 성장
반려동물의 ‘인간화’라는 추세를 배경으로 프리미엄 반려동물사료 및 치료용 반려동물사료가 잇달아 출시되고 있으며, 풍미의 휘발성 성분과 유효한 영양 보조 성분을 보존하는 정량 관리된 파우치에 대한 수요가 높아지고 있습니다. 특수 영양 보조 식품의 포장에는 유아용 안전 캡이나 변조 방지 기능이 필수적이며, 이를 위해서는 정확한 계량과 밀봉 강도를 확보할 수 있는 서보 구동식 수평형 FFS(Form Fill and Sealing) 구성이 적합합니다. 잦은 레시피 변경으로 인해 각 제조업체는 공구 없이도 전환이 가능하고 HMI 프리셋을 통해 레시피를 업로드할 수 있는 설비를 요구하게 되었으며, 이를 통해 소량 생산 시 다운타임을 단축하고 있습니다. 북미와 유럽의 수탁 제조업체들이 이러한 수요를 주도하고 있지만, 가처분 소득 증가와 반려동물 사육률의 상승에 따라 브라질, 한국, 인도의 도시 지역에서도 유사한 경향이 나타나고 있습니다. OEM 각사는 이에 대응하여 레시피 관리 소프트웨어와 원격 지원 계약을 세트로 제공함으로써, 계절적 수요가 정점에 달할 때의 가동 시간을 보장하고 있습니다. 그 결과 생산량이 증가함에 따라, 컨버터 업체들이 반자동 라인에서 누출 감지 기능을 통합한 완전 자동화 플랫폼으로 업그레이드하는 움직임이 확산되고 있으며, 이미 도입된 설비의 교체 수요가 높아지고 있습니다.
저밀도 제품에서는 수익성을 확보할 수 없습니다.
FFS(Form Fill and Sealing) 시스템은 부피 밀도가 0.3g/cm3 이하인 분말이나 압출 스낵을 취급할 경우, 단위 중량당 필름 소비량이 급증하기 때문에 경제적으로 불리한 상황에 직면합니다. 원자재비가 제품 가치의 15%를 초과하는 경우도 있어, 가격에 민감한 개발도상국 시장에서는 이익률을 압박하고 있습니다. 골판지 상자나 직물 봉투와 같은 대체 수단은 진열상의 매력은 떨어지지만, Kg당 비용이 낮아지는 경우가 있어, 이에 따라 지역 브랜드 소유자들은 FFS 라인에 대한 설비 투자를 미루는 경향이 있습니다. 각 OEM 업체들은 사이드 심을 제거하고 세로 피치를 최적화한 튜브형 디자인을 도입하여 이러한 장벽을 극복하려 하고 있지만, 수지 가격 및 환율 변동이 EBIT를 압박하고 있는 지역에서는 그 채택이 여전히 더딘 상황입니다. 그 결과, 이러한 제약은 저밀도 주력 상품에 의존하는 신흥 경제국에서의 설비 전면 교체를 장기적으로 가로막는 요인이 되고 있습니다.
부문 분석
2025년, 수직형 시스템은 입상 식품, 분말, 산업용 제품에 대한 범용성을 활용하여 FFS 포장 기계 시장의 57.83%를 차지했습니다. 한편, 수평형 기계의 FFS 포장 기계 시장 규모는 의약품 및 고차단성 스낵 용도에서 열을 균일하게 분산시키는 플랫 웹 구조가 선호됨에 따라 2031년까지 연평균 성장률(CAGR) 6.58%라는 빠른 속도로 확대될 것으로 예측됩니다. 유한 요소법에 의해 최적화된 성형 칼라 덕분에 VFFS의 밀봉 품질이 향상되고, 밀봉 내부의 제품 결함이 감소하여 시장에서 주도적인 입지를 유지하고 있습니다. 그러나 HFFS의 구성은 부록 1의 개정에 부합하여 더 깨끗한 제품 채널과 비접촉 이송을 가능하게 함으로써, 고급 의약품 충전 부문의 전환을 촉진하고 있습니다. 다국적 브랜드는 대개 듀얼 플릿 전략을 채택하여, 주류 SKU에는 VFFS를, 부가가치가 높은 형태에는 HFFS를 할당하고 있습니다.
도입 결정은 순수한 비용이 아니라 위생 등급, 포장 스타일, 라인 속도 목표에 따라 이루어집니다. HFFS용 릴에는 일반적으로 더 높은 차단성을 가진 코팅이 적용되어 있어, 더 얇은 두께로도 동등한 유통 기한을 실현함으로써 재료비의 단점을 부분적으로 상쇄하고 있습니다. 두 형태를 모두 다루는 사업자의 교차 교육은 여전히 과제로 남아 있으며, 각 OEM 업체들은 학습 곡선을 완화하기 위해 공통 HMI 프레임워크를 도입하는 방향으로 나아가고 있습니다. 그 결과, 아시아의 소포장 수요 증가에 따라 절대적인 출하량은 증가하겠지만, 2031년까지 VFFS의 우위는 소폭 후퇴할 전망입니다.
2025년에는 인력 부족과 위생 요건의 엄격화로 인해 비접촉식 작동이 구매 결정의 주요 요인이 된 결과, 전자동 라인이 매출의 71.85%를 차지했습니다. 이 부문은 가동 시간을 보장하는 엣지 AI 진단 기술의 뒷받침을 받아 연평균 성장률(CAGR) 6.05%를 기록하며, FFS 포장 기계 시장 전체를 상회하는 성장을 이룰 전망입니다. 반자동 라인은 설비 투자 제약이나 소량 생산이 주를 이루는 특수 생산 분야 및 개발도상국의 중소기업에서 여전히 사용되고 있습니다. 그러나 모듈식 제어 아키텍처 덕분에 단계적인 업그레이드가 가능해져, 사용자는 장비를 전면 교체하지 않고도 계량기, 픽 앤 플레이스 로봇, 서보 축을 나중에 추가할 수 있게 되었습니다.
IoT 대시보드는 OEE(종합 설비 효율) 지표를 제공하며, 공장장은 이를 활용하여 지속적인 개선을 통한 성과를 입증하고 경영진의 지지를 공고히 하고 있습니다. 또한, 전자상거래의 크기 제한은 폐쇄 루프 모션 제어를 통해서만 실현 가능한 치수 일관성을 요구하고 있으며, 이것이 전환을 더욱 촉진하고 있습니다. 농산물의 벌크 상품의 경우, 제품의 편차가 카메라 검사의 과제가 되기 때문에 여전히 수동으로 충전 및 포장하는 시장이 남아 있습니다.
지역별 분석
2025년, 아시아태평양은 중국, 인도, 베트남의 도시 지역 소비 확대와 수출 지향형 제조 거점의 확장에 힘입어 FFS 포장 기계 시장에서 39.75%라는 최대 점유율을 유지했습니다. 인도의 의약품 현지 생산에 대한 정책적 우대 조치와 중국의 자동화에 대한 세제 혜택이 새로운 생산 능력 확대를 촉진하는 한편, 태국과 인도네시아에서 스낵류의 수출 증가가 중속 라인 수요를 끌어올리고 있습니다. 국내 필름 압출 클러스터를 통해 신속한 공급 루프가 실현되어, 수입 소모품에 따른 환율 리스크를 완화하고 있습니다.
북미와 유럽은 고정밀 및 지속 가능한 포장에 대한 노력을 통해 기술적 리더십을 유지하고 있습니다. 두 지역 모두 그린필드 투자가 아닌 기존 설비의 갱신 주기에 주력하고 있습니다. 미국의 사업자들은 인력 이직을 보완하기 위해 엣지 AI를 활용한 개조 및 로봇 기술에 투자하고 있는 반면, 유럽의 공장들은 단일 소재 대응 및 에너지 효율이 높은 히터에 설비 투자를 하고 있습니다. 양 지역의 성숙한 규제 체계 덕분에 부속서 1을 준수하는 아이솔레이터 및 실시간 출하 검사가 가속화되고 있으며, 전문 OEM 업체들은 높은 수익률을 확보하고 있습니다.
중동 및 아프리카는 사우디아라비아, 이집트, 남아프리카의 지역 제약 허브들이 제네릭 의약품 생산을 현지화함에 따라, 2031년까지 연평균 성장률(CAGR) 7.25%로 가장 빠르게 성장하는 지역으로 부상하고 있습니다. 콜드체인 물류 인프라 확충으로 무균 파우치 충전 라인에 대한 수요가 더욱 높아지는 한편, 가처분 소득 증가는 포장 스낵 및 RTD(즉석 음용) 커피의 신제품 출시를 뒷받침하고 있습니다. 장비 공급업체들은 현지 숙련 인력 부족을 보완하기 위해, 사업자 교육 및 애프터서비스용 재고 확보를 포함한 턴키 지원을 통해 수주를 확보하고 있습니다. 전반적으로, 지리적 분산은 경기 변동을 완화시켜 FFS 포장 기계 시장에 균형 잡힌 세계 성장 궤도를 마련해 주고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the form fill seal packaging machine market size is expected to grow from USD 10.05 billion in 2025 to USD 10.56 billion in 2026 and is forecast to reach USD 13.5 billion by 2031 at 5.03% CAGR over 2026-2031.
This report is Segmented by Equipment Type (Vertical Form-Fill-Seal, and Horizontal Form-Fill-Seal), Automation Level (Fully-Automatic, and Semi-Automatic), Material Compatibility (Polyethylene Films, and More), Packaging Type (Bags and Pouches, Sachets and Stick Packs, and More), End-User Industry (Food and Beverage, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD)
Global Form-Fill-Seal (FFS) Packaging Machine Market Trends and Insights
Rising Demand for Aseptic Packaging in Biologics and Cell-Gene Therapy
Pharmaceutical manufacturers are scaling form fill seal systems that maintain sterility for highly sensitive biologics and cell-gene therapies. Ready-to-use containers lower contamination risks by 50% compared with conventional filling approaches, trimming batch rework and scrap. Syntegon's SynTiso liquid line processes 600 containers per minute using contactless transport and real-time particle monitoring, demonstrating how OEMs embed European Annex 1 updates into machine design. The capital shift first gained traction in North America and Europe but is now spreading to Asian contract manufacturing hubs as regulatory convergence accelerates. These installations typically pair isolator technology with inline vision inspection, shortening validation cycles and easing FDA and EMA audit readiness. Heightened biologic throughput is translating into repeat orders for higher-speed systems, strengthening aftermarket parts and service backlogs for leading suppliers.
Growth of Pet-Food and Veterinary Nutraceutical Brands
Pet-humanization trends have sparked premium and therapeutic pet-food launches requiring portion-controlled pouches that preserve flavor volatiles and active nutraceutical ingredients. Specialty nutraceutical packs mandate child-resistant closures and tamper evidence, which favor servo-driven horizontal form fill seal configurations for precision dosing and seal integrity. Frequent recipe changes force manufacturers to seek equipment that enables tool-less changeovers and recipe upload through HMI presets, shaving downtime in short-run production. North American and European co-packers are spearheading this demand, but similar patterns are emerging in Brazil, South Korea, and urban India as disposable income and pet adoption rise. OEMs have responded by bundling recipe-management software with remote support contracts that guarantee uptime during seasonal demand peaks. Resultant volume growth is elevating installed-base renewals as converters upgrade from semi-automatic lines to fully-automatic platforms with integrated leak detection.
Uneconomical for Low-Density Products
Form fill seal systems face unfavorable economics when handling powders or extruded snacks with bulk densities below 0.3 g/cm3, as film consumption per unit weight rises sharply. Material expenditure can surpass 15% of product value, eroding margin in price-sensitive developing markets. Carton and woven-sack alternatives sometimes deliver lower cost-per-kilogram despite reduced shelf appeal, prompting regional brand owners to delay capex for form fill seal lines. OEMs are tackling the barrier by introducing tubular designs that eliminate side seams and optimize vertical pitch, yet adoption remains tepid where resin prices and currency fluctuations squeeze EBIT. Consequently, the restraint exerts a long-run drag on aggregate equipment replacement in emerging economies reliant on low-density staples.
Other drivers and restraints analyzed in the detailed report include:
- Sustainability-Driven Shift Toward Recyclable Mono-Material Films
- Edge-AI Enabled Predictive Maintenance Reduces Downtime
- Skilled-Labor Shortage for Advanced Servo Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Vertical systems controlled 57.83% of the form fill seal packaging machine market in 2025, leveraging versatility for granular foods, powders, and industrial products. The form fill seal packaging machine market size for horizontal machines is projected to climb at a faster 6.58% CAGR to 2031 as pharmaceutical and high-barrier snack applications prefer their flat web geometry for even heat distribution. Finite-element-optimized forming collars have improved VFFS seal quality, mitigating product-in-seal defects and sustaining leadership. Yet HFFS configurations enable cleaner product paths and contactless transport that align with Annex 1 revisions, prompting premium drug-filler segments to migrate. Multinational brands often keep a dual-fleet strategy, deploying VFFS for mainstream SKUs while reserving HFFS for value-added formats.
Adoption choices pivot on hygiene class, pack style, and line-speed targets rather than pure cost. HFFS reels usually carry higher barrier coatings, enabling shelf-life parity at thinner gauges and partially neutralizing material-cost disadvantages. Cross-training operators across both formats remains a challenge, nudging OEMs toward common HMI frameworks that lower learning curves. Consequently, the VFFS stronghold will erode slightly through 2031, although absolute shipments rise in line with expanding sachet demand in Asia.
Fully-automatic lines captured 71.85% revenue in 2025 as labor scarcity and stricter hygiene requirements tilted purchasing decisions toward touchless operation. This segment will outpace the broader form fill seal packaging machine market at a 6.05% CAGR, fueled by edge-AI diagnostics that guarantee uptime contracts. Semi-automatic lines persist in specialty runs and developing-nation SMEs where capex constraints and small lot sizes dominate. However, modular control architectures now offer staged upgrades, allowing users to retrofit weighers, pick-and-place robots, and servo axes without wholesale replacement.
IoT dashboards supply OEE metrics that plant managers leverage to justify continuous-improvement bonuses, anchoring management buy-in. Moreover, e-commerce sizing constraints favor dimensional consistency achievable only with closed-loop motion control, further nudging migration upward. Nonetheless, a residual serviceable market for manual loading and bagging continues in bulk agricultural produce where product variability challenges camera-based inspection.
Complete Report Scope:
- By Equipment Type
- Vertical Form-Fill-Seal (VFFS)
- Horizontal Form-Fill-Seal (HFFS)
- By Automation Level
- Fully-Automatic
- Semi-Automatic
- By Material Compatibility
- Polyethylene (PE) Films
- Polypropylene (PP) Films
- Bioplastic and Compostable Films
- Aluminum-Laminate and Barrier Films
- By Packaging Type
- Bags and Pouches
- Sachets and Stick Packs
- Aseptic Bottles and Ampoules
- Blister and Strip Packs
- Other Packaging Types
- By End-user Industry
- Food and Beverage
- Pharmaceuticals and Biologics
- Pet Food and Veterinary
- Home and Personal Care
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific retained the largest 39.75% slice of the form fill seal packaging machine market in 2025, propelled by rising urban consumption and export-oriented manufacturing bases across China, India, and Vietnam. Policy incentives for localized pharma production in India and tax benefits for automation in China catalyze fresh capacity, while growing snack exports from Thailand and Indonesia add mid-speed line demand. Domestic film extrusion clusters enable fast supply loops, tempering currency risk on imported consumables.
North America and Europe uphold technology leadership through high-precision and sustainable packaging agendas. Both regions engage in replacement, not green-field, cycles: U.S. operators invest in edge-AI retrofits and robotics to offset labor turnover, whereas European plants allocate capex to mono-material compatibility and energy-efficient heaters. Their mature regulatory frameworks accelerate Annex 1-compliant isolators and real-time release testing, locking in premium margins for specialized OEMs.
Middle East and Africa emerge as the fastest-growing cluster at 7.25% CAGR to 2031 as regional pharma hubs in Saudi Arabia, Egypt, and South Africa localize generic production. Infrastructure upgrades in cold-chain logistics draw additional demand for aseptic pouching lines, while rising disposable income supports packaged snacks and RTD coffee launches. Equipment suppliers win orders through turnkey support, including operator training and after-sales stocking, to counter limited local skill pools. Collectively, geographic diversification cushions cyclical swings, granting the form fill seal packaging machine market a balanced global growth runway.
- Syntegon Technology GmbH
- ProMach Inc.
- SACMI Imola S.C.
- Winpak Ltd.
- Mespack S.L.
- HDG Verpackungsmaschinen GmbH
- Huhtamaki Oyj
- Rovema GmbH
- Duravant LLC
- ULMA Packaging, S.Coop.
- ILAPAK International S.A.
- IMA Industria Macchine Automatiche S.p.A.
- Viking Masek Global Packaging Technologies, LLC
- Nichrome India Ltd.
- Triangle Package Machinery Company
- PFM Group S.p.A.
- Fres-co System USA, Inc.
- Paxiom Group (WeighPack Systems Inc.)
- Multivac Sepp Haggenmller SE and Co. KG
- TNA Australia Pty Ltd
- Schneider Packaging Equipment Co., Inc.
- Bosch Rexroth AG
- Scholle IPN Company, LLC
- ProAmpac Holdings Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for aseptic packaging in biologics and cell-gene therapy
- 4.2.2 Growth of pet-food and veterinary nutraceutical brands
- 4.2.3 Sustainability-driven shift toward recyclable mono-material films
- 4.2.4 Surge in low-acidity ready-to-drink coffee launches
- 4.2.5 Edge-AI enabled predictive-maintenance modules reduce downtime
- 4.2.6 FMCG on-demand customization (late-stage differentiation)
- 4.3 Market Restraints
- 4.3.1 Uneconomical for low-density products
- 4.3.2 Skilled-labor shortage for advanced servo systems
- 4.3.3 Volatility in polymer-resin prices
- 4.3.4 Rising carbon-tax regimes on multilayer films
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Equipment Type
- 5.1.1 Vertical Form-Fill-Seal (VFFS)
- 5.1.2 Horizontal Form-Fill-Seal (HFFS)
- 5.2 By Automation Level
- 5.2.1 Fully-Automatic
- 5.2.2 Semi-Automatic
- 5.3 By Material Compatibility
- 5.3.1 Polyethylene (PE) Films
- 5.3.2 Polypropylene (PP) Films
- 5.3.3 Bioplastic and Compostable Films
- 5.3.4 Aluminum-Laminate and Barrier Films
- 5.4 By Packaging Type
- 5.4.1 Bags and Pouches
- 5.4.2 Sachets and Stick Packs
- 5.4.3 Aseptic Bottles and Ampoules
- 5.4.4 Blister and Strip Packs
- 5.4.5 Other Packaging Types
- 5.5 By End-user Industry
- 5.5.1 Food and Beverage
- 5.5.2 Pharmaceuticals and Biologics
- 5.5.3 Pet Food and Veterinary
- 5.5.4 Home and Personal Care
- 5.5.5 Other End-user Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Kenya
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Syntegon Technology GmbH
- 6.4.2 ProMach Inc.
- 6.4.3 SACMI Imola S.C.
- 6.4.4 Winpak Ltd.
- 6.4.5 Mespack S.L.
- 6.4.6 HDG Verpackungsmaschinen GmbH
- 6.4.7 Huhtamaki Oyj
- 6.4.8 Rovema GmbH
- 6.4.9 Duravant LLC
- 6.4.10 ULMA Packaging, S.Coop.
- 6.4.11 ILAPAK International S.A.
- 6.4.12 IMA Industria Macchine Automatiche S.p.A.
- 6.4.13 Viking Masek Global Packaging Technologies, LLC
- 6.4.14 Nichrome India Ltd.
- 6.4.15 Triangle Package Machinery Company
- 6.4.16 PFM Group S.p.A.
- 6.4.17 Fres-co System USA, Inc.
- 6.4.18 Paxiom Group (WeighPack Systems Inc.)
- 6.4.19 Multivac Sepp Haggenmller SE and Co. KG
- 6.4.20 TNA Australia Pty Ltd
- 6.4.21 Schneider Packaging Equipment Co., Inc.
- 6.4.22 Bosch Rexroth AG
- 6.4.23 Scholle IPN Company, LLC
- 6.4.24 ProAmpac Holdings Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment