

|
시장보고서
상품코드
2123625
원편광 이색성 분광계 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Circular Dichroism Spectrometers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 원편광 이색성 분광계 시장 규모는 2025년에 3,662만 달러로 평가되었고, 2026년 3,935만 달러에서 2031년까지 5,630만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 7.44%를 나타낼 전망입니다.
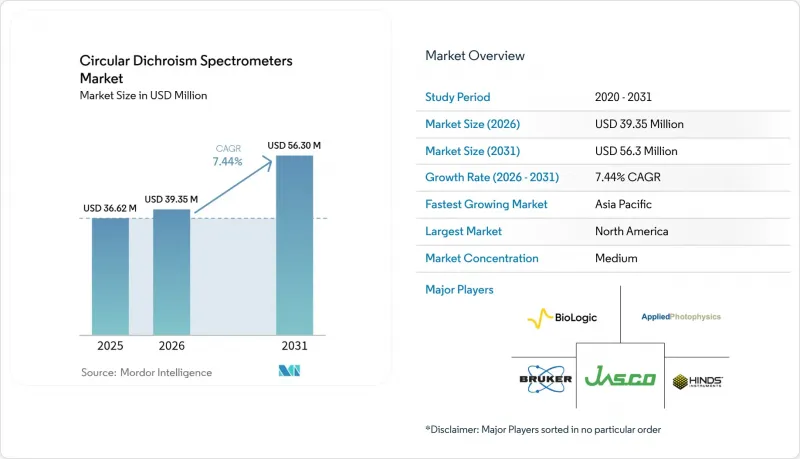
본 보고서는 제품 유형별(탁상형 CD 분광계, 기타), 기술별(전자 원편광성(ECD), 기타), 용도별(단백질 2차 구조 결정, 기타), 최종 사용자별(제약·바이오기술 기업, 기타), 지역별(북미, 유럽, 아시아태평양, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 원편광 이색성 분광계 시장 동향 및 인사이트
전 세계 바이오의약품 제조의 확대
연속 생산으로 전환되는 바이오의약품 제조 시설에서는 실시간 폴딩 검증을 위해 CD 프로브를 공정 라인에 직접 통합하고 있으며, 이로 인해 높은 처리량 사양이 요구되어 고정형 시스템의 도입이 촉진되고 있습니다. 브루커(Bruker)사의 2024년 매출이 33억 7,000만 달러로 급증한 것은 이러한 설비 투자 프로젝트와 연계된 계측 기기 수요 증가를 뒷받침하고 있습니다. 현재 각 벤더사는 자동 큐벳 체인저와 GMP 대응 소프트웨어를 번들로 제공하고 있으며, 이를 통해 운영자의 개입 시간을 단축하는 동시에 21 CFR Part 11 요건도 준수하고 있습니다. 배치 출시량 증가에 따라 다년간의 서비스 계약이 촉진되고 있으며, 이를 통해 안정적인 수익이 확보되고 있습니다. 이러한 요인들이 결합되어 원편광 이색성 분광계 시장을 뒷받침하는 견고한 규정 준수 기반이 형성되고 있습니다.
생명과학 계측 장비 분야의 연구개발비 증가
NIH의 2025 회계연도 예산 요청액 501억 달러에 힘입어, 보조금을 통한 실험실 업그레이드가 순조롭게 진행되고 있습니다. 한편, NSF의 4,000만 달러 규모의 단백질 설계 이니셔티브는 고도 구조 검증 키트에 대한 수요를 뒷받침하고 있습니다. 학술 컨소시엄은 구매력을 결집하여, 다양한 단백질 라이브러리를 처리할 수 있는 AI 기반 스펙트럼 디콘볼루션 기능을 갖춘 데스크톱형 장비를 선택하고 있습니다. 조달 사이클에서는 멀티 검출기 패키지가 점점 더 많이 지정되고 있으며, 턴키 시스템을 출하할 수 있는 제조업체가 우대받고 있습니다. 이러한 자금 조달 동향은 장비의 교체 주기를 안정화시키고, 원편광 이색성 분광계 시장을 뒷받침하고 있습니다.
CD 시스템의 높은 초기 투자 비용 및 운영 비용
GMP 준수 소프트웨어 및 서비스 계약을 포함하면 하이엔드 시스템의 가격은 25만 달러를 초과하기도 하여, 처음 구매하는 기업에게는 자본 예산상의 부담이 됩니다. 공급망 내 관세로 인해 광학 서브어셈블리를 미국으로 수입하는 기업의 경우, 입고 비용이 10-15% 증가할 위험이 있습니다. 운영 비용에는 액체 질소 조달, 램프 교체, 특수 교정용 시료 등이 포함되어 총 소유 비용을 상승시키고 있습니다. 시설 공유 모델은 이러한 부담의 일부를 경감시켜 주지만, 예약 병목 현상이 발생하여 시간적 제약이 있는 실험에 지장을 줍니다. 이러한 요인들이 복합적으로 작용하여, 가격에 민감한 지역의 원편광 이색성 분광계 시장에 대한 높은 성장에 대한 낙관론을 약화시키고 있습니다.
부문 분석
탁상형 장비는 학술 연구실 및 중견 생명공학 기업의 일상적인 단백질 폴딩 스크리닝 요구를 충족시킴으로써, 2025년 원편광 이색성 분광계 시장 규모에서 44.78%라는 압도적인 점유율을 차지했습니다. 연구실에서 이를 선택하는 이유는 컴팩트한 설치 면적, 고속 스캔 모드, 옵션으로 제공되는 자동 플레이트 리더 때문입니다. 플로어 스탠딩형 모델은 절대적인 출하 대수로는 적지만, 연속 생산 라인에서는 연중무휴 24시간의 신뢰성과 더 높은 S/N비가 요구되기 때문에 대수 기준으로 가장 빠른 성장세를 기록하고 있습니다. 국립광과학시설에 설치된 특수한 SRCD 빔라인 구성은 광범위한 파장이 중요한 틈새 시장인 막 단백질 프로젝트에 활용되고 있습니다. 하버드 대학교 의과대학에서 2대의 J-1500을 도입한 사례는 탁상형이 고성능 안정성 검사에서 여전히 중심적인 역할을 하고 있음을 보여줍니다. 예측 기간 동안, 탁상형은 계속해서 교체 주기를 주도하는 한편, 고정형 플랫폼은 신규 플랜트 시장을 확보하여 원편광 이색성 분광계 시장의 수익 구성 균형을 유지할 것으로 보입니다.
이와 동시에 제품 업그레이드로 인해 카테고리 간의 경계가 모호해지고 있습니다. 각 벤더들은 현재 과거에는 대형 시스템에만 탑재되었던 로봇식 오토샘플러를 탁상형에 후속 장착하고 있어, 소규모 실험실에서도 96웰 플레이트를 하룻밤 사이에 처리할 수 있게 되었습니다. 반면, 고정형 모델에는 모듈식 광학 시스템이 내장되어 있어, 사용자는 제조업체에 수리를 의뢰하지 않고도 UV, 가시광선 또는 중적외선(mid-IR) 헤드로 교체할 수 있습니다. 이러한 기능의 균일화로 인해 기존 제품 간의 가격 차이는 줄어들고 있지만, 처리 능력 및 내구성에 관한 차별화된 가치 제안은 유지되고 있습니다. 궁극적으로 진화하는 실험실 워크플로우로 인해 두 제품 카테고리의 확장이 확실시되며, 원편광 분광기 시장 전체에 걸친 광범위한 비즈니스 기회가 강화될 것입니다.
2025년에도 전자 CD는 원편광 이색성 분광계 시장 점유율의 54.88%를 계속 차지했습니다. 이는 그 원자외선 영역이 단백질 연구자들에게 높이 평가받는 α-헬릭스와 β-시트의 지문 정보를 제공하기 때문입니다. 이 기법의 성숙한 검증 지침은 규제 당국에 대한 신청을 용이하게 하며, 배치 출시 검사의 기본 기법이 되었습니다. 싱크로트론 방사선 CD는 빔라인 접근이 제한적이긴 하지만, 국립 시설이 산업용 큐타임을 개방하고 기존 광학 시스템으로는 달성할 수 없는 최대 170nm의 파장을 제공하게 됨에 따라 가장 높은 CAGR을 기록하고 있습니다. 진동 CD는 키랄 소분자의 품질 보증(QA) 및 품질 관리(QC) 부문에 진입하고 있지만, 현재 사용자는 양자 캐스케이드 레이저 광원에 대한 투자를 주저하지 않는 제약 산업의 입체화학 연구 그룹으로 제한되어 있습니다. JASCO의 중적외선 양자 캐스케이드 벤치탑 시스템은 측정 시간을 몇 시간에서 몇 분으로 단축함으로써, VCD가 틈새 시장에서 일상적인 워크플로우로 전환될 수 있음을 입증하고 있습니다.
이러한 기술 간의 상호 교류는 확대되고 있습니다. 소프트웨어 패키지를 통해 전자 영역과 진동 영역에 걸친 스펙트럼의 중첩이 가능해져, 단백질의 주사슬과 측사슬의 키랄성을 단일 화면에서 확인할 수 있게 되었습니다. 휴대용 SRCD 애드온은 평가 단계에 있지만, 빔 타임 확보가 여전히 제약 요인으로 작용하고 있습니다. 향후 전망으로, 전자 CD는 주력 제품으로 남을 것이며, SRCD와 VCD는 높은 이익률을 가져와 원편광 이색성 분광계 시장 전체에서 계층적인 가격 체계가 유지될 것으로 예측됩니다.
지역별 분석
북미는 2025년 원편광 이색성 분광계 시장 점유율 38.10%를 유지했습니다. 이는 성숙한 바이오의약품 파이프라인, FDA의 엄격한 분석 요건, 충분한 자금을 바탕으로 한 학술 생태계의 뒷받침에 힘입은 결과입니다. NIH의 2025 회계연도 예산 501억 달러는 공동 이용 시설 내 장비의 정기적인 교체를 보장합니다. 주요 광학 부품 어셈블리에 10-15%의 관세가 부과될 가능성이 있어 단기적으로는 가격 상승으로 이어질 우려가 있으나, 보증 할인이나 리스 모델이 그 영향을 완화할 것으로 보입니다. 캐나다 내 백신 제조 시설 확충으로 인해, 특히 GMP 생산 현장을 위해 설계된 고정형 CD 장비를 중심으로 지역 내 조달 수요가 증가하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 8.41%로 가장 빠르게 성장하는 시장이며, 중국의 현대적인 바이오의약품 클러스터, 인도의 적극적인 바이오시밀러 목표, 일본의 재생의학용 품질 관리 도구에 대한 투자가 그 원동력이 되고 있습니다. 중국의 CD 공급업체들은 비용 최적화된 벤치형 장비에 주력하고 있지만, FDA 준수 검증 포장이 필요한 다국적 합작 기업으로부터의 대용량 수주는 세계 기업들이 확보하고 있습니다. 인도의 정부 주도 바이오테크놀러지 파크에서는 설비 자금 조달이 패키지 형태로 이루어지고 있어 스타트업 기업 수요를 자극하고 있습니다. 이러한 지역적 모멘텀으로 인해 수입 중고 장비에 대한 기존 의존도가 낮아지고, 원편광 이색성 분광계 시장 전체에서 프리미엄 부문으로의 침투가 가속화되고 있습니다.
유럽에서는 대형 제약 기업의 설비 갱신과 ‘Horizon Europe’ 연구 공모를 중심으로 균형 잡힌 완만한 성장이 나타나고 있으며, 시장은 안정적입니다. 독일과 스위스에서는 막 단백질 의약품 연구용 고정밀 CD에 대한 투자가 계속되고 있지만, 영국에서는 브렉시트 이후 통관 절차 변경으로 인해 장비 납품에 더 긴 계획 기간이 필요해졌습니다. 동유럽의 CRO는 가격 경쟁력 있는 서비스 거점으로 부상하고 있으며, 중급급 CD 장비를 구매해 서유럽 스폰서를 유치하고 있습니다. 라틴아메리카와 중동에서는 규모는 작지만 주목할 만한 성장이 나타나고 있으며, 현지 백신 개발 이니셔티브가 파일럿 연구소 건설을 뒷받침하고 있습니다. 그러나 분광 분석 전문 인력이 제한적이고 자금 조달 주기가 불안정하여 이 지역들의 단기적인 성장을 저해하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the circular dichroism spectrometers market size was valued at USD 36.62 million in 2025 and estimated to grow from USD 39.35 million in 2026 to reach USD 56.3 million by 2031, at a CAGR of 7.44% during the forecast period (2026-2031).
This report is Segmented by Product Type (Benchtop CD Spectrometers, and More), Technology (Electronic CD (ECD), and More), Application (Protein Secondary-Structure Determination, and More), End User (Pharmaceutical & Biotechnology Companies, and More), Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Circular Dichroism Spectrometers Market Trends and Insights
Expansion of Global Biopharmaceutical Manufacturing
Biologic plants shifting toward continuous production embed CD probes directly into process lines for real-time folding validation, driving higher-throughput specifications and favoring floor-standing systems. Bruker's 2024 revenue spike of USD 3.37 billion underscores the instrumentation pull-through tied to these capital projects. Vendors now bundle automated cuvette changers and GMP-ready software, shortening operator intervention time and aligning with 21 CFR Part 11 expectations. Larger batch-release volumes encourage multi-year service contracts that lock in annuity revenue. Together, these factors add a sturdy compliance floor beneath the Circular Dichroism Spectrometers market.
Rising R&D Expenditure in Life Sciences Instrumentation
NIH's FY 2025 request of USD 50.1 billion keeps grant-backed lab upgrades on pace, while the NSF's USD 40 million protein-design initiative anchors demand for advanced structure-validation kits. Academic consortia consolidate purchasing power, opting for benchtop instruments equipped with AI-driven spectral deconvolution that handles diverse protein libraries. Procurement cycles increasingly specify multi-detector packages, rewarding manufacturers able to ship turn-key systems. These funding dynamics promote steady instrument refresh intervals, buttressing the Circular Dichroism Spectrometers market.
High Capital and Operational Costs of CD Systems
Premium systems can exceed USD 250,000 once GMP software and service agreements are added, straining capital budgets for first-time buyers. Supply-chain tariffs risk adding 10-15% to landed costs for U.S. importers of optics sub-assemblies. Operational expenses include liquid-nitrogen logistics, lamp replacements, and specialized calibrants, lifting total cost of ownership. Shared-facility models relieve part of that burden but produce reservation bottlenecks that deter time-sensitive experiments. These factors collectively temper high-growth optimism for the Circular Dichroism Spectrometers market in price-sensitive regions.
Other drivers and restraints analyzed in the detailed report include:
- Technological Innovations in Circular Dichroism Hardware
- Growing Demand for Protein Structure Analysis in Drug Discovery
- Limited Availability of Trained Spectroscopy Professionals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Benchtop units delivered a commanding 44.78% share of Circular Dichroism Spectrometers market size in 2025 by meeting everyday protein-fold screening needs of academic labs and mid-tier biotechs. Laboratories choose them for compact footprints, rapid scan modes, and optional automated plate readers. Floor-standing models, although fewer in absolute shipments, record the fastest unit growth because continuous-manufacturing lines require 24/7 reliability and higher s/n ratios. Specialty SRCD beamline configurations, housed at national light-sources, serve niche membrane-protein projects where extended wavelengths matter. The Harvard Medical School installation of dual J-1500s illustrates how benchtops remain central to high-throughput stability studies. Over the forecast, benchtops will continue to dominate replacement cycles, while floor-standing platforms capture green-field plants, keeping a balanced revenue mix inside the Circular Dichroism Spectrometers market.
In parallel, product upgrades blur lines between categories. Vendors now retrofit benchtops with robotic autosamplers once exclusive to large systems, letting smaller labs process 96-well plates overnight. Conversely, floor-standing models incorporate modular optics so users swap in UV, visible, or mid-IR heads without factory service visits. This feature parity compresses the historical price spread yet supports differentiated value propositions around throughput and robustness. Ultimately, evolving lab workflows ensure both product classes expand, reinforcing the broad opportunity base across the Circular Dichroism Spectrometers market.
Electronic CD still held 54.88% of Circular Dichroism Spectrometers market share in 2025 because its far-UV range delivers the alpha-helix and beta-sheet fingerprints prized by protein scientists. The method's mature validation guides ease regulatory submissions, making it the default for batch-release assays. Synchrotron Radiation CD, while confined to beamline access, posts the briskest CAGR as national facilities open industrial queue time and deliver wavelengths down to 170 nm unattainable on conventional optics. Vibrational CD elbows into chiral-small-molecule QA/QC, though current users remain pharma stereochemistry groups ready to pay for quantum-cascade-laser sources. JASCO's mid-IR quantum-cascade bench system demonstrates that VCD can migrate from niche to daily workflow by shortening acquisition times from hours to minutes.
Cross-pollination among these technologies is growing. Software packages increasingly allow spectral overlay across electronic and vibrational regimes, providing a single-view protein backbone plus side-chain chirality. Portable SRCD add-ons are under evaluation, but beamtime availability stays the gating factor. Over the outlook, Electronic CD will remain the workhorse while SRCD and VCD supply premium margins, preserving a tiered pricing architecture across the Circular Dichroism Spectrometers market.
Complete Report Scope:
- By Product Type
- Benchtop CD Spectrometers
- Floor-Standing CD Spectrometers
- SRCD Beamline Instruments
- CD Microspectrometers
- By Technology
- Electronic CD (ECD)
- Vibrational CD (VCD)
- Synchrotron Radiation CD (SRCD)
- By Application
- Protein Secondary-Structure Determination
- Vaccinology & Antigen Conformation Studies
- Biosimilar & Biologic Comparability Assessments
- Quality Control / Batch Release Testing
- Drug Discovery Screening & Hit Validation
- By End-User
- Pharmaceutical & Biotechnology Companies
- Contract Research / Manufacturing Organizations (CROs/CMOs)
- Academic & Government Research Institutes
- Hospital & Diagnostic Laboratories
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 38.10% of Circular Dichroism Spectrometers market share in 2025, buoyed by mature biologics pipelines, FDA's rigorous analytical expectations, and a well-funded academic ecosystem. The NIH's 2025 appropriation of USD 50.1 billion guarantees consistent instrument refresh rates at shared facilities. A possible 10-15% tariff on critical optics assemblies could lift short-term prices, but warranty discounts and lease models cushion the blow. Canada's vaccine-manufacturing build-out amplifies regional procurement, particularly for floor-standing CD lines designed for GMP production floors.
Asia-Pacific is the fastest-expanding arena at an 8.41% CAGR through 2031, propelled by China's modern biologic clusters, India's aggressive biosimilar targets, and Japan's investment in regenerative medicine quality tools. Chinese CD vendors focus on cost-optimized benches, but global players win large-capacity orders at multinational joint-ventures needing FDA-ready validation packages. India's state-sponsored biotech parks bundle equipment financing, unlocking demand among start-ups. This regional momentum reduces historical dependency on imported second-hand gear and accelerates premium segment penetration across the Circular Dichroism Spectrometers market.
Europe exhibits balanced but slower growth, stabilizing around large pharma refurbishments and Horizon Europe research calls. Germany and Switzerland continue to invest in high-precision CD for membrane-protein drug work, while the UK's post-Brexit customs shifts require longer planning windows for instrument delivery. Eastern European CROs emerge as price-competitive service hubs, purchasing mid-tier CD units to attract western sponsors. Smaller but notable gains surface in Latin America and the Middle East, where local vaccine initiatives spur pilot lab construction. However, limited spectroscopy talent and sporadic funding cycle volatility temper near-term upside in those regions.
- Jasco
- Bruker
- Applied Photophysics
- Bio-Logic Science Instruments
- Hinds Instruments
- Thermo Fisher Scientific
- Agilent Technologies
- Shimadzu
- CRAIC Technologies
- Aviv Biomedical
- ISS
- Ocean Insight
- Quantum Design International
- HORIBA Scientific
- SpectroPolaritek
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope Of The Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Global Biopharmaceutical Manufacturing
- 4.2.2 Rising R&D Expenditure in Life Sciences Instrumentation
- 4.2.3 Technological Innovations in Circular Dichroism Hardware
- 4.2.4 Growing Demand for Protein Structure Analysis in Drug Discovery
- 4.2.5 Increasing Academic Funding for Structural Biology Research
- 4.2.6 Emergence of Integrated Spectroscopy Platforms For Process Analytical Technology
- 4.3 Market Restraints
- 4.3.1 High Capital and Operational Costs of CD Systems
- 4.3.2 Limited Availability of Trained Spectroscopy Professionals
- 4.3.3 Growing Preference for High-Resolution Alternative Methods
- 4.3.4 Regulatory Validation Challenges for New CD Technologies
- 4.4 Regulatory Landscape (FDA, EMA, ICH Q5E, USP <781>)
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat Of New Entrants
- 4.6.2 Bargaining Power Of Buyers
- 4.6.3 Bargaining Power Of Suppliers
- 4.6.4 Threat Of Substitutes
- 4.6.5 Intensity Of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Benchtop CD Spectrometers
- 5.1.2 Floor-Standing CD Spectrometers
- 5.1.3 SRCD Beamline Instruments
- 5.1.4 CD Microspectrometers
- 5.2 By Technology
- 5.2.1 Electronic CD (ECD)
- 5.2.2 Vibrational CD (VCD)
- 5.2.3 Synchrotron Radiation CD (SRCD)
- 5.3 By Application
- 5.3.1 Protein Secondary-Structure Determination
- 5.3.2 Vaccinology & Antigen Conformation Studies
- 5.3.3 Biosimilar & Biologic Comparability Assessments
- 5.3.4 Quality Control / Batch Release Testing
- 5.3.5 Drug Discovery Screening & Hit Validation
- 5.4 By End-User
- 5.4.1 Pharmaceutical & Biotechnology Companies
- 5.4.2 Contract Research / Manufacturing Organizations (CROs/CMOs)
- 5.4.3 Academic & Government Research Institutes
- 5.4.4 Hospital & Diagnostic Laboratories
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 JASCO
- 6.3.2 Bruker
- 6.3.3 Applied Photophysics
- 6.3.4 Bio-Logic Science Instruments
- 6.3.5 Hinds Instruments
- 6.3.6 Thermo Fisher Scientific
- 6.3.7 Agilent Technologies
- 6.3.8 Shimadzu
- 6.3.9 CRAIC Technologies
- 6.3.10 Aviv Biomedical
- 6.3.11 ISS Inc.
- 6.3.12 Ocean Insight
- 6.3.13 Quantum Design International
- 6.3.14 HORIBA Scientific
- 6.3.15 SpectroPolaritek
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


