

|
시장보고서
상품코드
2123649
바코드 프린터 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Barcode Printer - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
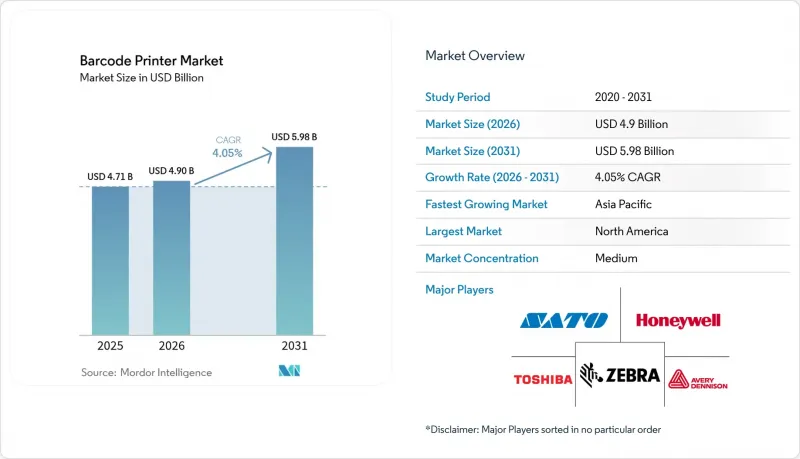
에 의하면, 바코드 프린터 시장 규모는 2025년 47억 1,000만 달러에서 2026년에는 49억 달러로 확대되어 2026년부터 2031년까지 CAGR 4.05%로 성장을 지속하여, 2031년에는 59억 8,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품 유형(데스크톱 프린터, 모바일 프린터, 산업용 프린터), 인쇄 기술(열전사, 직접 열전사, 레이저, 잉크젯, 기타), 최종 사용자 산업(제조, 소매, 운송 및 물류, 의료, 기타 최종 사용자 산업) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 바코드 프린터 시장 동향 및 인사이트
옴니채널 소매 및 전자상거래 물류의 급속한 성장
여러 채널에 걸쳐 재고를 일원화하여 관리하는 소매업체는 계절적 수요 변동에 대응하기 위해 주문 처리 센터에서 실시간으로 라벨을 인쇄해야 합니다. 아메리칸 이글 아웃피터스는 펜실베이니아주에 위치한 165만 제곱피트 규모의 물류 센터에 이미지 인식 기반 솔루션을 도입한 후, 상자 판독 정확도를 99%까지 향상시켰습니다. 이는 스캔율 향상이 얼마나 정확한 인쇄 요건으로 이어지는지를 보여줍니다. 블루 스카이 디스트리뷰션(Blue Sky Distribution)은 주문형 인쇄와 배송 경로 관리 소프트웨어를 연동한 결과, 주문 정확도 100%를 달성하고 주문 처리 효율을 80% 향상시켰습니다. 이를 통해 주문량이 70% 증가했음에도 불구하고 당일 배송 오류를 줄일 수 있었습니다. 소매업체들은 현재 피킹 카트에 모바일 프린터를 도입하여 고정 설비로 인한 병목 현상을 해소함으로써 창고 현장의 유연성을 높이고 있습니다. 또한 IT 팀이 펌웨어나 보안 패치를 원격으로 관리할 수 있도록 클라우드 기반 모니터링에 대한 수요도 증가하고 있습니다. 이러한 수요에 따라 바코드 프린터 시장은 무선 연결이 가능하고 내구성이 뛰어나며, 통합 대시보드를 통해 유지보수가 가능한 기기로 변화하고 있습니다.
AIDC를 도입하는 ‘인더스트리 4.0’ 주도의 스마트 팩토리
스마트 팩토리에서는 자동 식별 및 데이터 수집(AIDC)을 활용하여 생산 자산을 ERP 및 MES 플랫폼과 직접 연동하고 있습니다. Zebra사의 고정식 스캐너 ‘FS42’는 신경망 처리 기능을 통합하여 코드를 검사하는 동시에, 생산 라인상의 결함을 감지하는 AI 모델에 데이터를 공급합니다. 바코드 프린터가 일련번호를 공장 네트워크로 전송함으로써, 부품 ID를 기반으로 한 예측 유지보수 프로그램이 가능해집니다. Brady Corporation의 조사에 따르면, 인쇄된 코드를 기반으로 한 자동 데이터 입력으로 수동 입력 시 발생하는 오류를 최대 90%까지 줄일 수 있을 뿐만 아니라, 작업 효율을 40% 향상시킬 수 있다고 합니다. 이에 따라 제조업체들은 산업용 프로토콜, 엣지 컴퓨팅 및 대용량 처리 능력을 지원하는 프린터를 지정하고 있습니다. 그 결과, 각 산업 전반에 걸쳐 설비 투자가 둔화되고 있음에도 불구하고 하드웨어 교체 주기는 유지되고 있습니다.
열전사 프린트 헤드공급 변동 및 가격 변동
관세 및 원자재 가격의 급등으로 인해 2024년에는 감열지의 비용이 두 자릿수 상승을 기록했습니다. 프린트 헤드 제조는 동아시아의 소수 전문 공장에 집중되어 있으며, 직접 열전사 모드에서는 열전사 모드에 비해 교체용 헤드의 마모 속도가 25-50% 더 빠릅니다. 각 OEM 업체는 더 많은 재고를 확보해야 하므로, 이로 인해 운전 자본 수요가 증가하고, 최종 사용자 대상 가격 상승을 초래하고 있습니다. 구매자들이 부품 비용의 정상화를 기다리면서 일부 프로젝트가 지연되고 있습니다. 장기적으로는 각 제조업체들이 다중 공급업체 전략을 검토하고 있으나, 자본 측면의 장벽으로 인해 공급 다각화는 제한적인 수준에 그치고 있습니다.
부문 분석
2025년에는 산업용 프린터가 바코드 프린터 시장의 56.60%를 차지하며 가장 높은 매출을 기록했습니다. 이러한 장치는 넓은 미디어 폭, 강철 섀시, 24시간 연속 가동을 초과하는 듀티 사이클을 갖추고 있어 제조업체와 물류 허브는 가동 시간을 중시하고 있습니다. SATO사의 CL4NX Plus는 14 ips의 인쇄 속도를 실현하는 동시에, 펌웨어를 통해 프린트 헤드의 마모 상태를 추적하여 예측에 기반한 부품 교체를 가능하게 합니다. 그럼에도 불구하고, 긱 경제에 종사하는 택배 기사, 현장 엔지니어, 매장 내 피킹 담당자 등이 작업자와 함께 이동할 수 있는 경량 기기를 요구함에 따라, 모바일 단말기 시장 규모는 2031년까지 연평균 성장률(CAGR) 5.95%를 나타낼 것으로 전망됩니다. 모바일형 바코드 프린터 시장 규모는 2025년 10억 2,000만 달러에서 2031년에는 14억 4,000만 달러로 확대될 것으로 예측되며, 이는 휴대성이 고객의 기대를 재정의하고 있음을 보여줍니다. 데스크톱 프린터는 수용 가능한 가동 주기와 합리적인 설비 투자를 모두 충족하기 때문에 중소기업 사이에서 계속해서 지지를 받고 있습니다. 산업용 엔진을 카트형 플랫폼에 탑재한 하이브리드 설계는 제품 라인의 경계를 모호하게 만들 가능성이 있으며, 향후 세분화는 폼 팩터가 아닌 워크플로우에 따라 결정될 것임을 시사합니다.
출하 대수 기준으로 볼 때, 다중 라인 공장이 재공품 관리표를 위해 프린터 군을 도입하고 있기 때문에 산업용 프린터가 여전히 절대 수에서 가장 많은 출하 대수를 차지하고 있습니다. 그러나 중국 OEM 제조업체들의 가격 경쟁 심화로 인해 중급 제품의 이익률은 압박을 받고 있습니다. 모바일 프린터의 평균 판매 가격(ASP)은 구매자들이 배터리 구동 시간, 무선 보안, 낙하 내구성을 중시하기 때문에 비교적 견조한 추세를 유지하고 있습니다. 예측 기간 동안 산업용 SKU의 혁신은 연결성 업그레이드, 이더넷, 블루투스 5, WPA3를 중심으로 진행되는 한편, 모바일 SKU는 경량화와 의료 분야용 항균 케이스를 경쟁의 핵심으로 삼을 것입니다. 확고히 자리 잡은 산업용 수요와 기동성이 뛰어난 모바일 제품의 도입이 공존하고 있다는 점은 특정 부문이 성숙기에 접어들더라도 바코드 프린터 시장이 성장할 수 있음을 뒷받침합니다.
지역별 분석
2025년, 북미는 바코드 프린터 시장의 31.40%를 차지했습니다. 미국 우정공사의 수천 대에 달하는 Zebra 제조 장치 교체 등 연방 정부의 조달이 하드웨어 판매 대수를 뒷받침하고 있습니다. 또한, 의약품 공급망 관련 법률에 따라 병원과 약국은 GS1 DataMatrix 미디어를 지원하는 프린터에 투자해야 할 의무가 있습니다. 캐나다 소매업의 현대화와 멕시코 마키라도라의 수출이 이 지역 수요를 더욱 부추기고 있습니다. 북미 바코드 프린터 시장 규모는 2025년에 14억 8,000만 달러로 추정되며, 2031년까지 18억 6,000만 달러에 근접할 것으로 전망됩니다. 이 지역의 사용자들은 일반적으로 총 소유 비용(TCO)을 중시하며, 현장 방문 없이 펌웨어 업데이트를 예약할 수 있는 원격 플릿 관리 솔루션 도입을 추진하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 4.72%로, 가장 빠르게 성장하고 있는 시장입니다. 중국과 인도에서는 가전제품 및 의류용 신규 공장 건설이 계속되고 있으며, 두 국가 모두 수출을 위한 인라인 라벨링이 요구되고 있습니다. Gainscha사는 4만 제곱미터를 넘는 제조 공간을 운영하며, 50건의 열전사 관련 특허를 보유하고 있어 현지 기술력 향상이 두드러집니다. HPRT 보고서에 따르면, 80개국 이상에서 판매망을 전개하고 있어 중국 브랜드의 세계적 확장세를 엿볼 수 있습니다. 일본은 자동차 공장에서 인더스트리 4.0의 통합을 추진하는 한편, 동남아시아에서는 니어쇼어링이 진행되면서 라벨링 장비 수요가 남쪽으로 이동하고 있습니다. 아시아태평양의 바코드 프린터 시장 규모는 2025년에 13억 3,000만 달러에 달할 것으로 예측되며, 2031년까지 17억 5,000만 달러를 넘어설 것으로 전망됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the barcode printer market size is expected to grow from USD 4.71 billion in 2025 to USD 4.9 billion in 2026 and is forecast to reach USD 5.98 billion by 2031 at 4.05% CAGR over 2026-2031.
This report is Segmented by Product Type (Desktop Printers, Mobile Printers, Industrial Printers), Printing Technology (Thermal Transfer, Direct Thermal, Laser, Inkjet, Others), End-User Industry (Manufacturing, Retail, Transportation and Logistics, Healthcare, Other End-User Industries), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Barcode Printer Market Trends and Insights
Omnichannel retail and e-commerce logistics boom
Retailers that manage unified inventories across multiple channels need labels printed in real time at fulfillment sites to cope with seasonal demand swings. American Eagle Outfitters lifted carton reading accuracy to 99% after installing image-based solutions in its 1.65 million sq ft Pennsylvania distribution center, illustrating how higher scan rates feed back into precise print requirements. Blue Sky Distribution recorded 100% order accuracy and an 80% jump in fulfillment efficiency once it synchronized on-demand printing with routing software, which cut single-day delivery errors as orders rose 70%. Retailers now deploy mobile printers on picking carts to remove stationary bottlenecks, enhancing flexibility on warehouse floors. Demand for cloud oversight is also rising so that IT teams can manage firmware and security patches remotely. These needs push the barcode printer market toward devices that are wireless, rugged, and serviceable through centralized dashboards.
Industry 4.0-driven smart factories adopting AIDC
Smart factories rely on automated identification and data capture to link production assets directly with ERP and MES platforms. Zebra's FS42 fixed scanner integrates neural processing to inspect codes and feed AI models that flag defects on the line. When barcode printers relay serial numbers to plant networks, they enable predictive maintenance programs that rely on component IDs. Brady Corporation observed that automated data entry based on printed codes can eliminate up to 90% of manual typing errors while increasing lifting efficiency by 40%. Manufacturers therefore specify printers that support industrial protocols, edge computing, and high-volume throughput. The result is sustained hardware refresh cycles despite the broader slowdown in capital expenditure across sectors.
Supply volatility and price swings for thermal printheads
Tariffs and rising input prices pushed thermal paper costs up by double digits in 2024. Printhead fabrication is concentrated among a handful of specialist plants in East Asia, and replacement heads wear 25-50% faster in direct thermal modes than in thermal transfer settings. OEMs must stock larger buffers, elevating working capital needs and pushing end-user prices higher. Some projects have slipped because buyers wait for component costs to normalize. Longer term, manufacturers are evaluating multi-supplier strategies, yet the capital barrier keeps supply diversity modest.
Other drivers and restraints analyzed in the detailed report include:
- Cold-chain traceability demand in healthcare and food
- Mobile and wearable barcode printers enhancing field productivity
- Migration toward QR / RFID reducing basic barcode demand
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Industrial printers produced the highest revenue in 2025 by securing 56.60% of the barcode printer market. These devices deliver wide media widths, steel chassis, and duty cycles that exceed 24-hour operation, which manufacturers and logistics hubs value for uptime. SATO's CL4NX Plus prints at 14 ips while tracking head wear in firmware, ensuring predictive part replacement. Nonetheless, mobile units record a 5.95% CAGR to 2031 as gig-economy couriers, field engineers, and in-store pickers seek lightweight devices that roam with workers. The barcode printer market size for mobile models is projected to expand from USD 1.02 billion in 2025 to USD 1.44 billion by 2031, indicating that portability is redefining customer expectations. Desktop printers keep traction among small firms because they blend acceptable duty cycles with modest capex. Hybrid designs that mount industrial engines on cart platforms may blur product lines, suggesting future segmentation will hinge on workflow rather than form factor.
In volume terms, industrial printers still ship the largest absolute unit count because multi-line factories employ fleets for work-in-process tickets. However, price aggression by Chinese OEMs is compressing margins in the mid-tier. Mobile printer ASPs have proven more resilient because buyers prioritize battery life, wireless security, and drop resistance. Over the forecast, industrial SKU turnover will center on connectivity upgrades, Ethernet, Bluetooth 5, and WPA3, while mobile SKUs will compete on weight reductions and antimicrobial casings for healthcare. The coexistence of entrenched industrial demand with agile mobile adoption underscores how the barcode printer market can grow even as one segment matures.
Complete Report Scope:
- By Product Type
- Desktop Printers
- Mobile Printers
- Industrial Printers
- By Printing Technology
- Thermal Transfer
- Direct Thermal
- Laser
- Inkjet
- Others
- By End-user Industry
- Manufacturing
- Automotive
- Electronics
- Food and Beverage
- Others
- Retail
- Transportation and Logistics
- Healthcare
- Other End-user Industries
- Manufacturing
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- GCC
- Turkey
- Israel
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 31.40% of the barcode printer market in 2025. Federal procurement, such as the United States Postal Service's refresh of thousands of Zebra devices, anchors hardware volumes. Drug supply chain laws also oblige hospitals and pharmacies to invest in printers that handle GS1 DataMatrix media. Canada's retail modernization and Mexico's maquiladora exports further reinforce regional demand. The barcode printer market size for North America is estimated at USD 1.48 billion in 2025 and will edge toward USD 1.86 billion by 2031. Users in the region typically prioritize total cost of ownership, driving adoption of remote fleet management suites that schedule firmware updates without site visits.
Asia-Pacific is the fastest-expanding arena with a 4.72% CAGR to 2031. China and India keep building new factories for consumer electronics and apparel, each requiring inline labeling for export. Gainscha operates over 40,000 sqm of manufacturing space and holds 50 thermal patents, underscoring indigenous capability gains. HPRT reports distribution in more than 80 countries, reflecting the global reach of Chinese brands. Japan advances Industry 4.0 integration in automotive plants, while Southeast Asia wins near-shoring that moves labeling equipment demand southward. The barcode printer market size in Asia-Pacific is projected at USD 1.33 billion in 2025 and should exceed USD 1.75 billion by 2031.
- Zebra Technologies Corporation
- Sato Holdings Corporation
- Honeywell International Inc.
- Toshiba Tec Corporation
- Avery Dennison Corporation
- Seiko Epson Corporation
- TSC Auto ID Technology Co. Ltd.
- Brother Industries Ltd.
- Postek Electronics Co. Ltd.
- Primera Technology Inc.
- Bixolon Co. Ltd.
- Citizen Systems Japan Co. Ltd.
- Godex International Co. Ltd.
- Wasp Barcode Technologies
- Cab Produkttechnik GmbH and Co KG
- Printronix Auto ID Inc.
- Gainscha Technology Group Ltd.
- Domino Printing Sciences plc
- IDPRT (Xiamen Hanin Co. Ltd.)
- Datamax
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Omnichannel retail and e-commerce logistics boom
- 4.2.2 Industry 4.0-driven smart factories adopting AIDC
- 4.2.3 Cold-chain traceability demand in healthcare and food
- 4.2.4 Mobile and wearable barcode printers enhancing field productivity
- 4.2.5 Cloud-native remote print management and security
- 4.2.6 Adoption of linerless labeling for ESG compliance
- 4.3 Market Restraints
- 4.3.1 Supply volatility and price swings for thermal printheads
- 4.3.2 Migration toward QR/RFID reducing basic barcode demand
- 4.3.3 Tightening e-waste directives inflating lifecycle costs
- 4.3.4 Shift to direct-part marking and laser etching in harsh industrial use
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Intensity of Competitive Rivalry
- 4.7.5 Threat of Substitute Products
- 4.8 Assessment of the Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Desktop Printers
- 5.1.2 Mobile Printers
- 5.1.3 Industrial Printers
- 5.2 By Printing Technology
- 5.2.1 Thermal Transfer
- 5.2.2 Direct Thermal
- 5.2.3 Laser
- 5.2.4 Inkjet
- 5.2.5 Others
- 5.3 By End-user Industry
- 5.3.1 Manufacturing
- 5.3.1.1 Automotive
- 5.3.1.2 Electronics
- 5.3.1.3 Food and Beverage
- 5.3.1.4 Others
- 5.3.2 Retail
- 5.3.3 Transportation and Logistics
- 5.3.4 Healthcare
- 5.3.5 Other End-user Industries
- 5.3.1 Manufacturing
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 GCC
- 5.4.5.1.2 Turkey
- 5.4.5.1.3 Israel
- 5.4.5.1.4 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Nigeria
- 5.4.5.2.3 Kenya
- 5.4.5.2.4 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Zebra Technologies Corporation
- 6.4.2 Sato Holdings Corporation
- 6.4.3 Honeywell International Inc.
- 6.4.4 Toshiba Tec Corporation
- 6.4.5 Avery Dennison Corporation
- 6.4.6 Seiko Epson Corporation
- 6.4.7 TSC Auto ID Technology Co. Ltd.
- 6.4.8 Brother Industries Ltd.
- 6.4.9 Postek Electronics Co. Ltd.
- 6.4.10 Primera Technology Inc.
- 6.4.11 Bixolon Co. Ltd.
- 6.4.12 Citizen Systems Japan Co. Ltd.
- 6.4.13 Godex International Co. Ltd.
- 6.4.14 Wasp Barcode Technologies
- 6.4.15 Cab Produkttechnik GmbH and Co KG
- 6.4.16 Printronix Auto ID Inc.
- 6.4.17 Gainscha Technology Group Ltd.
- 6.4.18 Domino Printing Sciences plc
- 6.4.19 IDPRT (Xiamen Hanin Co. Ltd.)
- 6.4.20 Datamax
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


