

|
시장보고서
상품코드
2123653
배변 관리 시스템 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Bowel Management Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
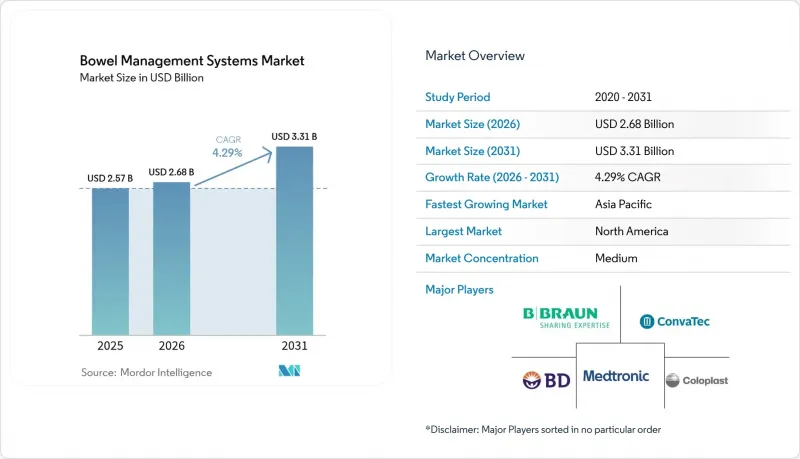
에 의하면, 배변 관리 시스템 시장 규모는 2025년 25억 7,000만 달러로 평가되었고, 2026년에는 26억 8,000만 달러로 추정되고, 2026-2031년 CAGR 4.29%로 성장을 지속할 전망이며, 2031년에는 33억 1,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품별(오스토미 백(콜로스토미 백 등), 경항문 세척 시스템, 신경 조절 기기, 기타), 환자 유형별(소아, 성인, 고령자), 최종 사용자별(병원, 외래수술센터(ASC), 재택 간호 시설, 전문 요양 시설), 지역별(북미, 유럽, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 배변 관리 시스템 시장 동향 및 인사이트
염증성 장 질환의 높은 유병률
염증성 장 질환은 미국 성인 310만 명에게 영향을 미치고 있으며, 산업화가 진행 중인 국가에서는 유병률이 상승하고 있어 오스토미 용품에 대한 수요가 지속되고 있습니다. 생물학적 제제에 반응하지 않는 환자에 대한 조기 외과적 개입으로 인해 진단부터 장루 형성까지의 기간이 단축되었으며, 이는 복잡한 복부 형태에도 잘 맞는 볼록형 배리어를 갖춘 대용량 파우치의 판매를 촉진하고 있습니다. 의료기기 제조업체들은 증상이 활발한 시기의 냄새를 억제하는 고성능 필터를 탑재한 제품으로 이에 대응하고 있으며, 이 기능은 학교나 직장으로 복귀하는 젊은 크론병 환자들로부터 높은 평가를 받고 있습니다. 임상의들은 일시적 회장 장루 성형술과 재건적 직장-결장 절제술을 병행하는 사례가 증가하고 있으며, 이를 통해 장루 주머니 교체 주기가 지속적으로 확보되고 있습니다. 이러한 추세로 인해 생물학적 제제로 인해 일부 수술이 지연되더라도 배변 관리 시스템 시장의 판매량은 안정적인 추세를 유지하고 있습니다.
급속히 증가하는 고령 인구
2050년까지 65세 이상 성인은 15억 명에 달할 것으로 예상되며, 재택 고령자의 대변 실금 유병률은 14.1%, 요양 시설에서는 최대 70%에 이를 것으로 전망됩니다. 고령화에 따라 골반저근의 약화, 다제 병용, 신경성 장 기능 장애가 증가함에 따라 일회용 파우치 및 신경 조절 임플란트의 적응증 환자층이 확대되고 있습니다. 일본의 요양보험에서는 현재 전자 세척 및 천골 신경 평가 비용이 급여 대상으로 포함되어 있으며, 이는 고령자가 자택에서 생활할 수 있도록 지원하는 고액 의료기기에 대한 자금 제공에 보험자가 적극적인 태도를 보이고 있음을 나타냅니다. 중국의 각 성에서는 오스토미 용품이 필수 의약품 목록에 포함되어 있으며, 독일에서는 경골 신경 자극 요법의 비용을 공적 자금으로 충당하고 있어 치료법의 보급이 진전되고 있습니다. 각 공급업체들은 관절염으로 인한 손의 불편함이나 시력 저하에 대응할 수 있도록 폐쇄 클립, 핑거 탭, 색상 코딩을 재설계하고 있으며, 이를 통해 배변 관리 시스템 시장에서 고령층의 충성도를 더욱 공고히 하고 있습니다.
보존적·비침습적 치료에 대한 환자의 선호도
2024년 조사에 따르면, 대변 실금 환자의 68%가 장루 형성보다 식이 요법이나 물리치료를 선호하여 파우치로 전환하는 시기가 늦어지고 있습니다. 눈에 보이는 의료기기에 대한 문화적 편견이 아시아, 라틴아메리카, 중동에서 주저함을 가중시키고 있습니다. 경골 신경 자극 요법은 침습성이 낮은 대안이지만, 치료 세션의 30-40%에서는 지속적인 증상 조절을 얻지 못해, 환자들은 불충분한 증상 완화와 영구적인 배설 경로 변경에 대한 거부감 사이에서 갈등하고 있습니다. 주사용 증량제나 자기 괄약근 역시, 그렇지 않았다면 장루 시스템을 채택했을지도 모르는 환자층을 흡수하고 있습니다. 이러한 보수적인 태도가 배변 관리 시스템 시장의 초기 단계 수요를 억제하고 있습니다.
부문 분석
신경 조절 장치는 2026-2031년 6.25%라는 가장 높은 연평균 성장률(CAGR)을 기록할 전망입니다. 이는 보험 적용과 이식을 간소화하는 소형 리드선의 혜택 덕분입니다. 오스토미 백은 2025년 시점에서도 배변 관리 시스템 시장 규모의 48.54%를 차지하고 있지만, 대장 외과 의사들이 괄약근 보존술을 채택함에 따라 점유율을 점차 내주고 있습니다. 파우치 부문에서는 좌측 절제술 증가로 인해 콜로스토미 백이 주류를 이루고 있지만, 염증성 장질환(IBD)의 수술 건수가 증가함에 따라 일레오스토미 백의 성장이 가속화되고 있습니다. 경항문 세척 시스템, 특히 프로그래밍 가능한 전자식 시스템은 독일과 영국에서 보험 적용이 확대되고 있으며, S자 결장 스토마의 대안으로 주목받고 있습니다. 항문 임플란트와 자기 괄약근은 2024년 Implantica의 기기가 FDA로부터 인도적 승인을 받은 데 힘입어, 규모는 작지만 높은 수익률을 보이는 틈새 시장을 개척하고 있습니다. 부속품 수요는 파우치 교체 빈도에 비례하여 확대되고 있으며, 7일간 착용을 가정하여 설계된 하이드로콜로이드 링은 눈에 띄지 않는 것을 중시하는 운동선수들 사이에서 호조를 보이고 있습니다.
각 공급업체는 배리어, 벤트 필터, 탈취제 향 주머니를 베이스 플레이트와 세트로 판매함으로써 리스크를 분산하고, 환자 1인당 평균 판매 가격을 높이고 있습니다. 재활용 가능한 파우치 필름은 EU의 입찰을 뒷받침하고 있으며, 데운 생리식염수를 주입하는 전자 펌프는 만성 변비 관리 분야에서 채택 범위를 넓히고 있습니다.
지역별 분석
북미는 천골 신경 자극 요법에 대한 메디케어 적용 범위 확대와 공인된 상처·장루·요실금 간호사의 긴밀한 네트워크 덕분에 2025년 배변 관리 시스템 시장 규모의 38.23%를 차지했습니다. 2024년 전국 적용 결정(NCD)에 따라 사전 승인 지연이 해소되어 연간 약 12만 명의 대변 실금 환자가 새롭게 적용 대상이 되었습니다. Eleven Health의 블루투스 지원 파우치 시스템은 15개의 통합 의료 네트워크에 도입되어 있으며,월50-65달러의 원격 모니터링 요금을 수익으로 얻고 있습니다. 캐나다에서는 온타리오주와 브리티시컬럼비아주에서 필수 급여 목록이 확대되어 환자의 본인 부담금이 감소했습니다. 멕시코에서의 성장은 주로 의료 관광객을 치료하는 민간 클리닉에 집중되어 있으며, 공립 병원에서는 기본적인 2피스 시스템 도입이 진행되고 있습니다.
아시아태평양은 중국의 2억 9,700만 명의 고령자와 현재 장루 주머니 및 세척에 자금을 지원하고 있는 인도의 ‘아유슈만 바라트’ 패키지에 힘입어 6.62%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 상하이와 광둥성에서는 경골 신경 자극 요법에 대한 보험 환급을 시범적으로 시행하고 있는 반면, 일본의 간병보험에서는 전자 세척 장치에 대한 보조금이 지급되고 있습니다. 호주의 의약품 급여 제도(PBS)는 2024년에 천골 신경 자극 요법을 추가하여 2만 5,000호주달러의 임플란트 비용을 환급하고 있습니다. 한국에서는 1년 치 파우치 공급을 포함한 대장 질환 치료 패키지를 시범 도입하고 있으며, 이는 이 지역 전체에서 지불 주체가 가치 기반 계약으로 전환되고 있음을 보여줍니다.
유럽의 배변 관리 시스템 시장은 2024년 MDR(의료기기 규정) 재인증에 따른 공급 차질로 인해 부속품 SKU의 30%가 매장에서 사라진 상황에서도 완만한 성장을 보이고 있습니다. 독일의 공적 의료보험은 경골 신경 자극 요법을 급여 대상으로 지정하여, 이를 통해 8만 명의 환자가 혜택을 받게 되었습니다. 잉글랜드 국민보건서비스(NHS)는 인공 항문용 제품을 대장 외과 수술의 요금 체계에 포함시켜, 재입원을 억제하는 고품질 볼록형 배리어의 구매를 촉진하고 있습니다. 프랑스와 이탈리아에서는 콜로플라스트사의 네덜란드 프로그램을 모델로 한, 순환 경제 기반의 파우치 회수 제도 도입이 추진되고 있습니다. 중동 및 아프리카에서는 시장이 아직 발전 단계에 있으며, GCC(걸프협력회의) 회원국의 민간 병원이 주재원을 위해 프리미엄 시스템을 수입하는 한편, 남아프리카공화국의 공공 부문에서는 2피스형 파우치의 대량 팩이 구매되고 있습니다. 남미에서는 브라질의 민간 보험사가 신경 조절 요법의 비용을 부담하고 있지만, 공공 의료 분야에서는 공급 부족이 지속되어 부유한 대도시권 이외의 지역에서는 보급률이 여전히 낮은 상태입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the bowel management systems market size is expected to grow from USD 2.57 billion in 2025 to USD 2.68 billion in 2026 and is forecast to reach USD 3.31 billion by 2031 at 4.29% CAGR over 2026-2031.
This report is Segmented by Product (Ostomy Bags [Colostomy Bags, and More], Transanal Irrigation Systems, Nerve Modulation Devices, and More), Patient Type (Pediatric, Adult, Geriatric), End User (Hospitals, Ambulatory Surgery Centers, Home Care Settings, and Skilled Nursing Facilities), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Bowel Management Systems Market Trends and Insights
High Incidence of Inflammatory Bowel Disease
Inflammatory bowel disease affects 3.1 million U.S. adults, while incidence climbs in industrializing economies, sustaining demand for ostomy supplies. Earlier surgical intervention among biologic-therapy non-responders reduces the window from diagnosis to stoma creation, driving sales of high-output pouches with convex barriers that fit complex abdomens. Device makers respond with deeper filters that tame odor during active flares, an attribute valued by younger Crohn's patients returning to school or work. Clinicians increasingly pair temporary ileostomies with restorative proctocolectomy, ensuring continued ostomy-bag replacement cycles. These patterns keep the bowel management systems market on a stable volume trajectory even if biologics delay some surgeries.
Rapidly Growing Geriatric Population
Adults aged 65 and over will reach 1.5 billion by 2050, with fecal-incontinence prevalence at 14.1% among community dwellers and up to 70% in nursing homes. Aging magnifies pelvic-floor weakness, polypharmacy, and neurogenic bowel, expanding the candidate base for disposable pouches and neuromodulation implants. Japan's long-term-care insurance now reimburses electronic irrigation and sacral nerve evaluation, signaling payer willingness to fund high-ticket devices that keep seniors at home. Chinese provinces include ostomy supplies on essential-drug lists, and Germany finances tibial nerve stimulation, boosting therapy penetration. Suppliers are redesigning closure clips, finger tabs, and color coding to suit arthritic hands and low vision, further embedding geriatric loyalty in the bowel management systems market.
Patient Preference for Conservative/Non-Invasive Care
A 2024 survey showed 68% of fecal-incontinence patients favor diet or physiotherapy over stoma formation, delaying conversion to pouch use. Cultural stigma around visible appliances amplifies hesitation in Asia, Latin America, and the Middle East. Tibial nerve stimulation offers a lower-invasiveness bridge, yet 30-40% of sessions fail to deliver durable control, leaving patients oscillating between suboptimal symptom relief and reluctance to pursue permanent diversion. Injectable bulking agents and magnetic sphincters also absorb candidates who might otherwise adopt ostomy systems. This conservatism tempers early-stage demand in the bowel management systems market.
Other drivers and restraints analyzed in the detailed report include:
- Reimbursement Expansion in High-Income Markets
- Smart-Sensor Ostomy Pouches Enable Remote Monitoring
- Post-Operative Infections & Device-Recall Headwinds
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Nerve-modulation devices logged the highest 6.25% CAGR between 2026 and 2031, benefiting from policy coverage and miniaturized leads that simplify implantation. Ostomy bags, though still 48.54% of the bowel management systems market size in 2025, are ceding share as colorectal surgeons adopt sphincter-sparing protocols. Within pouches, colostomy variants dominate due to left-sided resections, but ileostomy lines grow faster on rising IBD surgeries. Transanal irrigation systems, especially programmable electronic types, gain reimbursement in Germany and the U.K., offering an alternative for sigmoid stomas. Anal implants and magnetic sphincters open a small but high-margin niche after the FDA's humanitarian approval of Implantica's device in 2024. Accessory demand scales with pouch rotation; hydrocolloid rings designed for seven-day wear sell briskly to athletes who value discretion.
Suppliers hedge by bundling barriers, vent filters, and deodorizer sachets with baseplates, raising average selling price per patient episode. Recyclable pouch films bolster EU tenders, and electronic pumps with warmed saline broaden adhesion for chronic-constipation management.
Complete Report Scope:
- By Product
- Ostomy Bags
- Colostomy Bags
- Ileostomy Bags
- Urostomy Bags
- Transanal Irrigation Systems
- Manual Pump-based Irrigation
- Electronic Smart Irrigation
- Nerve Modulation Devices
- Sacral Nerve Stimulation Systems
- Tibial Nerve Stimulation Systems
- Anal Implants & Artificial Sphincters
- Hydraulic Artificial Sphincters
- Magnetic Sphincters
- Skin Barriers & Accessories
- Skin Barrier Sheets & Rings
- Deodorizing Filters & Pouch Accessories
- Ostomy Bags
- By Patient Type
- Pediatric (<18 yrs)
- Adult (18-64 yrs)
- Geriatric (65+ yrs)
- By End User
- Hospitals
- Ambulatory Surgery Centers
- Home Care Settings
- Skilled Nursing Facilities
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 38.23% of bowel management systems market size in 2025 thanks to Medicare coverage for sacral nerve stimulation and a dense network of certified wound-ostomy-continence nurses. The 2024 National Coverage Determination removed prior-authorization lag, adding roughly 120,000 fecal-incontinence beneficiaries per year. Eleven Health's Bluetooth pouch system is live at 15 integrated delivery networks earning USD 50-65 monthly remote-monitoring fees. Canada broadened essential-benefit lists in Ontario and British Columbia, trimming patient copay. Mexico's growth sits mostly in private clinics treating medical tourists, with government hospitals buying basic two-piece systems.
Asia-Pacific posts the fastest 6.62% CAGR, propelled by China's 297 million seniors and India's Ayushman Bharat package that now funds ostomy bags and irrigation. Shanghai and Guangdong pilot reimbursement for tibial nerve stimulation, while Japan's long-term-care insurance subsidizes electronic irrigation. Australia's Pharmaceutical Benefits Scheme added sacral nerve stimulation in 2024, reimbursing the AUD 25,000 implant. South Korea pilots bundled colorectal episodes including a year of pouch supply, signaling payer migration to value contracting across the region.
Europe's bowel management systems market grows modestly amid MDR recertification bottlenecks that forced 30% of accessory SKUs off shelves in 2024. Germany's statutory insurance covers tibial nerve stimulation, adding 80,000 eligible patients. NHS England bundled ostomy products into colorectal surgery tariffs, steering purchasing toward higher-quality convex barriers that curb readmissions. France and Italy test circular-economy pouch take-back modeled on Coloplast's Dutch program. The Middle East and Africa stay nascent, with GCC private hospitals importing premium systems for expatriates, while South Africa's public sector buys volume packs of two-piece bags. In South America, Brazil's private insurers fund neuromodulation, but public shortages persist, keeping penetration low outside affluent metros.
- Abena A/S
- Axonics Inc.
- B. Braun
- Beckton Dickinson
- Boston Scientific
- Cardinal Health
- Coloplast
- Consure Medical
- ConvaTec Group plc
- Cook MyoSite
- Hollister
- Implantica AG
- Laborie Medical Technologies
- Medtronic
- Qufora A/S
- Salts Healthcare
- Solventum Corporation
- Wellspect Healthcare
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 High incidence of inflammatory bowel disease (IBD)
- 4.2.2 Rapidly growing geriatric (65+) population
- 4.2.3 Reimbursement expansion in high-income markets
- 4.2.4 Smart-sensor ostomy pouches enable remote monitoring
- 4.2.5 ESG-driven shift to recyclable, bio-based single-use materials
- 4.3 Market Restraints
- 4.3.1 Patient preference for conservative/non-invasive care
- 4.3.2 Post-operative infections & device-recall headwinds
- 4.3.3 High upfront cost of sacral-nerve stimulation implants
- 4.3.4 Regulatory scrutiny on single-use plastic waste
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Ostomy Bags
- 5.1.1.1 Colostomy Bags
- 5.1.1.2 Ileostomy Bags
- 5.1.1.3 Urostomy Bags
- 5.1.2 Transanal Irrigation Systems
- 5.1.2.1 Manual Pump-based Irrigation
- 5.1.2.2 Electronic Smart Irrigation
- 5.1.3 Nerve Modulation Devices
- 5.1.3.1 Sacral Nerve Stimulation Systems
- 5.1.3.2 Tibial Nerve Stimulation Systems
- 5.1.4 Anal Implants & Artificial Sphincters
- 5.1.4.1 Hydraulic Artificial Sphincters
- 5.1.4.2 Magnetic Sphincters
- 5.1.5 Skin Barriers & Accessories
- 5.1.5.1 Skin Barrier Sheets & Rings
- 5.1.5.2 Deodorizing Filters & Pouch Accessories
- 5.1.1 Ostomy Bags
- 5.2 By Patient Type
- 5.2.1 Pediatric (<18 yrs)
- 5.2.2 Adult (18-64 yrs)
- 5.2.3 Geriatric (65+ yrs)
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Ambulatory Surgery Centers
- 5.3.3 Home Care Settings
- 5.3.4 Skilled Nursing Facilities
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Abena A/S
- 6.3.2 Axonics Inc.
- 6.3.3 B. Braun Melsungen AG
- 6.3.4 Becton Dickinson & Company
- 6.3.5 Boston Scientific Corp.
- 6.3.6 Cardinal Health Inc.
- 6.3.7 Coloplast A/S
- 6.3.8 Consure Medical
- 6.3.9 ConvaTec Group plc
- 6.3.10 Cook MyoSite
- 6.3.11 Hollister Incorporated
- 6.3.12 Implantica AG
- 6.3.13 Laborie Medical Technologies
- 6.3.14 Medtronic plc
- 6.3.15 Qufora A/S
- 6.3.16 Salts Healthcare Ltd
- 6.3.17 Solventum Corporation
- 6.3.18 Wellspect Healthcare
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


