

|
시장보고서
상품코드
2123661
고해상도 용융 분석 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)High-Resolution Melting Analysis - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
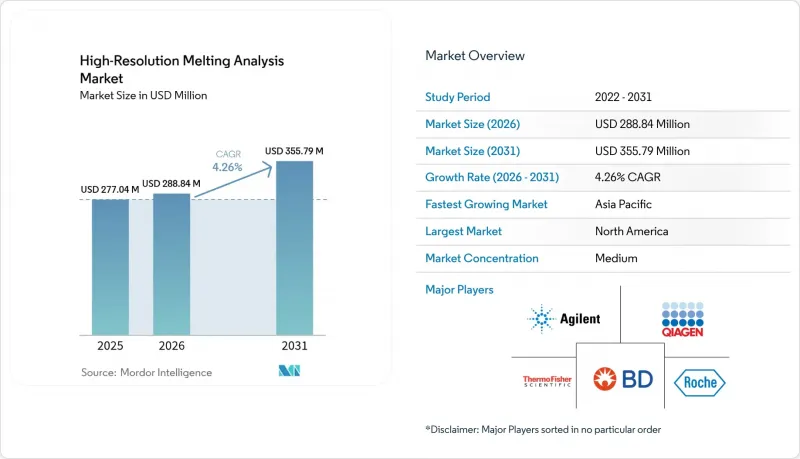
에 의하면, 2026년 고해상도 용융 분석 시장 규모는 2억 8,884만 달러로 추정되고, 2025년 2억 7,704만 달러에서 확대해, 2031년에는 3억 5,579만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 4.26%가 될 것으로 전망됩니다.
본 보고서는 제품 및 서비스별(시약 및 소모품, 기기, 소프트웨어 및 서비스), 용도별(SNP 유전형 분석, 기타), 최종 사용자별(연구소·학술 기관, 기타), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 고해상도 용융 분석 시장 동향 및 인사이트
정밀 의학 이니셔티브의 도입 확대
현재 정밀의료 프로그램은 종양학의 범위를 훨씬 넘어 순환기학, 정신 의학, 만성 질환 관리까지 확대되고 있으며, 신속한 유전자·약물 매칭 분석에 크게 의존하고 있습니다. 미국 메디케어·메디케이드 서비스 센터(CMS)는 약리유전체 검사의 보험 적용을 제안하고 있으며, 이를 통해 HRM 플랫폼은 임상적으로 유용한 변이에 대해 보험 환급을 확보할 수 있게 되었습니다. UnitedHealthcare 등 주요 보험사들은 임상적 유용성이 입증되면 일관된 보험 적용을 허용하는 방침 조정을 시작하고 있어, HRM 시약 공급업체들에게 안정적인 수익원을 창출하고 있습니다. 이에 대응하여, 각 진단 기기 제조업체들은 QIAGEN의 QIAstat-Dx가 동반 진단 부문에 진출한 사례에서 볼 수 있듯이, 1시간 이내에 유전자형 판정 결과를 제공하는 카트리지 기반 워크플로우에 HRM 모듈을 통합하여 대응하고 있습니다. 검사 비용 절감, 결과 보고까지의 시간 단축, 청구 절차의 명확화가 맞물리면서 병원 검사실에서는 일상적인 약물 반응 패널에서 샌거 시퀀싱을 대체하는 수단으로 HRM이 채택되고 있으며, 이에 따라 도입 기반이 확대되고 있습니다.
유전자 검사의 보험 급여 정책 확대
미국과 유럽의 보험 지급 기관은 제한적이고 적응증에 특화된 규정에서 분석 정확도와 임상적 유용성을 평가하는 근거 기반의 체계로 전환하고 있습니다. 『American Journal of Managed Care』지가 110건의 건강보험 플랜 정책을 추적한 조사에 따르면, 15쌍 이상의 실용적인 약물-유전자 쌍을 보장하는 플랜은 2023년부터 2025년 사이에 2배로 증가했습니다. HRM 시스템은 시퀀싱 가격의 불과 몇 분의 일 수준에서 감도 임계치에 도달하므로 대량 스크리닝에 적합하며, 그 우위를 발휘하고 있습니다. ‘유럽 의료기술평가 네트워크(ENHTA)’ 산하에서 EU 보험사들 간의 협력을 통해 국경을 넘는 보험 적용 결정이 더욱 가속화되고 있으며, 다국적 검사 기관들에게 통일된 전망이 제시되고 있습니다. 주요 플랫폼 제공업체들은 HRM 시약을 보험사용 보고서를 자동 생성하는 클라우드 포털과 세트로 판매하여 수익을 올리고 있으며, 이를 통해 소규모 지역 병원의 관리 부담을 경감시키고 있습니다.
HRM 장비에는 막대한 설비 투자가 필요합니다.
엔트리 레벨 HRM 플랫폼의 가격은 서비스 계약을 제외하고 6만-12만 달러로, 환급 수입이 불안정한 소규모 검사실에게는 진입 장벽이 되고 있습니다. 인력 부족이 이 문제를 더욱 심각하게 만들고 있습니다. 2024년 한 조사에 따르면, 미국 임상 실험실의 29.1%가 검사 기술자의 이직 문제로 어려움을 겪고 있으며, 경영진은 장비 업그레이드를 연기할 수밖에 없는 상황에 처해 있습니다. 디지털 트윈 프로젝트는 가동률 향상 및 검사 1건당 상각 비용 절감에 유망한 것으로 평가되지만, 이러한 워크플로우 최적화 소프트웨어에는 추가로 10만-20만 달러의 비용이 소요되어 총 투자액이 높은 수준을 유지하고 있습니다. 시약 임대 계약 등의 자금 조달 솔루션도 등장하고 있지만, 2024년 이후 금리 상승으로 인해 리스 비용이 증가하고 있어, 이익률이 낮은 공립병원에서의 도입은 제한적인 상황입니다.
부문별 분석
2025년에는 시약 및 소모품이 최대 매출을 창출했으며, 도입된 기기 수에 따라 확대되는 정기적인 보충 수요로 인해 매출의 49.02%를 차지했습니다. 시약에 기인한 고해상도 용융 분석 시장 규모는 1억 3,582만 달러에 달하며, 검사 메뉴의 확대에 따라 이 부문은 한 자릿수 중반대의 꾸준한 성장을 유지할 것으로 예측됩니다. 장비 매출은 연평균 성장률(CAGR) 6.41%로 확대되고 있습니다. 이는 여러 거점을 보유한 의료 시스템이 기술자의 작업 시간을 대폭 단축하고 전체 캠퍼스에서 품질을 표준화할 수 있는 통합형 자동 분석 장비에 투자하고 있기 때문입니다. 각 제조업체는 현재 장비에 클라우드 라이선스 및 검증 완료된 분석법을 묶어, 성과 기반 조달 모델에 부합하는 종합적인 계약을 구축하고 있습니다. 소프트웨어 및 서비스 매출은 여전히 총 매출의 10% 미만을 차지하고 있지만, 검사실이 데이터 분석을 24시간 365일 지원을 보장하는 공급업체 운영 플랫폼에 아웃소싱하고 있는 성숙한 시장에서 가장 빠르게 성장하고 있습니다.
지역별 분석
북미는 2025년 전 세계 매출의 41.10%를 차지했습니다. 이는 자금력이 풍부한 참조 실험실, 실용적인 유전자·약물 조합을 포괄하는 보험사의 정책, 전국 규모의 서비스 계약을 제공하는 통합된 공급업체 기반에 힘입은 것입니다. 또한, 이 지역 수요는 동반 진단과 관련된 임상 검사 활동이 활발한 점도 뒷받침하고 있으며, 이로 인해 완전 자동화된 HRM 제품군을 갖춘 계약 연구 기관(CRO)으로 대량의 검체가 유입되고 있습니다. 인력 부족은 여전히 과제로 남아 있습니다. 2024년에는 미국의 검사 기술자 공석률이 46%를 넘어설 것으로 예상되며, 이에 따라 각 네트워크는 인적 개입을 최소화하는 ‘워크어웨이(walk-away)’ 워크플로우를 갖춘 장비 도입을 추진하고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 2031년 연평균 성장률(CAGR)은 5.35%로 예측됩니다. 이는 국민 모두를 대상으로 하는 건강보험 프로그램과 호주의 5억 10만 달러 규모의 ‘유전체학 헬스 퓨처스 미션(Genomics Health Futures Mission)’과 같은 정부 자금 지원 유전체 이니셔티브에 힘입은 결과입니다. 비용 효율이 뛰어난 국산 진단약을 우선시하는 중국의 병원 조달 개혁은 HRM 기기와 정부 승인 시약 메뉴를 세트로 구성한 현지 합작 사업을 뒷받침하고 있습니다. 인도 및 필리핀의 모바일 현장 진단(PoC) 시범 사업에서는 배터리 구동식 카트리지형 HRM 검사가 도입되어, 중앙 검사실이 없는 지역의 접근성 확대에 기여하고 있습니다.
유럽에서는 학술 의료 센터의 긴밀한 네트워크와 약리유전학에 대한 지원적인 보험 환급 환경 덕분에 견조한 수요가 나타나고 있습니다. EU 의료기기 규정은 시판 후 모니터링을 통일하고 있어, 공급업체가 유럽 전역용 HRM 키트를 출시하는 데 힘을 실어주고 있습니다. 독일과 프랑스의 병원에서는 익명화된 멜트 커브 데이터를 각국의 바이오뱅크 저장소로 전송하는 클라우드 기반 분석 시스템을 도입하여, 유전체 분석 결과와 치료 성과 간의 중개 연구 연계를 가속화하고 있습니다.
중동 및 아프리카와 남미의 매출 총액은 10% 미만에 그치지만, 감염병 대책 프로그램에서 발병 대응 지침이 되는 신속한 유전자형 판정이 요구됨에 따라 검사 건수는 두 자릿수 성장을 기록하고 있습니다. 2024년 케냐에서 발생한 리프트밸리열 유행 당시, HRM을 탑재한 이동식 검사 차량의 도입으로 검체 처리 시간이 5일에서 당일 내로 단축되었으며, 이에 따라 외딴 지역의 견고한 플랫폼에 대한 수요가 높아지고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, high-resolution melting analysis market size in 2026 is estimated at USD 288.84 million, growing from 2025 value of USD 277.04 million with 2031 projections showing USD 355.79 million, growing at 4.26% CAGR over 2026-2031.
This report is Segmented by Product & Service (Reagents & Consumables, Instruments, and Software & Services), Application (SNP Genotyping, and More), End-User (Research Laboratories & Academic Institutes, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global High-Resolution Melting Analysis Market Trends and Insights
Growing Adoption of Precision Medicine Initiatives
Precision-medicine programs now stretch well beyond oncology into cardiology, psychiatry, and chronic-disease management, and they rely heavily on rapid gene-drug matching assays. The US Centers for Medicare & Medicaid Services proposed coverage for pharmacogenomic testing, enabling HRM platforms to secure reimbursement for clinically actionable variants. Leading payers such as UnitedHealthcare have started aligning policies that grant consistent coverage once clinical utility is proven, creating a stable revenue stream for HRM reagent vendors. Diagnostic manufacturers respond by embedding HRM modules into cartridge-based workflows that deliver genotyping results in under an hour, as illustrated by QIAGEN's QIAstat-Dx expansion into companion diagnostics. The combination of lower test cost, quicker turnaround, and billing clarity is driving hospital labs to replace Sanger sequencing in routine drug-response panels, thereby broadening the installed base.
Expansion of Genetic Testing Reimbursement Policies
Payers in the United States and Europe are shifting from restrictive, indication-specific rules toward evidence-based frameworks that reward analytical accuracy and clinical usefulness. An American Journal of Managed Care study tracking 110 health-plan policies showed that plans covering >=15 actionable drug-gene pairs doubled between 2023 and 2025. HRM systems gain because they reach sensitivity thresholds at a fraction of sequencing's price, which suits high-volume screening. EU payer cooperation under the European Network for Health Technology Assessment has further accelerated cross-border reimbursement decisions, giving multinational labs a uniform outlook. Large platform suppliers capitalize by bundling HRM reagents with cloud portals that auto-generate insurer-ready reports, reducing administrative overhead in small community hospitals.
High Capital Investment Required for HRM Instrumentation
Entry-level HRM platforms cost between USD 60,000 and USD 120,000, excluding service contracts, a hurdle for small labs whose reimbursement flows remain volatile. Staffing shortages compound the problem; one 2024 survey found 29.1% of US clinical labs reported difficulty retaining technologists, pushing management to delay equipment upgrades. Digital-twin projects show promise in boosting utilization and lowering amortized cost per test, yet such workflow-optimization software adds another USD 100,000-200,000, keeping total investment high. Financing solutions such as reagent-rental agreements are emerging, but interest-rate hikes since 2024 have raised leasing costs, limiting uptake in low-margin public hospitals.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Companion Diagnostics Development Pipelines
- Increasing Government Funding for Genomic Surveillance Programs
- Limited Standardization of Assay Protocols Across Laboratories
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Reagents and consumables generated the largest revenue in 2025, contributing 49.02% due to recurring refill demand that scales with installed instruments. The High-Resolution Melting Analysis market size attributable to reagents reached USD 135.82 million, and the category is forecast to maintain steady mid-single-digit growth as assay menus widen. Instrument revenue is accelerating at a 6.41% CAGR because multisite health systems invest in unified, automated analyzers that slash technician time and standardize quality across campuses. Manufacturers now bundle instruments with cloud licenses and validated assays, creating all-inclusive contracts that align with outcome-based procurement models. Software and service revenue, although still below 10% of overall value, is climbing fastest in mature markets where labs outsource data interpretation to vendor-operated platforms that guarantee 24/7 support.
Complete Report Scope:
- By Product & Service
- Reagents & Consumables
- Intercalating Dyes
- Master Mixes
- DNA Standards & Controls
- Instruments
- Real-time PCR Systems
- Digital PCR Systems (HRM-enabled)
- Compact POC Devices
- Software & Services
- Melt-curve Analysis Software
- Cloud-based Analytics & AI Services
- Validation & Training Services
- Reagents & Consumables
- By Application
- SNP Genotyping
- Mutation Discovery
- Pathogen Identification
- Methylation Analysis
- Other Applications
- By End-user
- Research Laboratories & Academic Institutes
- Pharmaceutical & Biotechnology Companies
- Hospitals & Diagnostic Centers
- Other End-users
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America produced 41.10% of global revenue in 2025, underpinned by well-funded reference labs, payer policies that cover actionable gene-drug pairs, and a consolidated supplier base that offers nationwide service contracts. The region's demand is also buoyed by high companion-diagnostic trial activity, which funnels large volumes into contract research organizations equipped with fully automated HRM suites. Workforce shortages remain a challenge; US lab-technologist vacancy rates surpassed 46% in 2024, prompting networks to adopt instruments with walk-away workflows that minimize human intervention.
Asia-Pacific is the fastest-growing territory, projected at a 5.35% CAGR through 2031, propelled by universal-health-coverage programs and government-funded genomic initiatives such as Australia's USD 500.1 million Genomics Health Futures Mission. China's hospital-procurement reforms, which favor cost-effective domestic diagnostics, are encouraging local joint ventures that bundle HRM instruments with government-approved reagent menus. Mobile point-of-care pilots in India and the Philippines showcase cartridge-based HRM tests that run off battery packs, broadening access in regions lacking central labs.
Europe commands solid demand thanks to a dense network of academic medical centers and a supportive reimbursement climate for pharmacogenomics. The EU Medical Device Regulation harmonizes post-market surveillance, aiding suppliers in launching pan-European HRM kits. Hospitals in Germany and France are integrating cloud-based analytics that route anonymized melt-curve data into national bio-bank repositories, accelerating translational research links between genomic findings and therapy outcomes.
Middle East & Africa and South America collectively capture under 10% of revenue but record double-digit test-volume growth as infectious-disease programs seek rapid genotyping to guide outbreak response. Deployment of HRM-equipped mobile vans during the 2024 Rift Valley fever outbreak in Kenya cut sample processing times from five days to same day, reinforcing demand for ruggedized platforms in remote regions.
- Thermo Fisher Scientific
- Bio-Rad Laboratories
- QIAGEN
- Agilent Technologies
- Roche
- Illumina
- Azura Genomics
- Canon
- bioMerieux
- Meridian Bioscience
- New England Biolabs
- Promega
- LGC Biosearch Technologies
- Takara Bio
- Cepheid (Danaher)
- Fluidigm
- Analytik Jena
- Pacific Bioscience
- Sysmex
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Adoption of Precision Medicine Initiatives
- 4.2.2 Expansion of Genetic Testing Reimbursement Policies
- 4.2.3 Surge in Companion Diagnostics Development Pipelines
- 4.2.4 Increasing Government Funding for Genomic Surveillance Programs
- 4.2.5 Proliferation of Decentralized Point-of-Care Molecular Testing
- 4.2.6 Integration of Cloud-Based Analytics for High-Throughput Workflows
- 4.3 Market Restraints
- 4.3.1 High Capital Investment Required for HRM Instrumentation
- 4.3.2 Limited Standardization of Assay Protocols Across Laboratories
- 4.3.3 Shortage of Skilled Molecular Diagnostics Personnel
- 4.3.4 Regulatory Uncertainty in Emerging Economies
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product & Service
- 5.1.1 Reagents & Consumables
- 5.1.1.1 Intercalating Dyes
- 5.1.1.2 Master Mixes
- 5.1.1.3 DNA Standards & Controls
- 5.1.2 Instruments
- 5.1.2.1 Real-time PCR Systems
- 5.1.2.2 Digital PCR Systems (HRM-enabled)
- 5.1.2.3 Compact POC Devices
- 5.1.3 Software & Services
- 5.1.3.1 Melt-curve Analysis Software
- 5.1.3.2 Cloud-based Analytics & AI Services
- 5.1.3.3 Validation & Training Services
- 5.1.1 Reagents & Consumables
- 5.2 By Application
- 5.2.1 SNP Genotyping
- 5.2.2 Mutation Discovery
- 5.2.3 Pathogen Identification
- 5.2.4 Methylation Analysis
- 5.2.5 Other Applications
- 5.3 By End-user
- 5.3.1 Research Laboratories & Academic Institutes
- 5.3.2 Pharmaceutical & Biotechnology Companies
- 5.3.3 Hospitals & Diagnostic Centers
- 5.3.4 Other End-users
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Thermo Fisher Scientific Inc.
- 6.3.2 Bio-Rad Laboratories Inc.
- 6.3.3 Qiagen N.V.
- 6.3.4 Agilent Technologies Inc.
- 6.3.5 F. Hoffmann-La Roche AG
- 6.3.6 Illumina Inc.
- 6.3.7 Azura Genomics
- 6.3.8 Canon Inc.
- 6.3.9 bioMerieux SA
- 6.3.10 Meridian Bioscience Inc.
- 6.3.11 New England Biolabs
- 6.3.12 Promega Corporation
- 6.3.13 LGC Biosearch Technologies
- 6.3.14 Takara Bio Inc.
- 6.3.15 Cepheid (Danaher)
- 6.3.16 Fluidigm Corporation
- 6.3.17 Analytik Jena AG
- 6.3.18 Pacific Biosciences of California Inc.
- 6.3.19 Sysmex Corporation
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


