

|
시장보고서
상품코드
2123666
히알루론산 기반 피부 필러 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Hyaluronic Acid Based Dermal Fillers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
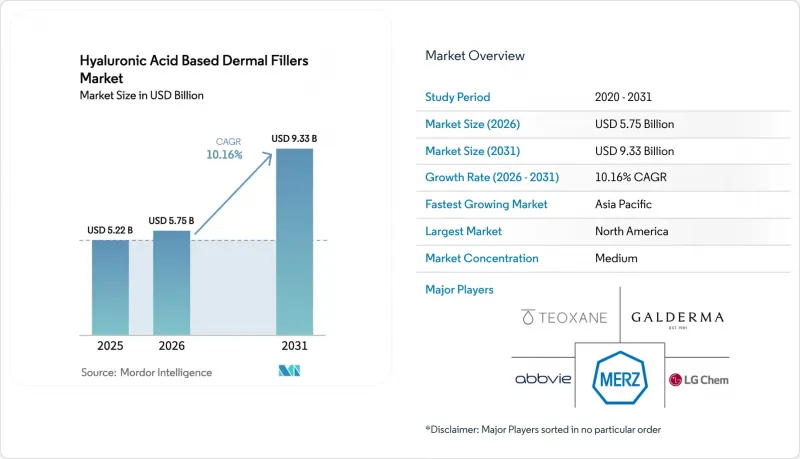
에 의하면, 히알루론산 기반 피부 필러 시장 규모는 2025년에 52억 2,000만 달러로 평가되었고, 2026년에 57억 5,000만 달러로 추정되고, 2031년까지 93억 3,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 10.16%로 성장할 전망입니다.
본 보고서는 제품 단계별(단상, 듀플렉스), 용도별(주름 개선, 흉터 치료, 볼륨 회복, 기타), 최종 사용자별(병원, 피부과 전문 클리닉, 메디컬 스파), 원료별(동물 유래, 완전 합성, 기타), 지역별(북미, 유럽, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 히알루론산 기반 피부 필러 시장 동향 및 인사이트
고령화 사회에서 저침습 미용 시술에 대한 수요 증가
인구 고령화에 따라 필러 시술 대상층이 확대되고 있으며, 2024년에는 40-54세 연령대가 미국 내 시술 건수의 50%를 차지했습니다. 2024년에는 시술 건수가 533만 건으로 증가했으나, 평균 비용은 715달러로 하락하여 많은 환자에게 있어 편의성이 비용에 대한 우려를 상회하고 있음을 뒷받침하고 있습니다. 북미와 유럽의 메디컬 스파에서 주사 시술에 대한 규제 허용 범위가 확대되어 접근성이 높아진 한편, 유지 관리를 목적으로 한 ‘미세 조정(tweakments)’이 분기별 내원 일정과 재방문 수익을 뒷받침하고 있습니다. 그 결과, 제품 공급업체와 클리닉 모두에게 이익이 되는 안정적인 시술 속도가 실현되고 있습니다.
필러의 지속 기간을 연장하는 가교 화학 분야의 급속한 제품 혁신
각 제조업체는 BDDE에서 PEGDE 및 자가 가교 폴리머 플랫폼으로 전환하고 있으며, 이를 통해 내구성이 향상되고 용해성 분획이 감소하고 있습니다. 반응 임계값이 130 mg/mL를 초과함으로써 임상 성능이 우수한 젤을 얻을 수 있습니다. 72 N 이하의 힘으로 34게이지 바늘을 통과하는 열반응성 하이드로겔은 주사 시 통증을 완화합니다. 노보자임스(Novozymes)사와 유전자 변형 코리네박테리움(Corynebacterium) 유래의 동물성 성분을 사용하지 않는 생산 균주는 45 g/L의 역가를 달성하여 발효 비용을 절감하고 현지 생산을 촉진하고 있습니다.
높은 본인 부담 비용과 짧은 지속 기간
필러의 지속 기간은 6-18개월이며, 반복적으로 발생하는 비용은 급속히 누적됩니다. 미국 내 가격은 715달러까지 하락했으나, 특히 보험 적용이 되지 않는 지역에서는 여전히 비용이 장벽으로 작용하고 있습니다. 중국의 치열한 경쟁으로 인해 소매 가격은 200위안까지 밀려 내려가 이익률을 압박하고 있습니다. LG화학이 YVOIRE를 매각한 사례에서 볼 수 있듯이, 다국적 기업들은 수익성이 낮은 부문에서 철수하고 있습니다.
부문 분석
2025년 매출액 중 듀플렉스 젤이 58.56%를 차지했으며, 볼, 턱, 턱선 시술에서 히알루론산계 진피 필러 시장 규모를 지탱하는 구조적 기반이 되고 있습니다. 이 젤은 이중상 조성으로 인해 200 Pa를 초과하는 탄성 계수를 가지며, 압축 상태에서도 형태를 유지할 수 있습니다. 한편, 단상 겔은 매끄러운 유변학적 특성으로 인해 표층 교정이나 스킨 부스터에 적합하므로 11.25%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다.
초극세 바늘을 이용한 주입이 가능한 열반응성 단상 유형은 통증 역치를 더욱 낮추고 시술 시간을 단축합니다. 규제 측면에서도 움직임이 활발해지고 있으며, 2024년 주비덤 볼마 XC의 관자놀이 부위 적응증 확대를 통해 혈관이 풍부한 부위에서 이중 구조의 안전성이 입증되었습니다.
2025년에도 주름 개선이 매출의 35.53%를 차지하며 여전히 주류를 이루었지만, 소셜 미디어상에서 볼륨감 있으면서도 균형 잡힌 입술이 보편화됨에 따라 입술 볼륨 증대 시장은 연평균 성장률(CAGR) 12.85%를 기록하며 주름 개선 시장을 앞지를 전망입니다. 테오크산(TheoXan)사의 ‘RHA 3’는 2023년에 FDA의 적응증 확대를 획득하여, 입술 전용 제품 라인에 대한 규제적 길이 열렸습니다.
중안면 및 턱의 볼륨 회복과 흉터 치료는 재건 용도의 확대에 힘입어 꾸준히 성장하고 있습니다. 조사 결과에 따르면, 섬세한 균형이 중요한 것으로 나타났습니다. 윗입술과 아랫입술의 높이 비율이 30%를 초과하는 입술은 응답자의 88%가 ‘아름답지 않다’고 평가했으며, 이러한 인사이트은 히알루론산 계열 진피 필러 시장에서 시술자의 교육 및 소비자의 기대 형성에 대한 지침이 되고 있습니다.
지역별 분석
북미는 2025년 매출의 42.13%를 차지했으며, 2024년에는 시술 비용이 하락했음에도 불구하고 미국에서 533만 건의 시술이 이루어져, 양적 성장 주도형 추세를 반영하고 있습니다. 메디컬 스파에서의 시술이 허용되면서 접근성이 확대되는 한편, EVOLYSSE FORM과 SMOOTH의 FDA 승인으로 인해 경쟁 구도가 치열해지고 있습니다. 캐나다에서의 바디 컨투어링용 ‘Restylane SHAYPE’ 도입과 멕시코에서 확대되는 미용 의료 관광은 시장에 파급 효과를 미칠 가능성을 시사하고 있습니다.
아시아태평양은 중국의 NMPA 승인 절차 효율화, 한국의 가격 경쟁 클리닉, 고령화되고 있지만 미용 의식이 높은 일본의 인구 구성에 힘입어 2031년까지 연평균 성장률(CAGR) 12.21%가 예상됩니다. 베이징 IMEIK의 RegenBIoTech 1억 9,000만 달러 인수 사례는 전략적 통합이 진행되고 있음을 여실히 보여줍니다. 2024년 Bloomage의 수출 매출이 국내 매출을 넘어선 것은 이 지역이 전 세계 수요에 대응할 수 있는 역량을 갖추고 있음을 입증합니다.
유럽은 여전히 큰 점유율을 차지하고 있지만, MDR(의료기기 규정)에 따른 증거 제출 요구로 인해 시장 출시까지의 기간이 길어지고 있으며, 이는 기존 브랜드에 유리하게 작용하고 있습니다. 갈데르마(Galderma)가 2024년 EU 주요 시장에서 ‘레스틸레인 볼륨(Restylane VOLYME)’을 출시한 것은 고성능 젤에 대한 수요가 여전히 높음을 보여줍니다. GCC의 부유층과 의료 관광에 힘입은 중동, 브라질의 미용 문화를 견인하는 라틴아메리카가 성장의 거점으로 꼽히지만, 규제 차이가 시장 진출을 복잡하게 만들고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the hyaluronic acid based dermal fillers market size is projected to be USD 5.22 billion in 2025, USD 5.75 billion in 2026, and reach USD 9.33 billion by 2031, growing at a CAGR of 10.16% from 2026 to 2031.
This report is Segmented by Product Phase (Single Phase and Duplex), Application (Wrinkle Correction, Scar Treatment, Volume Restoration, and More), End-User (Hospitals, Specialty Dermatology Clinics, and Medical Spas), Ingredient Source (Animal-Derived, Fully-Synthetic, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Hyaluronic Acid Based Dermal Fillers Market Trends and Insights
Rising Demand for Minimally-Invasive Aesthetic Procedures Among Aging Populations
Demographic aging is expanding the candidate pool for fillers, and the 40-54 cohort accounted for 50% of U.S. procedures in 2024. Procedure counts climbed to 5.33 million in 2024 even as average fees slid to USD 715, confirming that convenience outweighs cost concerns for many patients. Regulatory allowances for medical-spa injections in North America and Europe are widening access, while maintenance-oriented "tweakments" support quarterly visit schedules and repeat revenue. The result is a steady cadence of injections that benefits both product suppliers and clinics.
Rapid Product Innovation in Cross-Linking Chemistry Extending Filler Longevity
Manufacturers have shifted from BDDE to PEGDE and auto-crosslinked polymer platforms that improve durability and reduce soluble fractions, with reaction thresholds above 130 mg/mL yielding better clinical performance gels. Thermoresponsive hydrogels that pass through 34-gauge needles at forces under 72 N lessen injection pain. Animal-free production strains from Novozymes and engineered Corynebacterium have produced titers of 45 g/L, lowering fermentation cost and encouraging local manufacturing.
High Out-of-Pocket Cost Versus Short Durability
Fillers last 6-18 months, and repeat fees accumulate quickly. Although U.S. prices slipped to USD 715, cost remains a deterrent, especially in regions where insurance coverage is absent. China's aggressive competition has pushed retail prices to as low as CNY 200, hurting margins. Multinationals exit low-margin segments, as evidenced by LG Chem's sale of YVOIRE.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Male & Millennial "Pre-Juvenation" Consumer Segments
- Emergence of Micro-Droplet Skin-Booster HA Treatments Opening New Maintenance-Therapy Streams
- Heightened Regulatory Scrutiny & Adverse-Event Reporting
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Duplex gels accounted for 58.56% of 2025 revenue, giving the Hyaluronic Acid Based Dermal Fillers market size its structural backbone in cheek, chin, and jawline jobs. Their biphasic composition confers an elastic modulus above 200 Pa, enabling them to hold shape under compression. Single-phase gels, however, will post the swiftest 11.25% CAGR due to their smoother rheology, which suits superficial corrections and skin boosters.
Thermoresponsive single-phase variants, injectable via ultra-fine needles, further lower pain thresholds and shorten chair time. Regulatory traction is building; Juvederm Voluma XC's 2024 temple label expansion validated duplex safety in vascular-rich zones.
Wrinkle correction still ruled with 35.53% revenue in 2025, but lip augmentation will outstrip it at a 12.85% CAGR as social media aesthetics normalize fuller yet balanced lips. Teoxane RHA 3 gained an expanded FDA indication in 2023, opening regulated pathways for lip-specific lines.
Volume restoration for mid-face and chin, along with scar remediation, is expanding steadily, propelled by broader reconstructive uses. Research underpins subtlety: lip ratios above 30% upper-to-lower height were deemed unaesthetic by 88% of respondents, guiding injector training and shaping consumer expectations inside the Hyaluronic Acid-Based Dermal Fillers market.
Complete Report Scope:
- By Product Phase
- Single-Phase
- Duplex
- By Application
- Wrinkle Correction
- Scar Treatment
- Volume Restoration
- Lip Augmentation
- Others
- By End-User
- Hospitals
- Specialty Dermatology Clinics
- Medical Spas
- By Ingredient Source
- Animal-Derived
- Non-Animal Fermentation
- Fully-Synthetic
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America delivered 42.13% of 2025 sales, strengthened by 5.33 million U.S. procedures in 2024 despite fee declines, reflecting volume-driven growth. Medical-spa permissiveness broadens access, while FDA approvals of EVOLYSSE FORM and SMOOTH add competitive depth. Canada's adoption of Restylane SHAYPE for body contouring and Mexico's growing tourism trade signal spillover potential.
Asia-Pacific is set for a 12.21% CAGR to 2031, propelled by China's streamlined NMPA approvals, South Korea's price-competitive clinics, and Japan's aging yet aesthetics-aware demographic. Beijing IMEIK's USD 190 million purchase of RegenBiotech highlights strategic consolidation. Bloomage's export sales exceeding domestic revenue in 2024 prove the region's capacity to serve global demand.
Europe retains a sizeable slice, but MDR-driven evidence demands lengthen launch timelines, advantaging entrenched brands. Galderma's Restylane VOLYME launch across major EU markets in 2024 shows continued appetite for high-performance gels. The Middle East, buoyed by GCC wealth and medical tourism, and Latin America, led by Brazil's aesthetic culture, round out growth nodes, though regulatory heterogeneity complicates rollouts.
- Abbvie
- Anika Therapeutics
- Beijing IMEIK Technology Development
- BioPlus
- Bloomage Biotechnology Corp.
- Croma-Pharma GmbH
- Galderma
- Haohai Biological Technology Co.
- Humedix (Cleviel)
- JW Pharmaceutical (Q.O.Fill)
- LG Chem
- Medytox
- Merz Pharma
- Prollenium Medical Technologies Inc.
- Revance Therapeutics
- SciVision Biotech
- Sinclair Pharma Ltd.
- Teoxane Laboratories
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for minimally-invasive aesthetic procedures among ageing populations
- 4.2.2 Rapid product innovation in cross-linking chemistry extending filler longevity
- 4.2.3 Expansion of male & millennial pre-juvenation consumer segments
- 4.2.4 Emergence of micro-droplet skin-booster HA treatments opening new maintenance-therapy revenue streams
- 4.2.5 Tariff-driven localisation of bacterial-fermentation HA manufacturing capacity
- 4.3 Market Restraints
- 4.3.1 High out-of-pocket procedure cost versus short durability
- 4.3.2 Heightened regulatory scrutiny & adverse-event reporting (vascular occlusion, DIRs)
- 4.3.3 Supply-chain impurity controls (silicone oil, Al particulates) raising COGS
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Phase
- 5.1.1 Single-Phase
- 5.1.2 Duplex
- 5.2 By Application
- 5.2.1 Wrinkle Correction
- 5.2.2 Scar Treatment
- 5.2.3 Volume Restoration
- 5.2.4 Lip Augmentation
- 5.2.5 Others
- 5.3 By End-User
- 5.3.1 Hospitals
- 5.3.2 Specialty Dermatology Clinics
- 5.3.3 Medical Spas
- 5.4 By Ingredient Source
- 5.4.1 Animal-Derived
- 5.4.2 Non-Animal Fermentation
- 5.4.3 Fully-Synthetic
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 AbbVie Inc. (Allergan Aesthetics)
- 6.3.2 Anika Therapeutics Inc.
- 6.3.3 Beijing IMEIK Technology Development
- 6.3.4 BioPlus Co. Ltd.
- 6.3.5 Bloomage Biotechnology Corp.
- 6.3.6 Croma-Pharma GmbH
- 6.3.7 Galderma S.A.
- 6.3.8 Haohai Biological Technology Co.
- 6.3.9 Humedix (Cleviel)
- 6.3.10 JW Pharmaceutical (Q.O.Fill)
- 6.3.11 LG Chem Ltd.
- 6.3.12 Medytox Inc.
- 6.3.13 Merz Pharma GmbH & Co. KGaA
- 6.3.14 Prollenium Medical Technologies Inc.
- 6.3.15 Revance Therapeutics Inc.
- 6.3.16 SciVision Biotech Inc.
- 6.3.17 Sinclair Pharma Ltd.
- 6.3.18 Teoxane S.A.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


