

|
시장보고서
상품코드
2123672
동종요법 제품 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Homeopathy Product - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
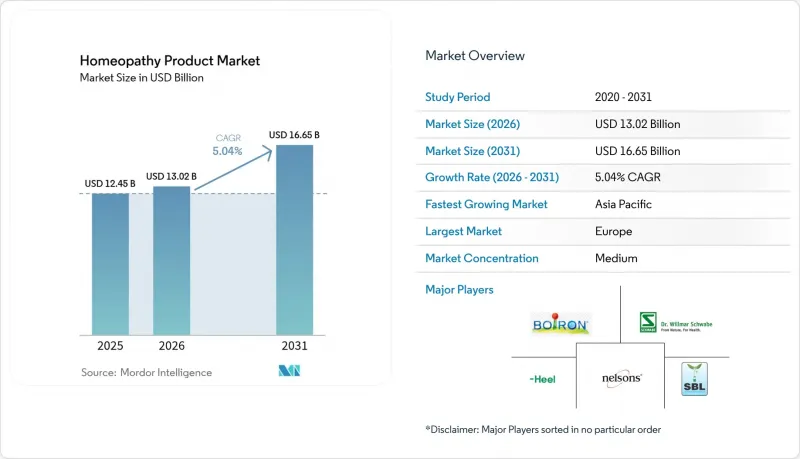
에 의하면, 동종요법 제품 시장 규모는 2025년에 124억 5,000만 달러로 평가되었고, 2026년 130억 2,000만 달러에서 2031년까지 166억 5,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.04%를 나타낼 전망입니다.
본 보고서는 제품 유형별(팅크제, 희석제, 정제, 연고·크림, 기타), 용도별(진통·해열, 호흡기 계통, 기타), 원료별(식물 유래, 동물 유래, 광물 유래), 유통 채널별(소매 약국 및 드럭스토어, 동종요법 클리닉, 기타), 지역별(북미, 유럽, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 동종요법 제품 시장 동향 및 인사이트
자연 요법 및 전체론적 의료에 대한 소비자 성향의 변화
식물 유래 및 광물 유래 치료법에 대한 선호도가 높아짐에 따라 제품 포트폴리오 재편이 진행되고 있습니다. 조사 대상 소비자의 80%가 자연주의 건강 제품에 관심을 보이는 반면, 동종요법에 대한 인지도는 60%에 그치고 있습니다. 부츠(Boots)가 2025년 6월, 동종요법 제품 라인을 포함한 300종의 웰니스 관련 SKU를 출시한 것은 이 카테고리의 성장에 대한 주류 시장의 신뢰를 보여줍니다. 밀레니얼 세대와 Z세대는 투명성과 지속가능성을 중시하고 있으며, 이에 따라 각 브랜드는 식물 유래 원료 조달에 초점을 맞추었습니다. 소매점 진열대에서 존재감이 높아지는 한편, 포텐타이제이션(희석·흔들기)에 대한 지식 부족도 존재하여, 유효성에 대한 주장에 대한 면밀한 검토가 요구되고 있습니다. 옴니채널을 통한 인식 제고 활동에 투자하고 있는 기업들은 소비자의 호기심을 재구매로 연결함으로써 타사를 압도하는 시장 점유율을 확보하고 있습니다.
자가 관리 및 예방 의료의 보급
연평균 성장률(CAGR) 6.85%로 확대되고 있는 복합형 일반의약품은 여러 증상을 간편하게 관리하고자 하는 소비자 수요를 여실히 보여주고 있습니다. 보와롱의 ‘오실로코카늄’과 하이랜드의 ‘콜드 앤 카프’는 의사의 진찰 없이 독감 유사 증상을 완화하는 것을 목적으로 하며, 팬데믹 시대에 형성된 원격 의료를 통한 자가 관리 습관으로 인해 이러한 경향은 더욱 강화되고 있습니다. 기존 치료 방식의 전문가들은 획일적인 접근 방식이 맞춤 치료 이념을 희석시킬 것이라고 경고하고 있습니다. 각 제조업체는 단일 성분 치료제를 의료 기관용 채널에, 복합 성분 치료제를 일반 소매점용으로 배치하는 단계적인 제품 포트폴리오를 통해 이러한 대립 사이에서 균형을 맞추고 있습니다.
제한된 임상적 근거와 과학적 회의론
대규모 위약 대조 시험이 수행되지 않았기 때문에 병원이나 보험사에 의한 채택은 제한적입니다. FDA의 2022년 위험 기반 지침은 유효성 검토를 제쳐두고 안전성에 초점을 맞추면서 모니터링 목록을 유지하고 있습니다. 캐나다의 2025년 면책 조항 표시 의무는 소매점 진열대에 대한 의구심을 법적으로 명문화한 것으로, 옹호 단체들은 이 조치를 법정에서 다투고 있습니다. 힐(Heel)사는 보기 드문 엄격한 프로그램을 추진하고 있으나, 그 조사 방법에 대한 비판에 직면해 있습니다. 설득력 있는 데이터가 부족하기 때문에 많은 브랜드는 일반의약품(OTC) 판매처나 의료진의 처방에 국한된 상태를 유지하고 있습니다.
부문 분석
2025년, 동종요법 제품 시장 점유율의 67.02%를 일반의약품(OTC)이 차지했습니다. 이 부문은 월그린, 월마트, 부츠를 통한 대규모 유통으로 성장하고 있으며, 하이랜드사가 2025년에 미국 내 7,400곳의 신규 판매 거점으로의 확장을 시작함에 따라 그 기세는 더욱 강해지고 있습니다. 일반의약품의 확대는 소비자의 신뢰를 높이고 1회당 구매 금액을 증가시키는 디지털 교육 캠페인과 연동되어 있습니다.
시간이 부족한 소비자들이 여러 증상을 동시에 완화하는 제품을 받아들이면서, 자가 치료용 복합 제제가 예측된 성장 가속화를 뒷받침하며 연평균 성장률(CAGR) 6.85%로 확대되고 있습니다. 보와롱사는 소아용 감기 및 독감 약 광고에 660만 달러를 투자하여, 미국 내 해당 채널의 매출을 전년 대비 11.4% 끌어올렸습니다. 의료 전문가의 영향력이 여전히 강한 독일과 인도에서는 처방약 라인이 뿌리 깊게 남아 있지만, 보험 환급 축소에 따라 동종요법 제품 시장 규모에서 차지하는 비중은 줄어들고 있습니다.
아르니카, 벨라도나, 카모밀라와 같은 성분에 대한 친숙함 덕분에 2025년에는 식물 유래 원료가 시장 규모의 60.34%를 차지했습니다. 지속가능성 노력과 클린 라벨에 대한 관심이 유럽과 북미 전역에서 시장 점유율 확대를 뒷받침하고 있습니다. 광물 유래 치료제는 의료 전문가의 조제를 통해 안정적인 수요를 유지하고 있습니다.
동물 유래의 노소드와 사르코드는 현재 소수이지만, 연평균 성장률(CAGR) 9.33%를 나타낼 것으로 예측됩니다. ‘Dr. Reckeweg’와 같은 브랜드가 만성 질환 치료 프로토콜에 대해 임상의들에게 인식을 제고함으로써 수용 범위를 넓히고 있습니다. 윤리적 조달 및 EU의 추적성 규제는 비용 및 평판 측면의 장벽이 되어 성장을 둔화시킬 가능성이 있지만, 현재로서는 그 성장세를 저해할 정도까지는 이르지 않았습니다.
지역별 분석
북미는 성숙한 OTC 채널과 디지털 구독 서비스에 힘입어 2025년 매출의 37.78%를 차지하며 시장을 주도했습니다. 미국의 소매업체들은 폭넓은 상품 구색을 선보이는 반면, 캐나다에서는 성장을 둔화시킬 가능성이 있는 2025년 면책 조항으로 인해 기회와 위험이 균형을 이루고 있습니다. 멕시코는 여전히 발전 단계에 있지만, 웰니스 관련 지출 증가의 혜택을 받고 있습니다.
유럽의 전망은 제각각입니다. 독일에서는 보험 적용 범위를 둘러싼 논란이 있음에도 불구하고, 인구의 95.1%가 이 제품에 친숙해 기초적인 수요가 유지되고 있습니다. 반면 프랑스에서는 보험 환급액 삭감으로 인해 보아롱(Boiron)사는 소매 전략의 전환을 강요받고 있습니다. 스페인, 이탈리아, 동유럽 국가들에서는 규제가 비교적 완만하여 한 자릿수 중반대의 성장이 예상됩니다. 베레다(Weleda)사가 고급 부티크에서 ‘셀 롱제비티(Cell Longevity)’를 출시한 것은 프리미엄 라인으로의 재포지셔닝을 보여줍니다.
아시아태평양은 연평균 성장률(CAGR) 7.03%를 나타낼 것으로 예측되며, 이는 지역별 중 가장 높은 성장률입니다. 인도는 30만 명의 시술자와 305억 루피에 달하는 연방 정부의 지원으로 시장을 주도하고 있습니다. 중국에서는 전통 중국 의학(TCM) 이외의 부문에서도 신중한 관심이 쏠리고 있으며, 호주에서는 TGA(호주 의약품 행정청)의 엄격한 감독이 프리미엄 가격 책정을 뒷받침하고 있습니다. 동남아시아 시장에서는 스마트폰을 활용한 원격 의료의 보급으로 새로운 시장 기회가 창출되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the homeopathy product market size was valued at USD 12.45 billion in 2025 and is estimated to grow from USD 13.02 billion in 2026 to reach USD 16.65 billion by 2031, at a CAGR of 5.04% during the forecast period (2026-2031).
This report is Segmented by Product Type (Tinctures, Dilutions, Tablets, Ointments & Creams, Others), Application (Analgesic & Antipyretic, Respiratory, and More), Source (Plant-Based, Animal-Based, Mineral-Based), Distribution Channel (Retail Pharmacies & Drugstores, Homeopathic Clinics, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Homeopathy Product Market Trends and Insights
Consumer Shift Toward Natural and Holistic Medicine
Escalating preference for plant-based and mineral-derived remedies is reshaping portfolios as 80% of surveyed consumers express interest in natural health products, yet familiarity with homeopathy lingers at 60%. Boots' June 2025 release of 300 wellness SKUs, including homeopathic lines, signals mainstream confidence in category growth. Millennials and Gen Z emphasize transparency and sustainability, prompting brands to spotlight botanical sourcing. Retail shelf gains coexist with knowledge gaps around potentization, inviting scrutiny over efficacy claims. Firms investing in omnichannel education capture outsized share as they translate curiosity into repeat purchase.
Self-Care and Preventive Health Adoption
Combination OTC remedies, expanding at a 6.85% CAGR, illustrate consumer demand for simplified multi-symptom control. Boiron's Oscillococcinum and Hyland's Cold'n Cough target flu-like syndromes without consultation, a habit reinforced by pandemic-era telehealth autonomy. Classical practitioners caution that a one-size-fits-all approach dilutes an individualized philosophy. Manufacturers straddle this divide through tiered portfolios that place single remedies in clinic channels and blends in mass retail.
Limited Clinical Evidence and Scientific Skepticism
The absence of large-scale placebo-controlled trials limits hospital and insurer adoption. FDA's 2022 risk-based guidance sidelines efficacy considerations, focusing on safety while maintaining a watchlist. Canada's 2025 disclaimer mandate codifies doubt on retail shelves, and advocacy groups challenge the policy in court. Heel undertakes the rare rigorous program yet faces methodology critiques. Without compelling data, many brands stay confined to OTC aisles and practitioner scripts.
Other drivers and restraints analyzed in the detailed report include:
- Aging Population and Chronic Disease Prevalence
- Regulatory Recognition and Healthcare Integration
- Regulatory Fragmentation and Reimbursement Rollbacks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Over-the-counter medicines accounted for 67.02% of the homeopathic product market share in 2025. The segment thrives on mass distribution through Walgreens, Walmart and Boots, reinforced by Hyland's 2025 rollout into 7,400 new U.S. outlets. OTC expansion aligns with digital education campaigns that deepen shopper confidence and raise basket sizes.
Self-care combination remedies underpin forecast acceleration, advancing at 6.85% CAGR as time-pressed consumers embrace multi-symptom relief. Boiron devoted USD 6.6 million to pediatric cold-and-flu advertising, lifting U.S. channel sales 11.4% year on year. Prescription lines persist in Germany and India where practitioner ecosystems remain influential, but their contribution to the homeopathy product market size shrinks as reimbursement wanes.
Plant-based inputs accounted for 60.34% of the value in 2025, thanks to familiarity with Arnica, Belladonna, and Chamomilla. Sustainability narratives and clean-label cues reinforce share across Europe and North America. Mineral remedies maintain a stable demand through practitioner prescriptions.
Animal-based nosodes and sarcodes, though a minority today, are projected to grow at a 9.33% CAGR. Brands like Dr. Reckeweg educate clinicians on chronic-disease protocols, widening acceptance. Ethical sourcing and EU traceability rules introduce cost and reputational hurdles that could moderate growth but have not yet derailed momentum.
Complete Report Scope:
- By Product Type
- OTC Homeopathic Medicines
- Prescription Homeopathic Medicines
- Self-care Combination Remedies
- By Source
- Plant-based
- Mineral-based
- Animal-based
- Biochemic
- By Form
- Liquid Dilutions
- Tablets & Pellets
- Drops & Tinctures
- Ointments & Creams
- Powders
- By Distribution Channel
- Retail Pharmacies
- Homeopathic Clinics
- Other Distribution Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led 2025 revenue at 37.78%, anchored by mature OTC channels and digital subscriptions. United States retailers stock broad assortments, while Canada balances opportunity with a 2025 disclaimer that could mute growth. Mexico remains nascent but benefits from rising wellness spend.
Europe shows mixed prospects. Germany's population familiarity of 95.1% sustains baseline demand despite the coverage debate, and France's reimbursement cut forces a retail pivot for Boiron. Spain, Italy, and Eastern Europe offer mid-single-digit growth under lighter regulation. Weleda's Cell Longevity debut in prestige boutiques illustrates premium repositioning.
Asia-Pacific is set to climb at 7.03% CAGR, the highest regional rate. India dominates with 300,000 practitioners and INR 3,050 crore federal backing. China sees cautious interest beyond TCM, while Australia's strict TGA oversight supports premium pricing. Southeast Asian markets open white-space through smartphone-driven telehealth adoption.
- A. Nelson & Co. Ltd
- Adonis Laboratories Pvt. Ltd
- Ainsworths Ltd
- Allen Homeopathy
- Archibel SA (RadarOpus)
- Bhandari Homoeopathic Laboratories
- Biologische Heilmittel Heel
- Boericke & Tafel
- Boiron
- Dr. Willmar Schwabe GmbH
- Hahnemann Laboratories Inc.
- Homeocan Inc.
- Hyland's (Standard Homeopathic)
- Mediral International
- Pekana Naturheilmittel
- Sanat Products Ltd.
- SBL World Pharmaceuticals
- Similia Research Laboratories
- Weleda
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Prevalence of Chronic Diseases & Dissatisfaction with Allopathy
- 4.2.2 Growing Adoption of Integrative Healthcare Models
- 4.2.3 Regulatory Recognition in Emerging Markets
- 4.2.4 Expansion of E-Commerce & Tele-Consult Platforms
- 4.2.5 Evidence-Based Nano-Dilution Analytics
- 4.2.6 Venture Funding in Personalised Micro-Dose Remedies
- 4.3 Market Restraints
- 4.3.1 Scientific Scepticism & Limited RCT Evidence
- 4.3.2 Reimbursement Cuts / Regulatory Bans in Key Nations
- 4.3.3 Organic Raw-Material Supply Bottlenecks
- 4.3.4 Adulteration & Cross-Contamination Recall Risk
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Product Type
- 5.1.1 OTC Homeopathic Medicines
- 5.1.2 Prescription Homeopathic Medicines
- 5.1.3 Self-care Combination Remedies
- 5.2 By Source
- 5.2.1 Plant-based
- 5.2.2 Mineral-based
- 5.2.3 Animal-based
- 5.2.4 Biochemic
- 5.3 By Form
- 5.3.1 Liquid Dilutions
- 5.3.2 Tablets & Pellets
- 5.3.3 Drops & Tinctures
- 5.3.4 Ointments & Creams
- 5.3.5 Powders
- 5.4 By Distribution Channel
- 5.4.1 Retail Pharmacies
- 5.4.2 Homeopathic Clinics
- 5.4.3 Other Distribution Channels
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 A. Nelson & Co. Ltd
- 6.3.2 Adonis Laboratories Pvt. Ltd
- 6.3.3 Ainsworths Ltd
- 6.3.4 Allen Homeopathy
- 6.3.5 Archibel SA (RadarOpus)
- 6.3.6 Bhandari Homoeopathic Laboratories
- 6.3.7 Biologische Heilmittel Heel GmbH
- 6.3.8 Boericke & Tafel
- 6.3.9 Boiron
- 6.3.10 Dr. Willmar Schwabe GmbH
- 6.3.11 Hahnemann Laboratories Inc.
- 6.3.12 Homeocan Inc.
- 6.3.13 Hyland's (Standard Homeopathic)
- 6.3.14 Mediral International
- 6.3.15 Pekana Naturheilmittel
- 6.3.16 Sanat Products Ltd.
- 6.3.17 SBL World Pharmaceuticals
- 6.3.18 Similia Research Laboratories
- 6.3.19 Weleda AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


