|
시장보고서
상품코드
2123685
고성능 액체 크로마토그래피(HPLC) 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)High-Performance Liquid Chromatography (HPLC) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
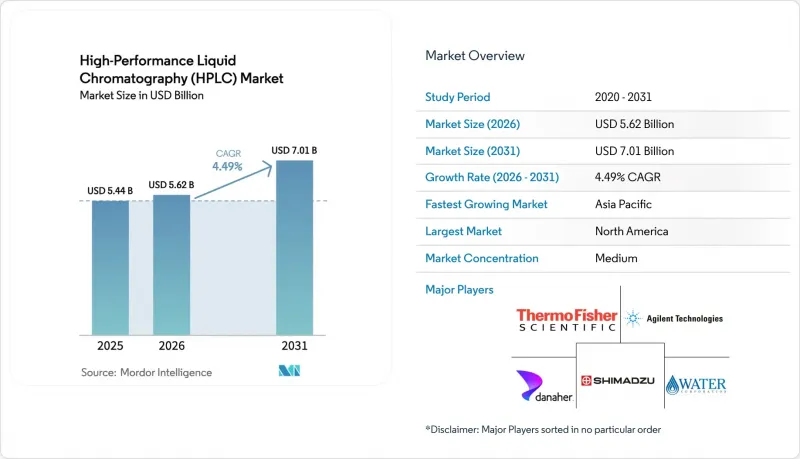
에 의하면, 고성능 액체 크로마토그래피(HPLC) 시장 규모는 2025년 54억 4,000만 달러에서 2026년에는 56억 2,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 4.49%로 성장을 지속하여, 2031년에는 70억 1,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품 유형(장비, 소모품, 부속품), 용도(제약·생명공학 연구 등), 분리 모드(역상 등), 검출 방법(UV/Vis 등), 최종 사용자(제약·생명공학 기업 등) 및 지역(북미 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 고성능 액체 크로마토그래피(HPLC) 시장 동향 및 인사이트
바이오의약품 및 단일클론 항체에 대한 수요 증가
2024년에는 18종의 단일 클론 항체가 FDA 승인을 받았으며, 현재는 99%의 순도 기준을 확보하기 위해 친화성, 이온 교환, 크기 배제 모드를 결합한 멀티 컬럼 정제 시스템에 의존하는 파이프라인이 유지되고 있습니다. 따라서 사내에 방법 개발 인력을 보유하지 않은 수탁 제조업체들은 검증 및 라이프사이클 지원을 포함하는 벤더의 서비스 계약이 포함된 완전한 HPLC 워크스테이션을 도입하고 있습니다. 인도 및 중국의 바이오시밀러 제조업체들은 18개월의 생물학적 동등성 심사 기간에 직면해 있으며, 기존 프로토콜보다 검증된 UHPLC 방법이 우대받기 때문에 고처리량 분석 장비의 구매 주기가 단축되고 있습니다. EMA의 2025년 ICH Q6B 개정안에서는 직교적인 당화 확인이 의무화됨에 따라, UV와 형광 또는 질량 분석법을 결합한 듀얼 검출기 구성에 대한 수요가 증가하고 있습니다. 세포 및 유전자 치료용 벡터의 경우, 잔류 플라스미드 DNA를 10억 분의 1 수준으로 정량해야 하므로, 이에 따라 18,000 psi의 작동 압력을 견딜 수 있는 2µm 미만의 입자층을 위한 컬럼 기술 혁신이 촉진되고 있습니다. 이러한 요인들이 복합적으로 작용하여, 바이오프로세스 분석 분야의 고성능 액체 크로마토그래피(HPLC) 시장 규모가 확대되고 있습니다.
식품 안전 및 환경 검사 분야에서의 도입 확대
미국 식품의약국(FDA)의 ‘예방적 관리에 관한 최종 규정’에 따라 수입 곡물에 대한 미코톡신 검사가 의무화됨에 따라, 2024년에는 국경 검역소에서 분석 기기 도입 대수가 약 2,500대에 달할 전망입니다. 중국은 2025년에 47건의 새로운 식품 안전 기준을 발표했으며, 그 대부분에서 농약의 기준 분석법으로 HPLC가 지정됨에 따라 각 성의 예산은 가스 크로마토그래피(GC)의 대체 기술이 아닌 컬럼 및 용매 팩으로 전환되고 있습니다. 유럽연합(EU)은 발색기를 갖지 않은 PFAS 화합물을 모니터링하기 위해 2024년 ‘식수 지침’ 개정안에 HPLC-MS를 포함시켰습니다. 브라질에서는 현재 커피 수출 시 HPLC를 이용한 아플라톡신 검증이 의무화되어 있으며, 신흥국들이 EU의 기준치를 충족하기 위해 설비를 개조하고 있는 실태를 엿볼 수 있습니다. 이것이 고성능 액체 크로마토그래피 시장의 지역적 수요를 더욱 부추기고 있습니다. 또한, 올리브 오일이나 꿀의 진위성 검사에서도 프리미엄 라벨 표기를 위한 원산지를 검증하기 위해 크로마토그래피를 이용한 지문 분석이 적용되면서, 컬럼의 처리 능력이 더욱 확대되고 있습니다.
장비 및 유지보수 비용의 고가
4만 달러의 엔트리 레벨 시스템도 질량 분석기와의 호환성이나 CFR Part 11 준수 소프트웨어를 포함하면 25만 달러 이상으로 치솟아, 신흥 경제국의 소규모 연구소에게는 큰 장벽이 되고 있습니다. 연간 유지보수 계약에는 구매 가격의 8-12%가 추가 비용으로 발생하지만, OEM에 의한 유지보수를 생략하면 보증이 무효화되거나 규제 준수가 위태로워지는 경우가 많습니다. 고속 처리 시설의 경우, 개당 500-1,500달러인 컬럼을 연간 30개나 소비하는 경우가 있어, 10년 동안 총 소유 비용이 50만 달러를 초과하게 됩니다. 이러한 장벽은 교체 주기를 장기화시켜 고성능 액체 크로마토그래피(HPLC) 시장의 성장을 둔화시키고 있습니다. 리스 투 오너(Lease-to-Owner) 방식은 부담을 줄여주지만, 8%에 가까운 이자 부담이 발생하며, 계약 조항에 따라 구매자가 공급업체가 지정한 소모품만을 사용해야 하는 경우도 빈번하게 나타납니다.
부문 분석
소모품 시장은 2031년까지 연평균 8.26%의 성장률을 보일 것으로 예측되며, 이는 고성능 액체 크로마토그래피 시장 전체 성장률의 거의 2배에 해당합니다. 200-500회 주입마다 컬럼을 교체해야 하고, 주당 평균 10-20 L의 아세토니트릴을 소비하며, 여기에 전용 버퍼 팩 등이 더해져 소모품에 대한 안정적인 수요를 뒷받침하고 있습니다. 2025년에 48.25%의 점유율을 차지한 장비 부문은 정기적인 유지보수를 실시하면 견고한 UHPLC 섀시를 10년 이상 사용할 수 있기 때문에 성장 속도가 비교적 완만합니다.
컬럼의 기술 혁신으로 수명이 최대 50% 연장되었지만, UHPLC의 높은 압력이 마모를 가속화하기 때문에 지속적인 수요가 보장되고 있습니다. 오토샘플러, 탈기 장치, 컬럼 오븐 등의 액세서리는 데이터 무결성 준수를 위해 연구소가 레거시 시스템을 개조할 때 점진적인 업그레이드를 가져옵니다. '면도기와 면도날' 비즈니스 모델을 활용하는 공급업체는 특히 검증된 분석법에 독자적인 컬럼 화학이 통합된 경우, 고성능 액체 크로마토그래피 시장에서 확고한 입지를 구축하고 있습니다.
식품 및 음료 검사 시장은 수입 규제, 오염 스캔들, 진위성 검증을 배경으로 2031년까지 연평균 성장률(CAGR) 7.23%로 확대되고 있습니다. 의약품 및 생명공학 연구는 2025년 기준 37.47%를 차지하며 여전히 가장 큰 점유율을 자랑하지만, 제네릭 의약품과의 경쟁으로 인해 연구 개발(R&D) 예산이 압박받고, 바이오의약품이 직교 분석법에 의존하게 됨에 따라 그 점유율은 축소되고 있습니다.
임상 진단 분야는 포인트 오브 케어(PoC) 면역 분석법이 많은 HPLC 검사를 대체하고, 크로마토그래피가 전문적인 검사 패널로 한정됨에 따라 완만한 성장에 그치고 있습니다. 환경 모니터링 분야는 안정적인 추세를 유지하고 있는 반면, 법의학 연구소에서는 압수된 약물프로파일링 및 독물학 분석에 대한 활용이 확대되고 있습니다. 수요의 다양화로 인해 고성능 액체 크로마토그래피(HPLC) 시장은 제약 업계의 설비 투자에 따른 주기적인 변동의 영향을 완화하고 있습니다.
지역별 분석
북미는 각 배치 출시 시마다 HPLC 분석을 3회 실시하도록 규정하는 FDA 주도의 검증 기준 덕분에 2025년 매출의 37.66%를 차지했습니다. 이미 도입된 시스템의 노후화(시스템의 40%가 10년 이상 경과)로 인해, 벤더들이 AI가 탑재된 UHPLC 플랫폼으로의 교체 크레딧을 제공하고 있어 교체 수요가 증가하고 있습니다. 캐나다와 멕시코가 성장을 주도하고 있으며, 특히 멕시코는 물류 시간을 단축하기 위해 제조 공장 근처에 분석 실험실을 설치하는 ‘니어쇼어링’의 혜택을 받고 있습니다.
아시아태평양은 중국, 인도, 한국이 유럽 및 미국의 규제 당국과의 GMP 기준 일관성을 강화함에 따라 2031년까지 연평균 성장률(CAGR) 6.72%로 성장할 전망입니다. 중국의 2024년 ‘약사관리법’ 개정에 따라 전통 의약품이라도 크로마토그래피를 통한 검사가 의무화되는 한편, 인도의 제네릭 의약품 제조업체들은 FDA의 지적 사항에 대응하기 위해 데이터 무결성 향상을 위한 투자를 진행하고 있습니다. 동남아시아의 수출업체들은 EU의 농약 잔류 기준을 충족하기 위해 HPLC를 도입하고 있으며, 태국, 베트남, 인도네시아로 수요가 확대되면서 해당 지역의 고성능 액체 크로마토그래피(HPLC) 시장을 성장시키고 있습니다.
유럽에서는 EMA(유럽의약품청) 및 EFSA(유럽식품안전청)의 지침을 배경으로 꾸준한 도입이 진행되고 있습니다. 서유럽 국가들은 EU 그린딜에 부합하는 용매 절약형 액세서리를 도입하여 장비군을 현대화하고 있으며, 남유럽의 올리브 오일 및 와인 업계에서는 원산지 명칭 라벨을 확보하기 위해 HPLC를 이용한 진위성 검사가 도입되고 있습니다. 동유럽은 EU 역내이면서도 비용 효율적인 생산을 추구하는 제약 투자를 유치하고 있으며, 폴란드와 체코 공화국으로의 장비 도입이 진행되고 있습니다. 중동 및 아프리카 및 남미는 여전히 시장 점유율이 낮은 편이지만, 식품 안전 및 현지 의약품 제조에 대한 공공 투자가 점진적인 성장을 뒷받침하고 있으며, 브라질과 GCC 국가들이 해당 지역 내 도입을 주도하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the high-Performance liquid chromatography market size is expected to grow from USD 5.44 billion in 2025 to USD 5.62 billion in 2026 and is forecast to reach USD 7.01 billion by 2031 at 4.49% CAGR over 2026-2031.
This report is Segmented by Product Type (Instruments, Consumables, Accessories), Application (Pharmaceutical & Biotechnology Research, and More), Separation Mode (Reverse-Phase, and More), Detection Method (UV/Vis, and More), End-User (Pharmaceutical & Biotechnology Companies, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global High-Performance Liquid Chromatography (HPLC) Market Trends and Insights
Rising Demand for Biopharmaceuticals & Monoclonal Antibodies
Eighteen monoclonal antibodies won FDA approval in 2024, sustaining a pipeline that now depends on multi-column purification trains combining affinity, ion-exchange, and size-exclusion modes to assure 99% purity thresholds. Contract manufacturers without in-house method-development talent are therefore acquiring complete HPLC workstations bundled with vendor service contracts covering validation and lifecycle support. Biosimilar producers in India and China face 18-month bioequivalence windows that reward validated UHPLC methods over legacy protocols, compressing buying cycles for high-throughput instruments. EMA's 2025 revision of ICH Q6B now compels orthogonal glycosylation confirmation, driving demand for dual-detector configurations that pair UV with fluorescence or mass spectrometry. Cell- and gene-therapy vectors require quantification of residual plasmid DNA at parts-per-billion levels, catalyzing column innovation toward sub-2 µm particle beds that withstand 18,000 psi operating pressures. Collectively, these factors enlarge the High-Performance Liquid Chromatography market footprint in bioprocess analytics.
Increasing Adoption in Food Safety & Environmental Testing
The U.S. FDA's final preventive-controls rule added mandatory mycotoxin screening for imported grains, triggering around 2,500 instrument placements across border laboratories in 2024. China released 47 new food-safety standards in 2025, most citing HPLC as the reference technique for pesticides, thereby shifting provincial budgets toward columns and solvent packs rather than gas-chromatography alternatives. The European Union incorporated HPLC-MS into its 2024 Drinking Water Directive update to monitor PFAS compounds that lack chromophores. Brazil now obliges aflatoxin verification in coffee exports using HPLC, illustrating how emerging economies retrofit facilities to meet EU thresholds, which in turn fertilizes regional demand in the High-Performance Liquid Chromatography market. Authenticity testing for olive oil and honey further expands column throughput by applying chromatographic fingerprints to verify geographic origin for premium labeling.
High Cost of Instruments & Maintenance
Entry-level systems priced at USD 40,000 escalate to >USD 250,000 when mass-spectrometry compatibility and CFR Part 11 software are included, intimidating small labs in emerging economies. Annual service contracts add another 8-12% of purchase price, yet forgoing OEM maintenance often voids warranties and jeopardizes regulatory compliance. High-throughput sites may burn through 30 columns per year at USD 500-1,500 each, lifting total ownership above USD 500,000 across ten years, a barrier that stretches replacement cycles and dampens High-Performance Liquid Chromatography market growth. Lease-to-own models offer relief but impose interest costs near 8%, and clauses frequently restrict buyers to vendor consumables.
Other drivers and restraints analyzed in the detailed report include:
- Growing Prominence of UHPLC for High-Throughput Screening
- Advances in Microfluidic / Chip-Based HPLC Platforms
- Shortage of Skilled Chromatographers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Consumables are projected to grow at 8.26% through 2031, nearly twice the overall High-Performance Liquid Chromatography market. Column turnover every 200-500 injections, solvent consumption that averages 10-20 L of acetonitrile weekly, and proprietary buffer packs together reinforce a steady consumable pull. The instruments segment, which captured 48.25% in 2025, expands more slowly because robust UHPLC chassis remain serviceable for >10 years with regular maintenance.
Column innovations extend lifetime by up to 50%, yet higher UHPLC pressures hasten wear, ensuring recurring demand. Accessories-autosamplers, degassers, column ovens-add incremental upgrades as labs retrofit legacy systems for data-integrity compliance. Vendors leveraging razor-and-blade economics secure durable footholds in the High-Performance Liquid Chromatography market, especially when validated methods embed exclusive column chemistries.
Food and beverage testing advances at 7.23% CAGR to 2031, driven by import regulations, contamination scandals, and authenticity verification. Pharmaceutical and biotechnology research still represents the single largest slice at 37.47% in 2025, but its share erodes as generic competition compresses R&D budgets and biologics rely on orthogonal analytics.
Clinical diagnostics grows slowly because point-of-care immunoassays replace many HPLC tests, relegating chromatography to specialist panels. Environmental monitoring remains stable, while forensic labs expand usage for seized-drug profiling and toxicology. Demand diversification cushions the High-Performance Liquid Chromatography market against cyclical swings in pharmaceutical capital expenditure.
Complete Report Scope:
- By Product Type
- Instruments
- Consumables
- Accessories
- By Application
- Pharmaceutical & Biotechnology Research
- Clinical Diagnostics
- Food & Beverage Testing
- Environmental Analysis
- Forensic Science
- Other Industrial Applications
- By Separation Mode
- Reverse-Phase HPLC
- Ion-Exchange HPLC
- Size-Exclusion HPLC
- Affinity HPLC
- Hydrophobic-Interaction HPLC
- Other Modes
- By Detection Method
- UV/Vis Detectors
- Fluorescence Detectors
- Refractive-Index Detectors
- Mass-Spectrometry Detectors
- Electrochemical Detectors
- Others
- By End-User
- Pharmaceutical & Biotechnology Companies
- Academic & Research Institutes
- Contract Research Organizations
- Hospitals & Clinics
- Environmental Agencies
- Food & Beverage Companies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America commanded 37.66% of 2025 revenue courtesy of FDA-driven validation norms that stipulate triplicate HPLC runs for each batch release. An aging installed base-40% of systems exceed 10 years-creates a ripe replacement pool as vendors offer trade-in credits toward AI-enabled UHPLC platforms. Canada and Mexico contribute incremental growth, the latter benefitting from near-shoring that places analytical labs near manufacturing plants to shorten logistics.
Asia-Pacific advances at 6.72% CAGR through 2031 as China, India, and South Korea tighten GMP parity with Western agencies. China's 2024 Drug Administration Law amendment forces chromatographic testing even for traditional medicines, while Indian generic producers invest in data-integrity upgrades to satisfy FDA observations. Southeast Asian exporters adopt HPLC to meet EU pesticide residue limits, diffusing demand across Thailand, Vietnam, and Indonesia and enlarging the regional High-Performance Liquid Chromatography market.
Europe exhibits steady uptake anchored by EMA and EFSA directives. Western European nations modernize fleets with solvent-savings accessories aligned to the EU Green Deal, and Southern Europe's olive-oil and wine sectors deploy HPLC authenticity assays to secure denomination-of-origin labels. Eastern Europe attracts pharmaceutical investments seeking EU-based yet cost-effective production, channeling instrument placements into Poland and the Czech Republic. Middle East & Africa and South America maintain modest shares, yet public investment in food-safety and local drug manufacturing underpins incremental growth, with Brazil and GCC states leading regional adoption.
- Agilent Technologies
- Bio-Rad Laboratories
- Danaher
- Gilson
- Hamilton Company
- Hitachi
- Jasco Inc.
- Knauer Wissenschaftliche Gerate
- LECO
- Merck KGaA (MilliporeSigma)
- Restek
- Revvity Inc
- Shimadzu
- Thermo Fisher Scientific
- Tosoh
- Trajan Scientific
- Waters Corporation
- YMC Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Biopharmaceuticals & Monoclonal Antibodies
- 4.2.2 Increasing Adoption in Food Safety & Environmental Testing
- 4.2.3 Growing Prominence of UHPLC For High-Throughput Screening
- 4.2.4 Advances in Microfluidic / Chip-Based HPLC Platforms
- 4.2.5 Integration of AI-Driven Predictive Maintenance
- 4.2.6 Stringent Regulatory Guidelines for Pharma QA
- 4.3 Market Restraints
- 4.3.1 High Cost of Instruments & Maintenance
- 4.3.2 Shortage of Skilled Chromatographers
- 4.3.3 Regulatory Push Toward Greener Analytical Techniques
- 4.3.4 Competition From Alternative Separation Technologies
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product Type
- 5.1.1 Instruments
- 5.1.2 Consumables
- 5.1.3 Accessories
- 5.2 By Application
- 5.2.1 Pharmaceutical & Biotechnology Research
- 5.2.2 Clinical Diagnostics
- 5.2.3 Food & Beverage Testing
- 5.2.4 Environmental Analysis
- 5.2.5 Forensic Science
- 5.2.6 Other Industrial Applications
- 5.3 By Separation Mode
- 5.3.1 Reverse-Phase HPLC
- 5.3.2 Ion-Exchange HPLC
- 5.3.3 Size-Exclusion HPLC
- 5.3.4 Affinity HPLC
- 5.3.5 Hydrophobic-Interaction HPLC
- 5.3.6 Other Modes
- 5.4 By Detection Method
- 5.4.1 UV/Vis Detectors
- 5.4.2 Fluorescence Detectors
- 5.4.3 Refractive-Index Detectors
- 5.4.4 Mass-Spectrometry Detectors
- 5.4.5 Electrochemical Detectors
- 5.4.6 Others
- 5.5 By End-User
- 5.5.1 Pharmaceutical & Biotechnology Companies
- 5.5.2 Academic & Research Institutes
- 5.5.3 Contract Research Organizations
- 5.5.4 Hospitals & Clinics
- 5.5.5 Environmental Agencies
- 5.5.6 Food & Beverage Companies
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 France
- 5.6.2.3 United Kingdom
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Agilent Technologies
- 6.3.2 Bio-Rad Laboratories
- 6.3.3 Danaher
- 6.3.4 Gilson Inc.
- 6.3.5 Hamilton Company
- 6.3.6 Hitachi High-Tech Corporation
- 6.3.7 Jasco Inc.
- 6.3.8 Knauer Wissenschaftliche Gerate
- 6.3.9 LECO Corporation
- 6.3.10 Merck KGaA (MilliporeSigma)
- 6.3.11 Restek Corporation
- 6.3.12 Revvity Inc
- 6.3.13 Shimadzu Corporation
- 6.3.14 Thermo Fisher Scientific
- 6.3.15 Tosoh Bioscience
- 6.3.16 Trajan Scientific
- 6.3.17 Waters Corporation
- 6.3.18 YMC Co., Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment