|
시장보고서
상품코드
2123724
피하 면역글로불린 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Subcutaneous Immunoglobulin - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
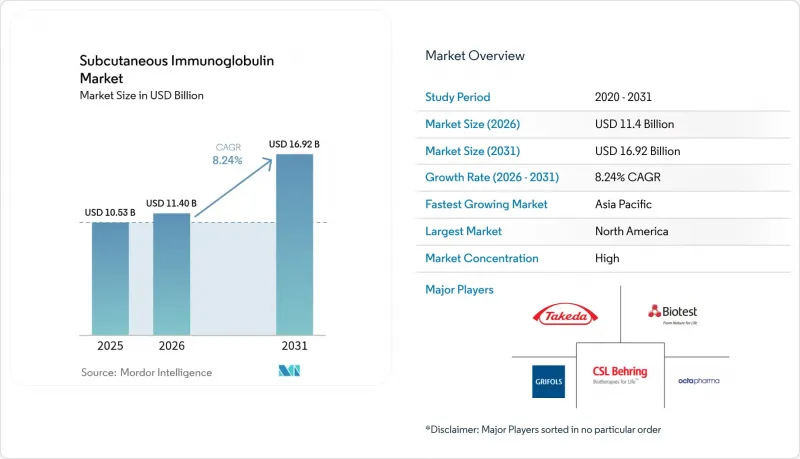
에 의하면, 피하 면역글로불린 시장 규모는 2025년에 105억 3,000만 달러로 평가되었고 2026년 114억 달러에서 2031년까지 169억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 8.24%를 나타낼 전망입니다.
본 보고서는 용도(원발성 면역결핍증, 이차성 면역결핍증 등), 투여 방법(기존 펌프, 급속 주입 등), 최종 사용자(병원, 재택 간호 시설 등), 지역(북미, 유럽 등), 유통 채널(병원 약국 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 피하 면역글로불린 시장 동향 및 인사이트
원발성 면역결핍증 유병률 증가가 시장 확대를 주도
대규모 전자 차트 시스템에 통합된 선별 알고리즘의 개선으로, 현재 1만 명 중 6명의 선천성 면역 이상 환자가 확인되고 있으며, 이는 기존의 예상을 크게 상회하는 수치입니다. 역학적 데이터의 정확도가 향상됨에 따라 의사들은 더 조기에 보충 요법을 처방하게 되었고, 그 결과 환자들이 피하 투여 제제를 투여받는 기간이 길어지고 있습니다. 병원 데이터에 따르면, 중증 감염증으로 인한 입원 평균 비용은 12만 2,739달러이며, 이 수준은 보험사가 예방적 면역글로불린 요법 비용을 부담하는 결정적인 요인이 되고 있습니다. 다운증후군 및 기타 증후군에 수반되는 면역 결핍이 잇달아 발견됨에 따라 치료 대상이 되는 환자층이 확대되고 있습니다. 또한, COVID-19 경험을 통해 팬데믹에서 엔데믹으로 전환되는 시기에 있는 취약 계층에 대한 예방적 IgG 사용의 타당성이 더욱 입증되었습니다. 이러한 요인들이 복합적으로 작용하여 기초 수요가 증가함에 따라, 피하 면역글로불린 시장의 연간 판매량 증가세가 안정적으로 유지되고 있습니다.
환자들의 선호도가 IVIG에서 SCIG로의 전환을 가속화
조사 데이터에 따르면, 환자의 82%가 피하 투여를, 84%가 재택 투여를 선호하며, 그 이유로 자율성 확보와 통원 부담 경감이 꼽히고 있습니다. 실제 임상 연구에서는 특히 만성 신경근 질환에서 전신 반응이 적으면서도 동등한 유효성이 확인되었습니다. 의료 경제 분석에 따르면, 간호사가 환자 1인당 소요하는 시간은 피하 투여의 경우 연간 35시간인 반면, 정맥 내 투여의 경우 이보다 훨씬 더 많은 노력이 필요합니다. 사전 충전 주사기, 수동 주입 옵션, 소형 휴대용 펌프를 통해 과거 치료를 점적실로만 제한하던 기술적 장벽이 제거되었습니다. 이러한 편의성의 조합으로 인해 신규 환자들이 끊임없이 피하 면역글로불린 시장으로 유입되고 있습니다.
전 세계 혈장 공급 문제가 시장의 지속적인 성장을 저해하고 있습니다.
혈장 1리터당 환자에게 투여되기까지 7-12개월의 분획 처리가 필요하기 때문에 수요가 조금만 증가해도 재고에 부담이 가중됩니다. 각국 정부는 이에 대응하고 있으며, 영국은 2025년까지 혈장 자급률을 0%에서 25%로 높이고, 2031년까지 30-35%를 목표로 하고 있습니다. 각 제조업체들은 제조 공정의 개선을 추진하고 있으며, ADMA Biologics는 최적화된 크로마토그래피 및 바이러스 여과 공정을 통해 수율을 20% 향상시키는 기술을 신청했습니다. 그러나 주요 기증국의 채혈 정책 변경이 여전히 성장의 걸림돌이 되고 있으며, 분획 처리 능력이 제한적인 개발도상국에서는 지역적인 공급 부족이 가장 먼저 표면화되고 있습니다. 따라서 피하 면역글로불린 시장은 1리터의 혈장에서 얻을 수 있는 양을 극대화하기 위한 지속적인 혁신에 의존하고 있습니다.
부문 분석
2025년에는 원발성 면역결핍증이 매출의 58.10%를 차지하며 연평균 성장률(CAGR) 8.86%로 성장하고 있어, 피하 면역글로불린 시장에서 가장 큰 점유율을 차지하고 있습니다. 의사의 인식 제고, 신생아 선별 검사의 시범 도입, 그리고 유전체 검사가 결합되어 환자의 조기 발견이 가능해졌으며, 이는 치료 기간의 연장으로 이어지고 있습니다. 화학요법, 줄기세포 이식, 항류마티스 약물과 관련된 이차성 면역결핍증은 기존에는 병원에서 IVIG 주사에 의존하던 환자층을 대폭 확대시키고 있습니다. 만성 염증성 탈수초성 다발성 신경염(CIDP) 및 다발성 운동 신경 장애에 대해 유지 투여에 관한 지침의 지지를 얻음에 따라, 신경학적 적응증 분야가 가장 빠르게 확대되고 있습니다. 성인 CIDP에 대한 ‘GAMMAGARD LIQUID’의 규제 당국 승인으로, 2025년에는 보험사들의 인지도가 높아졌습니다. 자가면역성 뇌염 및 스티프 퍼슨 증후군에 대한 새로운 연구 결과, 잠재적 환자층이 더욱 확대되고 있습니다. 정밀 의학(Precision Medicine) 이니셔티브에서는 혈청 바이오마커 패널과 머신러닝 알고리즘을 활용하여 환자를 피하 투여군과 정맥 내 투여군으로 분류하고 있습니다. 이러한 데이터에 기반한 매칭을 통해 자원 배분이 최적화되고, 복약 순응도가 향상되며, 피하 면역글로불린 시장의 성장이 환자 중심적으로 이루어질 수 있도록 보장됩니다.
부문의 다양성이 회복력을 보장합니다. 혈장 부족으로 인해 투여량 배분이 제한될 경우, 제조업체는 면역 결핍의 주요 환자층을 소외시키지 않으면서도 고부가가치의 신경학 분야 부문으로 공급을 재분배할 수 있습니다. 병원, 진료소 및 재택 간호 서비스는 더 광범위한 적응증 조합을 반영하도록 교육 컨텐츠를 조정하여 오투여 위험을 줄이고 있습니다. 치료 대상자가 확대됨에 따라, 리얼 월드 에비던스 네트워크는 안전성, 유효성 및 삶의 질(QOL)에 관한 결과를 수집하여 보험사용 자료에 반영하고 있습니다. 이러한 피드백 루프는 계약 협상을 강화하고 보험 등재를 확보합니다. 전반적으로 적응증 범위의 확대로 인해 피하 면역글로불린 업계는 일회용 제품 라인이 아닌 다목적 치료 플랫폼으로 변모하고 있습니다.
기존 펌프를 이용한 점적 투여는 확립된 임상 프로토콜과 기기의 광범위한 접근성을 바탕으로 2025년에도 매출 점유율 48.05%를 유지했습니다. 이 방법은 프로그래밍 가능한 유량으로 주사 부위의 불편함을 최소화할 수 있기 때문에 소아나 손의 민첩성에 제한이 있는 환자들에게 여전히 선호되고 있습니다. 하지만 히알루로니다제를 통한월1회 투여가 가능해짐에 따라, 투여 지원 요법은 연평균 성장률(CAGR) 8.76%라는 빠른 속도로 급속히 확대되고 있습니다. 주간 일정을 맞추는 데 어려움을 겪던 환자들은월1회 투여 요법으로 전환하고 있으며, 이를 통해 시간적 여유가 생기고 말초 카테터 관련 소모품도 줄어들고 있습니다. 주사기를 이용한 수동 기술인 ‘래피드 푸시(Rapid Push)’는 완벽한 제어와 최소한의 장비를 선호하는 성인 환자들에게 지지를 받고 있습니다. 비교 연구에서는 이러한 기술들 간에 약동학적 비열등성이 보고되어, 의사는 환자의 라이프스타일에 맞추어 선택지를 조정할 수 있게 되었습니다.
의료기기 제조업체들도 동시에 혁신을 추진하고 있습니다. 임상 평가 중인 웨어러블형 체외 주입 장치는 대용량과 눈에 띄지 않는 디자인을 동시에 실현하는 것을 목표로 하고 있습니다. 스마트폰 앱은 주입 데이터를 기록하고, 복약 순응도를 돕는 알림을 전송합니다. 증강현실(AR)을 활용한 교육 모듈은 초기 학습 곡선을 완화하고, 치료 시작 시 병원 체류 시간을 단축합니다. 지역별 진료 패턴은 다릅니다. 북미에서는 모든 투여 방법이 도입되어 있는 반면, 유럽에서는 성인을 대상으로 한 보조 요법이 점점 더 선호되는 추세이며, 아시아태평양에서는 HYQVIA의 승인을 받아 대용량·저압 점적 주입이 가능한 차세대 펌프가 도입되고 있습니다. 전반적으로 투여 방법의 다양성이 피하 면역글로불린 시장의 지속적인 성장을 뒷받침하고 있습니다.
지역별 분석
북미는 매출의 40.85%를 차지합니다. 이는 미국에서 약 15만-20만 명의 원발성 면역결핍증 환자가 진단되었으며, 민간 보험 플랜과 메디케어 모두에서 재택 주입에 대한 광범위한 급여가 유지되고 있기 때문입니다. 캐나다에서는 주 정부 처방약 목록을 통해 치료비가 환급되며, 병원이나 지역 프로그램을 통해 제품이 제공되고 있습니다. 한편, 멕시코에서는 공공 부문의 입찰이 확대되고 있으며, 피하 투여 옵션도 대상에 포함되고 있습니다. 가정 내 정맥 주사 투여에 대한 간호 시간 보상을 허용하는 최근 메디케어 규정 변경으로 인해 이 치료법의 보급이 더욱 촉진되고 있습니다. 주로 미국에 구축된 견고한 혈장 채취 인프라는 국내 안정적 공급을 보장하며, 국제적인 공급 충격에 대한 완충재 역할을 수행하고 있습니다.
유럽은 자급자족형 생산 거점으로서의 위상을 확립해 가고 있습니다. 영국은 2025년에 국내 혈장 자급률 25%를 달성하고, 2031년까지 30-35%를 목표로 하고 있습니다. 독일은 최대의 분획 처리 능력을 보유하고 있으며, 프랑스, 이탈리아,스페인은 국내 혈장 수집 활동을 우선적으로 추진하고 있습니다. 유럽의약품청(EMA)은 투여가 용이한 제제에 대한 심사 신속화를 지원하고 있으며, HYQVIA의 신속 승인 및 XEMBIFY의 EU 전역에서의 적응증 확대가 그 증거입니다. COVID-19로 인한 공급 차질을 계기로 전략적인 혈장 비축에 대한 투자가 진행되면서, 공중보건 정책과 산업 정책이 연계되기 시작했습니다.
아시아태평양은 연평균 성장률(CAGR) 8.98%로 가장 빠르게 성장하고 있는 지역이며, 그 배경에는 일본의 2024년 HYQVIA 승인 및 중국 도시 지역의 보험 적용 범위 확대가 있습니다. 호주 국립혈액청은 2개월마다 가정용 투여 제품을 공급하며, 피하 투여 제제를 표준 치료법으로 정착시키고 있습니다. 한국은 바이오의약품 생태계를 활용하여 국내 혈장 분획 프로젝트를 추진하고 있는 반면, 인도네시아는 자국 최초의 혈장 시설 건설을 위한 외국인 투자를 유치했습니다. 신흥 시장의 규제 체계 분절화와 기증자 네트워크의 제한성이 과제로 지적되지만, 다자간 보건 안보 프로그램을 통해 기술 지원이 이루어지고 있습니다. 인증된 혈장 분획 공장의 기반이 확대되고 있는 것은 피하 면역글로불린 시장의 장기적인 성장을 위한 견고한 토대를 마련하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the subcutaneous immunoglobulin market size was valued at USD 10.53 billion in 2025 and estimated to grow from USD 11.4 billion in 2026 to reach USD 16.92 billion by 2031, at a CAGR of 8.24% during the forecast period (2026-2031).
This report is Segmented by Application (Primary Immunodeficiency Diseases, Secondary Immunodeficiency, and More), Administration Technique (Conventional Pump, Rapid Push, and More), End User (Hospitals, Home Care Settings, and More), and Geography (North America, Europe, and More). Distribution Channel (Hospital Pharmacies, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Subcutaneous Immunoglobulin Market Trends and Insights
Growing Prevalence of Primary Immunodeficiency Disorders Drives Market Expansion
Improved screening algorithms embedded in large electronic-health-record systems now identify 6 in 10,000 individuals with inborn errors of immunity, well above earlier assumptions. More accurate epidemiology means physicians prescribe replacement therapy earlier, which lengthens a patient's lifetime exposure to subcutaneous products. Hospital data place the average cost of admission for severe infections at USD 122,739, a level that persuades insurers to fund preventive immunoglobulin therapy. Parallel discoveries of immune deficits in Down syndrome and other syndromic conditions widen the treated population. COVID-19 experience further supports prophylactic IgG use for vulnerable groups as they transition from pandemic to endemic risk. Together these factors elevate baseline demand and stabilize year-on-year volume growth for the subcutaneous immunoglobulin market.
Patient Preference Accelerates IVIG-to-SCIG Migration
Survey data show that 82% of patients prefer subcutaneous delivery and 84% favor home administration, citing autonomy and reduced travel burden. Real-world studies confirm equal efficacy alongside fewer systemic reactions, particularly in chronic neuromuscular conditions. Health-economic analyses reveal that nurses spend 35 hours per patient annually on subcutaneous support versus significantly higher labor for intravenous regimens. Pre-filled syringes, manual push options, and small portable pumps remove the technical hurdles that once confined therapy to infusion suites. These combined conveniences channel a steady stream of new starters directly into the subcutaneous immunoglobulin market.
Global Plasma Supply Constraints Challenge Market Growth Sustainability
Every liter of plasma requires 7-12 months of fractionation before a dose reaches the patient, so even modest demand increments strain inventories. Governments act: the United Kingdom moved from 0% to 25% plasma self-sufficiency by 2025 and targets 30-35% by 2031. Manufacturers upgrade processes, and ADMA Biologics filed for a 20% yield enhancement that uses optimized chromatography and virus-filtration steps. Yet collection policy changes in major donor countries still cap growth, and regional shortfalls appear first in developing economies with limited fractionation capacity. The subcutaneous immunoglobulin market therefore relies on continuous innovation to stretch each liter of plasma further.
Other drivers and restraints analyzed in the detailed report include:
- Aging Demographics and Chronic Disease Burden Expand Treatment Population
- Hyaluronidase-Facilitated Therapy Transforms Administration Paradigms
- FcRn-Inhibitor Biologics Emerge as Competitive Threat
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Primary immunodeficiency held 58.10% revenue in 2025 and is advancing at an 8.86% CAGR, underpinning the largest slice of the subcutaneous immunoglobulin market. Greater physician awareness, newborn screening pilots, and genomic testing converge to catch patients earlier, which extends therapy lifespan. Secondary immunodeficiency linked to chemotherapy, stem-cell transplant, and antirheumatic medications adds a sizeable cohort that previously relied on hospital IVIG infusions. Neurological applications are rising fastest because chronic inflammatory demyelinating polyneuropathy and multifocal motor neuropathy have secured guideline support for maintenance dosing. Regulatory clearance of GAMMAGARD LIQUID for CIDP in adults widened payer recognition in 2025. Emerging research on autoimmune encephalitis and stiff-person syndrome further enlarges the potential pool. Precision-medicine initiatives use serum biomarker panels and machine-learning algorithms to stratify patients for subcutaneous versus intravenous routes. This data-guided matching optimizes resource allocation and improves adherence, ensuring that subcutaneous immunoglobulin market growth remains patient-centric.
Segment diversity secures resilience. When plasma scarcity limits volume allocation, manufacturers can redistribute supply toward high-value neurology segments without abandoning core immunodeficiency users. Hospitals, clinics, and home-care services align educational content to reflect the broader indication mix, reducing mis-administration risks. As the treated base widens, real-world evidence networks collect safety, efficacy, and quality-of-life outcomes that feed back into payer dossiers. The feedback loop strengthens contract negotiations and secures formulary placement. Overall, application breadth transforms the subcutaneous immunoglobulin industry into a versatile treatment platform rather than a single-use product line.
Conventional pump infusion retained 48.05% revenue share in 2025 on the strength of entrenched clinical protocols and broad device availability. The method remains favored for children and patients with limited manual dexterity because programmable flow rates minimize infusion-site discomfort. That said, facilitated therapy is scaling quickly at an 8.76% CAGR on the back of hyaluronidase-enabled monthly dosing. Patients who struggled with weekly schedules migrate to one-day-per-month regimens, freeing time and cutting peripheral-catheter consumables. Rapid push, a syringe-driven manual technique, appeals to adults who prefer complete control and minimalist equipment. Comparative studies report non-inferior pharmacokinetics across these techniques, empowering physicians to tailor choices to patient lifestyle.
Device firms innovate in parallel. Wearable on-body injectors under clinical evaluation aim to combine large-volume capacity with discreet form factors. Smart-phone apps log infusion data and push reminders that support adherence. Training modules delivered through augmented reality reduce the initial learning curve and shorten hospital chair time at initiation. Regional practice patterns differ: North America deploys the full menu of techniques, Europe increasingly favors facilitated therapy for adults, and Asia-Pacific installs new-generation pumps capable of high-volume, low-pressure infusions following HYQVIA approval. Collectively, technique diversity underpins sustained depth in the subcutaneous immunoglobulin market.
Complete Report Scope:
- By Application
- Primary Immunodeficiency
- Secondary Immunodeficiency
- Chronic Inflammatory Demyelinating Polyneuropathy (CIDP)
- Multifocal Motor Neuropathy (MMN)
- Other Applications
- By Administration Technique
- Conventional Pump
- Rapid Push
- Facilitated (fSCIG) Therapy
- By End User
- Hospitals
- Homecare Settings
- Specialty Clinics & Infusion Centers
- Others
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America owns 40.85% revenue because the United States diagnoses roughly 150,000-200,000 primary immunodeficiency patients and maintains extensive home-infusion benefits under both commercial plans and Medicare. Canada reimburses therapy through provincial formularies and delivers product via hospital or community programs, while Mexico's public-sector tenders are enlarging to include subcutaneous options. Recent Medicare rule changes that reimburse nursing time for home infusions further strengthen adoption. Robust plasma-collection infrastructure, predominantly in the United States, guarantees local supply and buffers international shocks.
Europe positions itself as a self-sufficient producer: the United Kingdom reached 25% domestic plasma self-sufficiency in 2025 and targets 30-35% by 2031. Germany operates the largest fractionation capacity, while France, Italy, and Spain prioritize national plasma-collection drives. The European Medicines Agency supports accelerated reviews for facilitated formulations, as evidenced by HYQVIA's centralized authorization and XEMBIFY's pan-EU label expansion. COVID-19 supply disruptions prompted investment in strategic plasma reserves, synchronizing public health and industrial policy.
Asia-Pacific is the fastest-growing region at 8.98% CAGR, prompted by Japan's 2024 HYQVIA approval and widening reimbursement in urban China. Australia's National Blood Authority supplies product for home administration every two months, embedding subcutaneous formulations into standard care. South Korea leverages its biopharmaceutical ecosystem to push local fractionation projects, while Indonesia attracted inward investment for a first-of-its-kind plasma facility. Challenges include fragmented regulatory frameworks and limited donor networks in emerging markets, but multilateral health-security programs supply technical assistance. The expanding base of qualified fractionation plants lays a durable foundation for the long-term growth of the subcutaneous immunoglobulin market.
- Takeda Pharmaceuticals
- CSL Behring
- Grifols
- Octapharma
- Kedrion Biopharma
- Biotest
- Bio Products Laboratory (BPL)
- ADMA Biologics
- GC Biopharma
- Sanquin
- LFB SA
- Emergent Bio Solutions
- China Biologic Products
- Kamada Ltd.
- Argenx SE
- Octapharma Plasma Inc. (US)
- Intas Pharmaceuticals
- Bioplasma Argentina
- Bharat Serums & Vaccines
- Green Cross Health
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Prevalence of Primary Immunodeficiency Disorders (PID)
- 4.2.2 Shift from IVIG to Home-based SCIG Administration
- 4.2.3 Aging Population & Rising Chronic Disease Burden
- 4.2.4 Expanding Reimbursement & Plasma-collection Programs
- 4.2.5 Hyaluronidase-facilitated High-volume fSCIG Adoption
- 4.2.6 Decentralised Plasma Sourcing Initiatives
- 4.3 Market Restraints
- 4.3.1 Stringent Regulatory & Quality Requirements
- 4.3.2 High Therapy Cost & Reimbursement Friction
- 4.3.3 Global Plasma Supply Constraints
- 4.3.4 Emerging FcRn-inhibitor Biologics as Substitutes
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value -USD)
- 5.1 By Application
- 5.1.1 Primary Immunodeficiency
- 5.1.2 Secondary Immunodeficiency
- 5.1.3 Chronic Inflammatory Demyelinating Polyneuropathy (CIDP)
- 5.1.4 Multifocal Motor Neuropathy (MMN)
- 5.1.5 Other Applications
- 5.2 By Administration Technique
- 5.2.1 Conventional Pump
- 5.2.2 Rapid Push
- 5.2.3 Facilitated (fSCIG) Therapy
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Homecare Settings
- 5.3.3 Specialty Clinics & Infusion Centers
- 5.3.4 Others
- 5.4 By Distribution Channel
- 5.4.1 Hospital Pharmacies
- 5.4.2 Retail Pharmacies
- 5.4.3 Online Pharmacies
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles
- 6.3.1 Takeda Pharmaceutical Company Limited
- 6.3.2 CSL Behring
- 6.3.3 Grifols SA
- 6.3.4 Octapharma AG
- 6.3.5 Kedrion SpA
- 6.3.6 Biotest AG
- 6.3.7 Bio Products Laboratory (BPL)
- 6.3.8 ADMA Biologics
- 6.3.9 GC Pharma
- 6.3.10 Sanquin
- 6.3.11 LFB SA
- 6.3.12 Emergent BioSolutions
- 6.3.13 China Biologic Products
- 6.3.14 Kamada Ltd.
- 6.3.15 Argenx SE
- 6.3.16 Octapharma Plasma Inc. (US)
- 6.3.17 Intas Pharmaceuticals
- 6.3.18 Bioplasma Argentina
- 6.3.19 Bharat Serums & Vaccines
- 6.3.20 Green Cross Health