|
시장보고서
상품코드
2123750
유압 장비 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Hydraulic Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
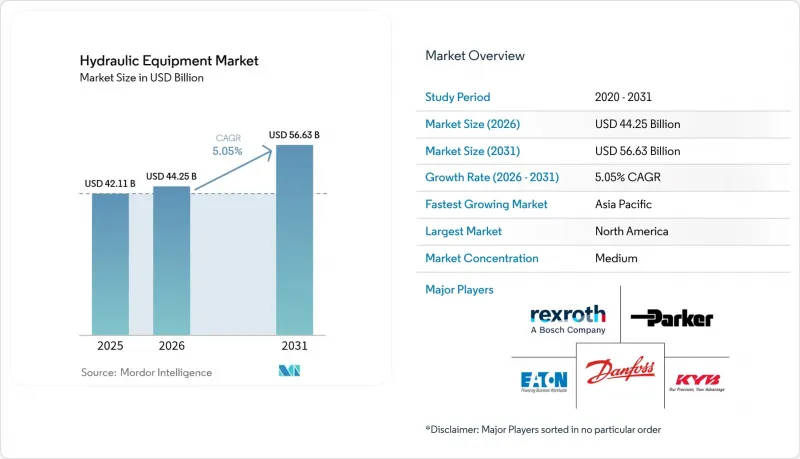
유압 장비 시장 규모는 2025년에 421억 1,000만 달러로 평가되었습니다. 2026년 442억 5,000만 달러에서 2031년까지 566억 3,000만 달러에 이를 것으로 추정되고 예측 기간(2026-2031년) CAGR은 5.05%를 나타낼 전망입니다.

본 보고서는 장비 유형(펌프, 밸브, 실린더, 모터, 필터 및 어큐뮬레이터, 변속기, 기타),최종 사용자 산업(건설, 농업, 자재관리 등), 용도(이동식 유압 장비 및 산업용 고정식 유압 장비), 작동 압력 범위(저압, 중압, 고압), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 유압 장비 시장 동향 및 인사이트
전자상거래 주문 처리 분야의 창고 자동화 가속화
전자상거래 주문량이 폭발적으로 증가함에 따라, 물류 센터에서는 mm 단위의 정밀도를 실현하는 소형 서보 유압 실린더를 채택한 자율 주행 지게차, 셔틀 시스템 및 ‘상품에서 사람으로(Goods-to-Person)’ 방식의 로봇 도입이 시급해지고 있습니다. 아마존의 이동형 로봇 네트워크는 연중무휴 24시간 가동에서 다운타임을 최소화하기 위해 누출이 없고 센서가 장착되어 있으며 예측 유지보수 경보 기능을 갖춘 유압 시스템이 필수적임을 보여줍니다. 창고 운영 사업자들로부터 일반적으로 40%의 생산성 향상이 보고되고 있으며, 이를 통해 부품 공급업체는 신뢰성이 매우 높고 오염이 관리된 조립품에 대해 프리미엄 가격을 책정할 수 있게 되었습니다.
정부 자금 지원 대규모 인프라 계획
1조 2,000억 달러 규모의 ‘미국 인프라 투자 및 고용법’부터 1조 4,000억 달러 규모의 중국 지방 정부 부채 계획에 이르기까지, 수년에 걸친 유틸리티은 굴삭기, 콘크리트 펌프, 대구경 실린더에 대한 수요 전망을 명확히 하고 있습니다. 프로젝트 파이프라인이 확대됨에 따라, 각 OEM 업체들은 장기 계약을 확실하게 확보하고 지역 서비스 거점을 확충하는 동시에, 교량, 항만, 재생 에너지 건설용 특수 목적 유압 시스템을 공동 개발할 수 있게 되었습니다.
철강 및 희토류 원자재 가격 변동 심화
2024년에는 철강 가격이 40%나 변동한 반면, 희토류 가공 분야에서 중국의 지배적인 지위는 자석 모터공급망을 지정학적 위험에 노출시켰습니다. 중국이 유압 부품에 부과하는 44-54%의 관세는 이익률을 더욱 압박하고 있으며, 공급업체들은 원자재 헤지, 자재 사용량 감축을 위한 설계 변경, 혹은 합병을 통한 규모 확대를 강요받고 있습니다.
부문별 분석
2025년, 펌프는 건설, 농업, 산업기계의 모든 분야에서 필수적인 동력원으로 유압 장비 시장의 27.85%를 차지했습니다. 가변 용적형 및 부하 감지형 모델은 연료 소비를 줄이고 OEM의 효율 목표를 충족시키는 동시에 애프터마켓에서의 개조 판매를 촉진하고 있습니다. 펌프의 유압 장비 시장 규모는 2031년까지의 인프라 투자 주기에 따라 확대될 전망입니다. 필터 및 어큐뮬레이터는 6.18%의 연평균 성장률(CAGR)로 가장 빠른 성장세를 기록하고 있습니다. 이는 ISO 4406 청정도 규격이 강화됨에 따라 보증 협상에서 오염 관리가 결정적인 요소가 되었기 때문입니다. 고유량·저차압 필터 매체에 대한 수요가 증가하면서 이익률을 끌어올리고 있습니다. 한편, 질소 충전식 블래더는 하이브리드 회로에서 회생 에너지를 축적하여, 이동체 용도에서 이 하위 부문의 유압 장비 시장 점유율을 확대시키고 있습니다.
밸브 공급업체들은 원격 조작 및 자율 작업에 요구되는 정밀한 유량 제어를 비즈니스 기회로 활용하고 있습니다. 실린더는 재현성이 높고 고주기의 직선 운동이 필요한 EC 물류창고 로봇 기술의 혜택을 받고 있습니다. 모터와 변속기는 토크 밀도와 과부하 용량이 여전히 중요한 요소인 특수 이동 장비에 공급되고 있습니다. 부속 부품(리저버, 매니폴드, 쿨러)은 OEM 조립 라인을 간소화하고 시장 출시 기간을 단축하는 통합형 파워팩의 혜택을 받고 있습니다.
건설 분야는 전 세계 유틸리티 계획 및 상업용 부동산 착공에 힘입어 2025년 유압 장비 시장 매출의 31.05%를 차지했습니다. 차량 운영 사업자들은 현장에서의 배기가스 규제 강화에 대응하기 위해 전기-유압 하이브리드를 채택하고 있으며, 이를 통해 높은 가동률과 부품 소비가 유지되고 있습니다. 건설 분야의 유압 장비 시장 규모는 교량, 항만, 철도 프로젝트에서 수년에 걸친 공정을 통해 장행정 액추에이터와 헤비듀티 펌프가 소비됨에 따라, 안정적인 한 자릿수 중반대의 성장이 예상됩니다. 한편, 항공우주 및 방위 분야는 민간용 협폭기(나로우드바디) 생산 확대와 방위 기관의 기체 현대화에 따라 연평균 성장률(CAGR) 6.35%라는 가장 급격한 성장 궤도를 보이고 있습니다. 비행 제어 및 착륙 장치용 고압 및 중량 최적화 액추에이터는 고가대로 거래되고 있으며, 이로 인해 항공우주 공급업체가 차지하는 유압 장비 시장 점유율이 확대되고 있습니다.
농업 분야에서는 센티미터 단위의 정밀도로 종자를 파종하기 위한 GPS 유도식 유압 시스템이 정밀 농업에 도입됨에 따라 꾸준한 성장을 유지하고 있습니다. 자재관리 분야는 옴니채널 소매 물류의 확대로 활기를 띠고 있는 반면, 석유 및 가스 분야 수요는 해양 건설 및 파이프라인 유지 관리를 중심으로 안정세를 보이고 있습니다. 공작기계, 플라스틱, 자동차 각 부문에서는 세계 제조 주기에 연동되어 동향에 편차가 나타나고 있지만, 씰, 밸브, 소구경 실린더 수요를 지탱하는 필수적인 수요의 기둥으로 계속 자리 잡고 있습니다.
지역별 분석
북미는 수자원 인프라 정비에 배정된 688억 달러와 간척 프로젝트에 투입된 8억 5,000만 달러의 자금을 바탕으로 2025년에는 전 세계 매출의 37.65%를 차지했습니다. 창고 자동화에 대한 꾸준한 투자와 노후화된 차량의 교체가 실린더, 비례 밸브, 여과 키트의 매출을 뒷받침하고 있습니다. 그러나 운송 장비 시장의 침체가 역풍으로 작용하고 있어, 공급업체들은 애프터마켓 서비스 계약 및 디지털화된 유지보수 서비스 제공에 주력하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 8.07%로 가장 빠른 성장세를 기록하고 있습니다. 이는 중국의 1조 4,000억 달러 규모의 신용 공급 패키지와 인도의 도시 철도 및 상수도 유틸리티으로 인해 국내 경기 주기를 넘어 수요가 정점을 유지하고 있기 때문입니다. 현지 OEM 기업들은 Tier 4f 기준을 충족하기 위해 부품 전문 제조업체와 제휴하고 있는 반면, 관세 분쟁을 배경으로 다국적 공급업체들은 동남아시아로의 조립 거점 다각화를 추진하고 있습니다. 고압 마이크로펌프와 내오염성 밸브는 한국과 일본의 정밀 제조 클러스터에서 채택이 확대되고 있습니다.
유럽의 전망은 엇갈리고 있습니다. 2024년 독일의 유체 동력 관련 수주량은 8% 감소했지만, 프랑스의 ‘그랑 파리 익스프레스’나 이탈리아의 풍력 발전소 건설과 같은 프로젝트가 틈새 고압 수요를 견인하고 있습니다. PFAS 규제로 인해 바이오 씰로의 전환이 가속화되고 있으며, 유압 장비 시장 전반에 걸쳐 막대한 연구개발 투자가 촉진되고 있습니다. ‘REPowerEU’ 계획에 따른 재생에너지 인프라에 대한 3,000억 유로(3,390억 달러)의 예산 배정으로 인해, 해상 풍력 발전 설비 설치 선박용 텔레스코픽 실린더 수요가 확대되어 거시경제의 둔화를 완화하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.16According to Mordor Intelligence, the hydraulic equipment market size was valued at USD 42.11 billion in 2025 and estimated to grow from USD 44.25 billion in 2026 to reach USD 56.63 billion by 2031, at a CAGR of 5.05% during the forecast period (2026-2031).
This report is Segmented by Equipment Type (Pumps, Valves, Cylinders, Motors, Filters and Accumulators, Transmissions, and Others), End-User Industry (Construction, Agriculture, Material Handling, and More), Application (Mobile Hydraulics and Industrial Stationary Hydraulics), Operating-Pressure Range (Low, Medium, and High), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Hydraulic Equipment Market Trends and Insights
Accelerated Warehouse Automation in E-commerce Fulfillment
Explosive e-commerce order volumes compel distribution centers to deploy autonomous forklifts, shuttle systems, and goods-to-person robots that rely on compact servo-hydraulic cylinders for milli-meter accuracy. Amazon's network of mobile robots illustrates how 24/7 operation requires leak-free, sensor-equipped hydraulics offering predictive failure alerts to minimize downtime. Warehouse operators typically report 40% productivity gains, enabling component suppliers to charge premium prices for ultra-reliable, contamination-controlled assemblies.
Government-Funded Mega-Infrastructure Programmes
Multi-year public works-from the USD 1.2 trillion U.S. Infrastructure Investment and Jobs Act to China's USD 1.4 trillion local-government debt plan-create demand visibility for excavators, concrete pumps, and large-bore cylinders. Extended project pipelines allow OEMs to lock-in long-term contracts, expand regional service hubs, and co-develop application-specific hydraulics for bridge, port, and renewable-energy construction.
Intensifying Raw-Material Price Volatility for Steel and Rare Earths
Steel prices swung 40% in 2024, while China's dominance of rare-earth processing exposes magnet-motor supply chains to geopolitical risk. Tariffs of 44-54% on Chinese hydraulic components further compress margins, forcing suppliers to hedge commodities, redesign to reduce material intensity, or pursue scale through mergers.
Other drivers and restraints analyzed in the detailed report include:
- Shift to Energy-Efficient Electro-Hydraulic Hybrids
- Increasing Off-Highway Electrification
- Skilled-Labor Shortage for Maintenance and Retrofits
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pumps anchored 27.85% of the hydraulic equipment market in 2025 as the indispensable power-source across construction, agriculture, and industrial machinery. Variable-displacement and load-sensing models cut fuel draw, satisfying OEM efficiency targets and boosting aftermarket retrofit sales. The hydraulic equipment market size for pumps is positioned to advance with infrastructure investment cycles through 2031. Filters and accumulators log the quickest gains at a 6.18% CAGR as stricter ISO 4406 cleanliness codes make contamination control decisive during warranty negotiations. Demand for high-flow, low-delta-pressure filter media elevates margins, while nitrogen-charged bladders store regenerative energy in hybrid circuits, extending the hydraulic equipment market share of this sub-segment across mobile applications.
Valve suppliers capitalize on precision flow control required by tele-operation and autonomous tasks. Cylinders benefit from e-commerce warehouse robotics that necessitate repeatable, high-cycle linear motion. Motors and transmissions cater to specialty mobile equipment where torque density and overload capacity remain critical. Ancillary components-reservoirs, manifolds, coolers-gain from integrated power-packs that simplify OEM assembly lines and shorten time-to-market.
Construction contributed 31.05% of hydraulic equipment market revenue in 2025, buoyed by global public-works pipelines and commercial real-estate starts. Fleet operators adopt electro-hydraulic hybrids to meet stricter job-site emissions caps, sustaining high utilization and parts consumption. The hydraulic equipment market size for construction is poised for stable mid-single-digit growth as bridge, port, and rail projects consume long-stroke actuators and heavy-duty pumps over multi-year timelines. Aerospace and defense, however, posts the sharpest trajectory at 6.35% CAGR as commercial narrow-body production ramps and defense agencies modernize airframes. High-pressure, weight-optimized actuation for flight-control and landing-gear commands premium pricing, increasing the hydraulic equipment market share captured by aerospace suppliers.
Agriculture maintains steady gains as precision farming embeds GPS-guided hydraulics for centimeter-level seed placement. Material-handling thrives on omnichannel retail logistics, while oil and gas demand stabilizes around offshore construction and pipeline maintenance. Machine-tool, plastics, and automotive segments experience mixed trends tied to global manufacturing cycles yet remain indispensable volume anchors for seal, valve, and small-bore cylinder demand.
Complete Report Scope:
- By Equipment Type
- Pumps
- Valves
- Cylinders
- Motors
- Filters and Accumulators
- Transmissions
- Others
- By End-user Industry
- Construction
- Agriculture
- Material Handling
- Aerospace and Defence
- Machine Tools
- Oil and Gas
- Hydraulic Press
- Plastics
- Automotive
- Other End-users
- By Application
- Mobile Hydraulics
- Industrial Stationary Hydraulics
- By Operating-Pressure Range
- Low (Less than 150 bar)
- Medium (150-350 bar)
- High (Greater than 350 bar)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 37.65% of global revenue in 2025, supported by USD 68.8 billion in obligated water-infrastructure funds and USD 850 million dedicated to reclamation projects. Robust warehouse-automation investments and aging fleet replacements underpin sales of cylinders, proportional valves, and filtration kits. Nevertheless, the softness of transport equipment presents a headwind, prompting suppliers to emphasize aftermarket service contracts and digitalized maintenance offers.
The Asia-Pacific region registers the fastest growth, with an 8.07% CAGR through 2031, as China's USD 1.4 trillion credit package and India's urban-rail and water-supply programs sustain demand peaks beyond domestic cycles. Local OEMs partner with component specialists to meet Tier 4f standards, while tariff disputes prompt multinational suppliers to diversify assembly footprints into Southeast Asia. High-pressure micro-pumps and contamination-resistant valves are seeing a rising take-up in Korean and Japanese precision-manufacturing clusters.
Europe presents a mixed outlook: German fluid-power orders fell 8% in 2024, yet projects such as France's Grand Paris Express and Italy's wind-farm builds drive niche high-pressure requirements. PFAS restrictions are accelerating the shift to bio-based seals, prompting significant R&D investment across the hydraulic equipment market. The REPowerEU plan's EUR 300 billion (USD 339 billion) allocation for renewable energy infrastructure multiplies demand for telescopic cylinders in offshore wind installation vessels, cushioning macroeconomic softness.
- Bosch Rexroth AG
- Parker Hannifin Corporation
- HYDAC International GmbH
- Danfoss A/S
- SMC Corporation
- Festo SE and Co. KG
- Norgren Limited (IMI plc)
- Bucher Hydraulics GmbH (Bucher Industries AG)
- HAWE Hydraulik SE
- Linde Hydraulics GmbH and Co. KG
- Caterpillar Inc.
- KYB Corporation
- Eaton Corporation plc
- Kawasaki Heavy Industries Ltd.
- Yuken Kogyo Co., Ltd.
- Daikin Industries, Ltd.
- Komatsu Ltd.
- Sun Hydraulics LLC (Helios Technologies, Inc.)
- Moog Inc.
- Argo-Hytos Group AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry Supply-Chain Analysis
- 4.3 Regulatory Landscape
- 4.4 Technological Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
- 4.6 Market Drivers
- 4.6.1 Accelerated warehouse automation in e-commerce fulfilment
- 4.6.2 Government-funded mega infrastructure programmes
- 4.6.3 Shift to energy-efficient electro-hydraulic hybrids
- 4.6.4 Increasing off-highway electrification driving compact power-dense hydraulics
- 4.6.5 Growing adoption of precision agriculture machinery
- 4.6.6 Ageing industrial machinery replacement cycle in OECD
- 4.7 Market Restraints
- 4.7.1 Total cost of ownership (TCO) higher than electric drives in light-duty ranges
- 4.7.2 Intensifying raw-material price volatility for steel and rare earths
- 4.7.3 Rising ESG scrutiny over hydraulic-fluid leakage
- 4.7.4 Skilled-labour shortage for maintenance and retrofits
- 4.8 Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Equipment Type
- 5.1.1 Pumps
- 5.1.2 Valves
- 5.1.3 Cylinders
- 5.1.4 Motors
- 5.1.5 Filters and Accumulators
- 5.1.6 Transmissions
- 5.1.7 Others
- 5.2 By End-user Industry
- 5.2.1 Construction
- 5.2.2 Agriculture
- 5.2.3 Material Handling
- 5.2.4 Aerospace and Defence
- 5.2.5 Machine Tools
- 5.2.6 Oil and Gas
- 5.2.7 Hydraulic Press
- 5.2.8 Plastics
- 5.2.9 Automotive
- 5.2.10 Other End-users
- 5.3 By Application
- 5.3.1 Mobile Hydraulics
- 5.3.2 Industrial Stationary Hydraulics
- 5.4 By Operating-Pressure Range
- 5.4.1 Low (Less than 150 bar)
- 5.4.2 Medium (150-350 bar)
- 5.4.3 High (Greater than 350 bar)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Colombia
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Bosch Rexroth AG
- 6.4.2 Parker Hannifin Corporation
- 6.4.3 HYDAC International GmbH
- 6.4.4 Danfoss A/S
- 6.4.5 SMC Corporation
- 6.4.6 Festo SE and Co. KG
- 6.4.7 Norgren Limited (IMI plc)
- 6.4.8 Bucher Hydraulics GmbH (Bucher Industries AG)
- 6.4.9 HAWE Hydraulik SE
- 6.4.10 Linde Hydraulics GmbH and Co. KG
- 6.4.11 Caterpillar Inc.
- 6.4.12 KYB Corporation
- 6.4.13 Eaton Corporation plc
- 6.4.14 Kawasaki Heavy Industries Ltd.
- 6.4.15 Yuken Kogyo Co., Ltd.
- 6.4.16 Daikin Industries, Ltd.
- 6.4.17 Komatsu Ltd.
- 6.4.18 Sun Hydraulics LLC (Helios Technologies, Inc.)
- 6.4.19 Moog Inc.
- 6.4.20 Argo-Hytos Group AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment