|
시장보고서
상품코드
2123753
양자암호 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Quantum Cryptography - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
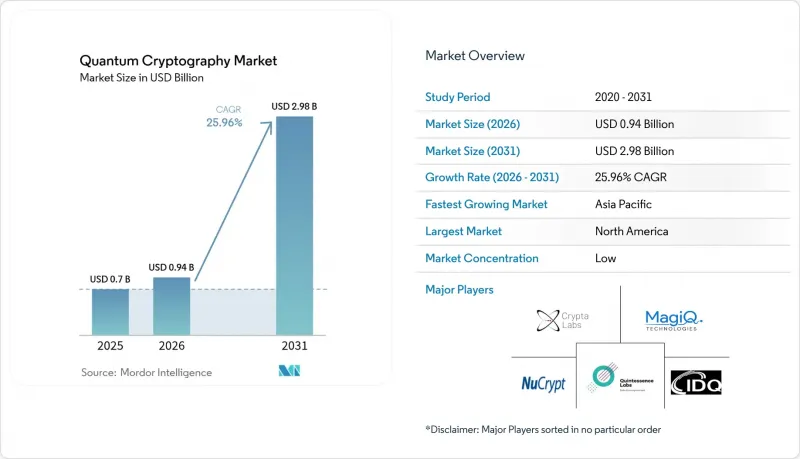
양자암호 시장 규모는 2025년 7억 달러, 2026년 9억 4,000만 달러에서 2031년까지 29억 8,000만 달러로 확대한다고 예측되고 있어 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 25.96%를 나타낼 전망입니다.
본 보고서는 구성 요소(하드웨어, 소프트웨어, 서비스), 기술(양자 키 배포, 포스트 양자암호, 양자 난수 생성 등), 도입 형태(On-Premise 등), 용도(네트워크 보안 등), 최종 사용자(IT 및 통신 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 양자암호 시장 동향 및 인사이트
양자 기술을 이용한 사이버 공격 증가
2025년, 공격자가 향후 복호를 목적으로 암호화된 트래픽을 가로채는 사건이 급증하면서, 논의는 이론적 위험에서 운영상의 위험으로 옮겨갔습니다. 금융 기관, 주요 방위 기업, 클라우드 제공업체는 이에 대응하여 QKD(양자 키 배포) 및 포스트 양자암호 모두에 대한 로드맵을 가속화하는 조치를 취했습니다. 현재 이사회에서는 ‘지금 수집하고 나중에 복호화(harvest-now-decrypt-later)’ 위험에 대해 분기별로 보고가 이루어지고 있으며, 보다 광범위한 IT 업데이트 주기에 앞서 양자 내성 업그레이드를 위한 예산이 우선적으로 배정되고 있습니다. 새로운 사이버 보험 계약에서 양자 관련 침해 사고를 제외하려는 보험사들의 움직임이 이러한 시급성을 더욱 높이고 있습니다. 그 결과, 양자암호 시장은 개념 증명(PoC) 단계에서 전사적 도입 단계로 전환되고 있습니다.
양자 통신 인프라에 대한 정부 자금
2025년에는 공공 부문의 투자액이 42억 달러에 달하여, 민간 도입의 위험을 완화하는 전국 규모의 백본 네트워크 구축이 뒷받침되었습니다. 중국 전역에 걸쳐 총 길이 1만 킬로미터에 달하는 광섬유 네트워크, EU의 주요 국경을 가로지르는 회선, 미국의 국방 위성 프로젝트, 그리고 일본의 도시 지역 내 구축은 모두 국내 공급업체들에게 주요 고객 기반을 마련해 주었습니다. 이러한 초기 네트워크는 장거리 및 도시권 내에서의 성능을 입증하고, 상용 서비스 수준 계약(SLA) 달성을 보여주었습니다. 또한, 정부 기관이 상호 운용 가능한 장비를 요구함에 따라 보조금을 통한 표준화 작업도 가속화되었으며, 다중 공급업체 전략을 검토하는 기업들에게 벤더 락인(vendor lock-in)에 대한 우려가 간접적으로 완화되었습니다.
QKD 하드웨어의 높은 도입 및 유지보수 비용
단일 광자 검출기, 고정밀 레이저, 동기화용 전자 기기는 여전히 제조 규모가 제한된 틈새 부품이기 때문에 노드당 지출이 50만 달러를 초과하는 경우가 빈번합니다. 가동 시간을 확보하려면 엄격한 환경 제어가 필요하기 때문에 유지보수 계약은 운영 비용에 큰 부담이 됩니다. 신흥 시장에서는 환율 변동으로 인해 수입 가격이 더욱 치솟아 가격 격차가 확대되고 있습니다. 각 벤더사는 소비 전력이 100와트 미만인 소형 19인치 랙 유닛으로 대응하고 있지만, 비용 곡선은 여전히 기존 네트워크 장비에 비해 한 자릿수 높은 수준에 머물러 있어, 가격에 민감한 지역에서의 양자암호 시장 보급을 지연시키고 있습니다.
부문 분석
양자암호 시장의 구성 요소별 시장 규모를 보면, 하드웨어가 2025년 매출의 46.19%를 차지하며 1위를 차지하고 있는데, 이는 전용 송신기, 수신기 및 포토닉 스위치가 필요했던 초기 네트워크 구축을 반영한 것입니다. 그러나 장비, 통합, 연중무휴 24시간 모니터링을 패키지로 묶은 운영 비용(OPEX) 기반 계약을 선호하는 기업의 비율이 증가하고 있습니다. 그 결과, 서비스 부문은 2031년까지 26.67%의 성장이 예상되며, 이는 구성 요소 중 가장 높은 성장률입니다. 이는 보다 광범위한 IT 아웃소싱 동향을 반영한 구독 모델에 힘입은 것입니다.
서비스로의 전환 추세는 사내 양자 기술 인력 부족과 규제 당국이 주요 관리 업무에 대한 제3자 감사를 요구하고 있는 점도 뒷받침하고 있습니다. 전력 소비량이 100와트 미만인 소형 랙 마운트형 QKD 노드는 코로케이션을 간소화하지만, 단일 광자 검출기의 일상적인 조정은 여전히 전문 지식을 필요로 합니다. 각 벤더들이 QKD 소스를 기존의 공개 키 인프라(PKI) 플랫폼과 연동하는 API를 공개함에 따라 소프트웨어는 계속 성숙해 가고 있지만, 관리된 오케스트레이션이 없다면 많은 기업들은 여전히 정책 운영에 어려움을 겪고 있습니다. 현장 경험이 축적됨에 따라, 서비스 카탈로그에는 현재 양자 위험 평가, 자동화된 키 수명 주기 관리, 규정 준수 보고 등이 포함되게 되어 양자암호 시장의 제공 내용을 더욱 풍성하게 하고 있습니다.
양자 키 배분(QKD)은 정보 이론에 기반한 키 교환에서 입증된 유일한 방법으로 남아 있기 때문에 2025년 기술 지출의 54.16%를 차지했습니다. 그러나 고객들이 QKD 채널, 포스트 양자암호, 양자 난수 생성기를 통합한 대시보드를 요구하고 있기 때문에 통합형 양자 보안 통신 플랫폼은 2031년까지 연평균 성장률(CAGR) 26.91%라는 최고의 성장률을 나타낼 것으로 예측됩니다. 이러한 플랫폼 접근 방식은 운영상의 사일로화를 완화하고, 보안 팀이 이미 방화벽 및 VPN 집중기를 관리하는 방식과 일관성을 유지합니다.
NIST에 의한 알고리즘 표준화에 따라, 포스트 양자암호 소프트웨어의 양자암호 시장 점유율은 확대되고 있습니다. 특히, 광섬유 거리나 예산 제약으로 인해 QKD 도입이 어려운 상황에서 이러한 경향이 두드러집니다. 또한, QRNG 실리콘은 현재 하드웨어 보안 모듈(HSM)에 통합되어 있어, 사이드 채널을 통해 악용되는 엔트로피 격차를 해소하고 있습니다. 마지막으로, 위성 QKD는 실증 실험 단계에서 제한적인 상용 시범 단계로 전환되고 있으며, 광섬유 백본이 구축되지 않은 지역에 전 세계적인 커버리지를 제공합니다. 이러한 기법들을 종합함으로써, 양자 보안은 단순한 이색적인 부가 기능이 아닌 통합된 기능으로 재정의되고 있습니다.
지역별 분석
북미는 금융 서비스 및 국방 분야에서의 조기 도입을 통해 2025년 매출의 36.67%를 차지하며 양자암호 시장을 주도하고 있습니다. 그 활동은 대도시권의 광섬유 회랑에서 실험적인 위성 링크에 이르기까지 다양하며, 연방 정부의 자금 지원과 강력한 벤처 생태계에 의해 뒷받침되고 있습니다. 유럽은 이에 근소한 차이로 뒤를 잇고 있으며, EU의 ‘Quantum Flagship’을 활용하여 국경을 초월한 인증 조화를 도모하고, 지역 벤더 클러스터에 대한 보조금을 지원하고 있습니다. 파리-베를린-비엔나 간 링크를 통한 성능 벤치마크는 이미 EU 전역의 조달 기준에 반영되었습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 연평균 성장률(CAGR) 27.01%가 예상됩니다. 이는 중국의 국가 백본, 일본의 도쿄·오사카 간 도시권 네트워크 구축, 그리고 한국의 QRNG 지원 5G 기지국 네트워크에 의해 주도되고 있습니다. 이러한 프로젝트들은 국내 공급망을 구축하고 부품 비용을 절감하는 동시에, 현지 표준화 기관의 영향력을 높이고 있습니다.
중동 및 아프리카 시장은 아직 발전 단계에 있지만, 걸프 국가들의 스마트 시티 구상 속에서 금융 허브 및 핵심 인프라 확보를 위해 정부계 펀드가 자금을 투입하고 있어 전략적으로 중요한 위치를 차지하고 있습니다. 라틴아메리카에서는 진척도에 편차가 나타나고 있습니다. 브라질 정부 네트워크 시범 사업은 광검출기 공급 부족으로 인해 일정이 지연되고 있으며, 이는 공급망의 취약성이 여전히 지역 내 전개에 영향을 미치고 있음을 보여주는 실례입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the quantum cryptography market size is projected to expand from USD 0.70 billion in 2025 and USD 0.94 billion in 2026 to USD 2.98 billion by 2031, registering a CAGR of 25.96% between 2026 to 2031.
This report is Segmented by Component (Hardware, Software, and Services), Technology (Quantum Key Distribution, Post-Quantum Cryptography, Quantum Random Number Generation, and More), Deployment Mode (On-Premises, and More), Application (Network Security, and More), End-User (IT and Telecommunications, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Quantum Cryptography Market Trends and Insights
Rising Number of Quantum-Enabled Cyber-Attacks
Incidents in which adversaries captured encrypted traffic for future decryption rose sharply during 2025, moving the discussion from theoretical to operational risk. Financial institutions, defense primes, and cloud providers reacted by accelerating roadmaps for both QKD and post-quantum cryptography. Boards are now briefed quarterly on "harvest-now-decrypt-later" exposures, pushing budgets for quantum-safe upgrades ahead of broader IT refresh cycles. Insurance carriers excluding quantum-related breaches from new cyber policies are amplifying the urgency. As a result, the quantum cryptography market is transitioning from proof-of-concept trials to enterprise-wide rollouts.
Government Funding for Quantum Communication Infrastructure
Public-sector capital reached USD 4.2 billion in 2025, underwriting nationwide backbones that de-risk private adoption. China's 10 000-kilometer fiber network, the EU's flagship cross-border links, U.S. defense satellite projects, and Japan's metro deployments all created anchor tenants for domestic vendors. These early networks validated performance over long haul and urban metro distances, demonstrating commercial service-level agreements. Subsidies also accelerated standards work because agencies demanded interoperable gear, indirectly lowering vendor lock-in fears for enterprises evaluating multi-supplier strategies.
High Deployment and Maintenance Costs of QKD Hardware
Per-node spending frequently exceeds USD 500 000 because single-photon detectors, precision lasers, and synchronization electronics remain niche components with limited manufacturing scale. Maintenance contracts add material operational expenditure because uptime requires tight environmental control. Currency volatility further inflates import prices in emerging markets, widening the affordability gap. Vendors are responding with compact 19-inch rack units that consume under 100 watts, but cost curves still trail conventional networking equipment by an order of magnitude, slowing the quantum cryptography market adoption in price-sensitive regions.
Other drivers and restraints analyzed in the detailed report include:
- Need for Quantum-Safe Security in 5G and IoT Ecosystems
- Standardization Progress at ETSI and ITU Enabling Interoperable QKD
- Shortage of Skilled Quantum-Security Professionals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The quantum cryptography market size for components shows hardware leading with 46.19% of 2025 revenue, reflecting early network buildouts that required dedicated transmitters, receivers, and photonic switches. A growing share of enterprises, however, prefer opex-based engagements that bundle equipment, integration, and 24/7 monitoring. Services consequently are projected to grow at 26.67% through 2031, the fastest among components, supported by subscription models that mirror broader IT outsourcing trends.
Momentum toward services is also propelled by a lack of internal quantum talent and by regulators urging third-party audits of key management operations. Compact rackmount QKD nodes consuming under 100 watts simplify colocation, yet day-to-day tuning of single-photon detectors remains specialized. Software continues to mature as vendors expose APIs that link QKD sources to classical public-key-infrastructure platforms, but without managed orchestration, many enterprises still struggle to operationalize policies. As field experience accumulates, service catalogues now include quantum-risk assessments, automated key-lifecycle management, and compliance reporting, rounding out the quantum cryptography market offering.
Quantum key distribution commanded 54.16% of 2025 technology spend because it remains the only field-proven method for information-theoretic key exchange. Yet integrated quantum secure communications platforms should post the highest growth, 26.91% CAGR to 2031, as customers demand unified dashboards that merge QKD channels, post-quantum cryptography, and quantum random number generators. This platform approach reduces operational silos and matches how security teams already manage firewalls and VPN concentrators.
The quantum cryptography market share for post-quantum cryptography software is expanding following NIST algorithm standardization, especially where fiber distance or budget constraints preclude QKD. QRNG silicon is now embedded inside hardware security modules, closing entropy gaps exploited via side-channels. Finally, satellite QKD has moved from demonstrations to limited commercial pilots, offering global coverage for regions lacking fiber backbones. Together, these modalities reposition quantum security as an integrated feature rather than an exotic bolt-on.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Technology
- Quantum Key Distribution (QKD)
- Post-Quantum Cryptography (PQC)
- Quantum Random Number Generation (QRNG)
- Quantum Secure Communications Platforms
- By Deployment Mode
- On-Premises
- Cloud
- Hybrid
- By Application
- Network Security
- Application Security
- Database/Storage Security
- Secure Cloud Access
- Other Applications
- By End-User
- IT and Telecommunications
- BFSI
- Government and Defense
- Healthcare and Life Sciences
- Energy and Utilities
- Other End-Users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East
- GCC
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
North America led the quantum cryptography market with 36.67% of 2025 revenue owing to early financial-services and defense rollouts. Activity spans both metropolitan fiber corridors and experimental satellite links, anchored by federal funding and strong venture ecosystems. Europe follows closely, leveraging the EU Quantum Flagship to harmonize cross-border certification and subsidize regional vendor clusters. Performance benchmarks from Paris-Berlin-Vienna links have already fed back into procurement standards across the bloc.
Asia-Pacific is the fastest-growing region, projected at 27.01% CAGR, propelled by China's national backbone, Japan's Tokyo-Osaka metro buildouts, and South Korea's QRNG-enabled 5G base-station networks. These projects create domestic supply chains, lowering component costs and accelerating local standardization bodies' influence.
Middle East and Africa markets are nascent but strategically important as Gulf smart-city initiatives allocate sovereign wealth to secure financial hubs and critical infrastructure. Latin America is progressing unevenly; Brazil's pilot government network has slipped schedules because of photonic-detector shortages, illustrating how supply-chain fragility still shapes regional rollouts.
- ID Quantique SA
- Toshiba Corporation
- QuantumCTek Co., Ltd.
- QuintessenceLabs Pty Ltd
- Huawei Technologies Co., Ltd.
- Crypta Labs Ltd.
- MagiQ Technologies, Inc.
- NuCrypt LLC
- PQ Solutions Ltd.
- ISARA Corporation
- Quantum Xchange Inc.
- QuNu Labs Pvt Ltd
- Qutools GmbH
- AUREA Technology
- Infineon Technologies AG
- KETS Quantum Security Ltd.
- IBM Corporation
- Qrypt Inc.
- BT Group plc
- SK Telecom Co., Ltd.
- NEC Corporation
- Verizon Communications Inc.
- ZTE Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Number of Quantum-Enabled Cyber-Attacks
- 4.2.2 Government Funding for Quantum Communication Infrastructure
- 4.2.3 Need for Quantum-Safe Security in 5G and IoT Ecosystems
- 4.2.4 Standardization Progress at ETSI and ITU Enabling Interoperable QKD
- 4.2.5 Emergence of Quantum Network Testbeds Accelerating Commercial Pilots
- 4.2.6 Convergence of QKD with Software-Defined Networking for Automated Key Orchestration
- 4.3 Market Restraints
- 4.3.1 High Deployment and Maintenance Costs of QKD Hardware
- 4.3.2 Shortage of Skilled Quantum-Security Professionals
- 4.3.3 Photonic Component Supply-Chain Bottlenecks
- 4.3.4 Inconsistent Quantum Channel Certification Frameworks Across Jurisdictions
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Competition
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Technology
- 5.2.1 Quantum Key Distribution (QKD)
- 5.2.2 Post-Quantum Cryptography (PQC)
- 5.2.3 Quantum Random Number Generation (QRNG)
- 5.2.4 Quantum Secure Communications Platforms
- 5.3 By Deployment Mode
- 5.3.1 On-Premises
- 5.3.2 Cloud
- 5.3.3 Hybrid
- 5.4 By Application
- 5.4.1 Network Security
- 5.4.2 Application Security
- 5.4.3 Database/Storage Security
- 5.4.4 Secure Cloud Access
- 5.4.5 Other Applications
- 5.5 By End-User
- 5.5.1 IT and Telecommunications
- 5.5.2 BFSI
- 5.5.3 Government and Defense
- 5.5.4 Healthcare and Life Sciences
- 5.5.5 Energy and Utilities
- 5.5.6 Other End-Users
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Russia
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 GCC
- 5.6.5.2 Turkey
- 5.6.5.3 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ID Quantique SA
- 6.4.2 Toshiba Corporation
- 6.4.3 QuantumCTek Co., Ltd.
- 6.4.4 QuintessenceLabs Pty Ltd
- 6.4.5 Huawei Technologies Co., Ltd.
- 6.4.6 Crypta Labs Ltd.
- 6.4.7 MagiQ Technologies, Inc.
- 6.4.8 NuCrypt LLC
- 6.4.9 PQ Solutions Ltd.
- 6.4.10 ISARA Corporation
- 6.4.11 Quantum Xchange Inc.
- 6.4.12 QuNu Labs Pvt Ltd
- 6.4.13 Qutools GmbH
- 6.4.14 AUREA Technology
- 6.4.15 Infineon Technologies AG
- 6.4.16 KETS Quantum Security Ltd.
- 6.4.17 IBM Corporation
- 6.4.18 Qrypt Inc.
- 6.4.19 BT Group plc
- 6.4.20 SK Telecom Co., Ltd.
- 6.4.21 NEC Corporation
- 6.4.22 Verizon Communications Inc.
- 6.4.23 ZTE Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment