

|
시장보고서
상품코드
2123758
공압 장비 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Pneumatic Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
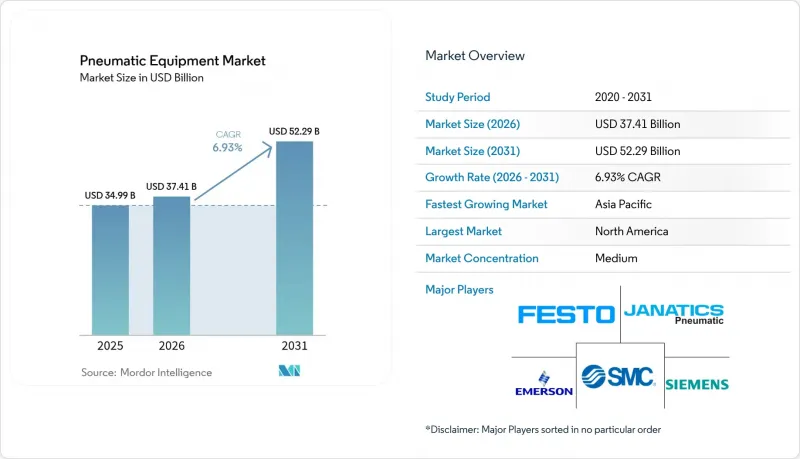
공압 장비 시장 규모는 2026년에 374억 1,000만 달러로 추정되고 있어 2025년 349억 9,000만 달러에서 확대해, 2031년에는 522억 9,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 6.93%로 성장할 것으로 전망됩니다.
본 보고서는 구성 부품(액추에이터, 밸브, 공기 처리 장치, 피팅 및 튜브 등), 기능(모션 제어, 유체 제어, 자재관리 등), 최종 사용자 산업(자동차, 식품 및 음료 가공·포장, 항공우주 및 방위 등),압력 범위(저압, 중압, 고압) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 공압 장비 시장 동향 및 인사이트
산업 전반에 걸친 자동화의 진전
공장의 대규모 디지털화로 인해 공압 장비의 설계가 재구성되고 있으며, 공급업체들은 예측 분석을 가능하게 하는 센서 및 무선 모듈의 통합을 추진하고 있습니다. SMC사의 무선 노드 ‘EXW1’은 밸브 매니폴드의 크기를 86% 줄였으며, 주요 산업용 이더넷 프로토콜을 지원함으로써 소형화와 연결성이 하나의 패키지에 융합되었음을 보여줍니다. 플랜트 관리자에게 있어 실린더나 밸브의 실시간 상태 데이터는 예기치 않은 가동 중단을 줄이고 근본 원인을 신속하게 분석하는 데 도움이 됩니다. 특히, 그린필드 방식의 ‘무인화’ 생산 라인을 구축하고 있는 전자, 자동차, 소비재 공장에서 도입 추세가 매우 강해지고 있습니다. ISO 11011에 기반한 규정 준수 감사를 통해 압축 공기의 기준치를 정량화하는 솔루션의 중요성이 더욱 높아지고 있으며, 디지털화된 공압 시스템은 매력적인 투자 대상으로 부상하고 있습니다. 측정 가능한 OEE(종합 설비 효율) 향상을 입증할 수 있는 공급업체는 기존 제품과의 직접 경쟁에서 우위를 점하고 있습니다.
에너지 효율이 높은 압축 공기 시스템에 대한 수요
압축 공기는 산업용 전력 부하의 약 10%를 차지하고 있으며, 2025년 1월에 발효되는 미국 에너지부(DOE)의 새로운 효율화 규정에 따라 기존 설비의 전면적인 교체가 시급해지고 있습니다. 아틀라스콥코의 하이브리드 컴프레서 제품군은 정속 모드와 VSD 모드를 전환함으로써 압력 안정성을 ±0.1 bar 이내로 유지하면서, 1대당 연간 9톤의 CO2 배출량을 감축할 수 있습니다. 유럽에서는 ASHRAE 90.1-2022에 압축 공기가 포함됨에 따라 건축 설계자에 대한 기준도 높아졌습니다. 경제적인 관점에서 볼 때, 누출률은 종종 30%를 초과하며, 개별 공장에서는 매년 수만 달러에 달하는 전력 낭비가 발생하고 있어, 이는 신속한 투자 회수가 기대되는 개조의 동기가 되고 있습니다. 현재 기업의 지속가능성 담당자들은 누출 감지 프로그램을 ‘손쉽게 실현할 수 있는 탈탄소화 성과’로 인식하고 있으며, 이로 인해 고효율 공압 장비에 대한 수요가 더욱 가속화되고 있습니다.
전체 수명 주기 동안의 높은 유지보수 비용과 에너지 비용
총 소유 비용(TCO) 감사에 따르면, 압축기의 수명 주기 비용 중 에너지 비용이 77%를 차지하는 것으로 밝혀졌으며, 이는 초기 투자액을 훨씬 상회하는 수치입니다. 누출 방지 프로그램은 소비량을 줄여주지만, 이를 시행하려면 계측 장비와 직원의 작업 시간이 필요하며, 소규모 공장에서는 이를 충분히 확보하지 못하는 경우가 많습니다. 호주 정부의 조사에 따르면 평균 누출률은 30%로 보고되어 전 세계적인 비효율성 추세를 뒷받침하고 있습니다. IIoT 센서는 누출을 자동으로 추적할 수 있게 해 주지만, 초기 하드웨어 비용과 분석 서비스 구독료가 가격에 민감한 사업자들에게는 장벽이 되고 있습니다. 유럽 일부 지역에서는 두 자릿수 전력 가격 상승이 지속되고 있어, 이로 인해 공압 시스템 비용에 대한 감시가 엄격해지고 있으며, 가동 주기가 허용하는 한 구매자들은 대체 구동 방식으로 눈을 돌리고 있습니다.
부문 분석
2025년, 업스윙 밸브(Upswing Valve)는 공압 장비 시장 점유율의 33.02%를 차지하며, 자동화 라인 내 압력 및 유량 제어에서 이 회사가 수행하는 핵심적인 역할을 부각시켰습니다. 픽 앤 플레이스 로봇에서 벌크 컨베이어에 이르기까지, 모든 회로가 작동 순서를 조정하기 위해 방향 제어 밸브와 비례 밸브에 의존하고 있기 때문에 이 회사의 우위는 계속되고 있습니다. 성장은 설치 시간을 단축하고 스마트 팩토리 아키텍처에 적합한, 컴팩트하고 프로토콜에 구애받지 않는 매니폴드로 기울고 있습니다.
액추에이터 시장은 연평균 성장률(CAGR) 7.46%로 확대되고 있으며, 이는 제조업체들이 더 높은 적재 정밀도와 더 빠른 사이클 속도를 요구하고 있음을 반영합니다. 에머슨의 XV 시리즈는 슬림한 설치 면적으로 분당 350 NL의 유량을 실현하여, 설계자가 처리량을 희생하지 않고도 캐비닛을 소형화할 수 있게 해줍니다. 청정 공기 요구 사항이 엄격해지는 가운데, 공기 처리 장치와 정밀 피팅이 구성 요소를 보완하는 한편, 예측 유지보수의 도입이 진행됨에 따라 센서용 액세서리 시장도 활기를 띠고 있습니다. 그 결과, 공압 장비 시장은 단일 부품에서 완전히 통합되고 데이터가 풍부한 어셈블리로 계속 전환되고 있습니다.
모션 제어 부문은 2025년 전체 공압 장비 시장 수요의 40.02%를 차지하며, 리니어 슬라이드, 로터리 테이블, 프레스 스테이션 등에서의 광범위한 보급을 반영하고 있습니다. 이 부문은 공압이 가진 뛰어난 출력 대 중량비와 밀리초 단위의 응답 속도라는 장점을 활용하고 있으며, 이러한 장점은 고속 조립 라인에서 높이 평가받고 있습니다. 현재, 추적성을 확보하기 위해 스트로크 데이터를 MES 플랫폼으로 전송하는 피드백 지원 실린더가 주목받고 있습니다.
전자상거래 물류가 자동 분류 센터를 견인하는 가운데, 자재관리 분야는 7.95%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. SMC의 RMH 그리퍼는 코봇과의 협업이 인증되었으며, 부드러운 터치로 물건을 잡는 방식이 새로운 SKU 처리 능력을 어떻게 개척해 나갈 수 있는지 보여주고 있습니다. 유체 제어는 공정 산업에서 틈새 시장을 유지하고 있는 반면, 반도체 웨이퍼 이송 분야에서는 진공 발생 기술이 확대되고 있습니다. 기술 융합이 두드러지며, 첨단 매니폴드가 위치 결정, 그립, 진공 제어 로직을 하나의 노드에 통합함으로써 공압 장비 시장에서 공급업체의 고객 충성도 향상에 기여하고 있습니다.
지역별 분석
북미는 고사양 솔루션을 필요로 하는 성숙한 항공우주, 제약, 자동차 부문 덕분에 2025년 전 세계 매출의 34.21%를 차지했습니다. 지멘스가 텍사스와 캘리포니아의 신규 공장에 100억 달러를 투자할 계획인 것은 이 지역에서 진행 중인 리쇼어링 추세를 보여주는 것으로, 이로 인해 모션, 밸브, 압축기 패키지 부품 수주가 증가하고 있습니다. 곧 시행될 미국 에너지부(DOE)의 압축기 규제는 설비 갱신 주기를 안정화시키는 개조 붐을 일으키고 있습니다.
아시아태평양은 7.66%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있으며, 중국, 인도, 아세안(ASEAN) 국가들이 새로운 반도체 공장 및 배터리 공장을 건설함에 따라 2031년까지 다른 지역과의 격차를 좁힐 전망입니다. 아틀라스콥코가 한국에 거점을 둔 경원머시너리를 4,650만 달러에 인수한 것은 공급의 현지화를 도모하고 급증하는 지역 수요에 대응하기 위한 전략적 움직임을 보여줍니다. 인도 및 베트남에서 반도체 자급자족을 촉진하기 위한 정부의 인센티브는 초저공해 공압 장비에 대한 새로운 수요를 창출하고 있습니다.
유럽은 엄격한 에너지 및 지속가능성 관련 지침에 힘입어 견조한 시장 점유율을 유지하고 있습니다. 보쉬 렉스로트가 멕시코에 1억 6,000만 유로를 투자해 건설한 공장은 유럽의 OEM 기업들이 채택하고 있는 ‘시장 분할 전략’을 여실히 보여주고 있습니다. 즉, 연구개발(R&D)은 본국에 유지하면서 미국 고객 기반 근처에 비용 효율적인 생산 능력을 구축하는 전략입니다. 남미와 중동에서 규모는 작지만 확대되고 있는 비즈니스 기회는 견고한 고압 공압 어레이가 필요한 석유화학 다각화 프로젝트에 좌우되고 있으며, 이로 인해 공압 장비 시장 수요가 서서히 증가하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the pneumatic equipment market size in 2026 is estimated at USD 37.41 billion, growing from 2025 value of USD 34.99 billion with 2031 projections showing USD 52.29 billion, growing at 6.93% CAGR over 2026-2031.
This report is Segmented by Component (Actuators, Valves, Air Preparation Units, Fittings and Tubing, and More), Function (Motion Control, Fluid Control, Material Handling, and More), End-User Industry (Automotive, Food and Beverage Processing and Packaging, Aerospace and Defense, and More), Pressure Range (Low, Medium, and High), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Pneumatic Equipment Market Trends and Insights
Increasing Automation Across Industries
Mass-scale factory digitalization is reshaping pneumatic design, prompting suppliers to embed sensors and wireless modules that allow predictive analytics. SMC's EXW1 wireless node trims valve-manifold size by 86% and supports leading industrial Ethernet protocols, demonstrating how miniaturization and connectivity now converge in a single package. For plant managers, real-time health data on cylinders and valves translates into fewer unplanned stops and faster root-cause analysis. Adoption momentum is especially strong in electronics, automotive, and packaged-goods plants building greenfield "lights-out" lines. Compliance audits under ISO 11011 give added weight to solutions that quantify compressed-air baselines, making digitally enabled pneumatics a compelling investment. Suppliers able to prove measurable OEE gains are winning head-to-head bids against legacy offerings.
Demand for Energy-Efficient Compressed-Air Systems
Compressed air accounts for roughly 10% of industrial electricity load, and new U.S. DOE efficiency rules effective January 2025 are forcing upgrades across the installed base. Atlas Copco's hybrid compressor portfolio, which toggles between fixed-speed and VSD modes, can trim annual CO2 output by 9 tons per unit while keeping pressure stability within +-0.1 bar. In Europe, ASHRAE 90.1-2022 inclusion of compressed air raises the bar for building designers as well. From a financial angle, leak rates often exceed 30% and cost individual factories tens of thousands of dollars in wasted power each year, incentivizing rapid payback retrofits. Enterprise sustainability officers now view leak-detection programs as low-hanging decarbonization wins, further accelerating demand for high-efficiency pneumatics.
High Lifetime Maintenance and Energy Costs
Total cost-of-ownership audits reveal that energy can make up 77% of compressor lifecycle expense, dwarfing capital outlay. Leak-fix programs cut consumption, yet they demand instrumentation and staff hours that smaller plants often lack. Government studies in Australia report average leakage at 30%, confirming a global inefficiency pattern. While IIoT sensors promise automated leak tracking, initial hardware and analytics subscriptions deter price-sensitive operators. The persistence of double-digit electricity inflation in parts of Europe amplifies scrutiny on pneumatic bills and nudges buyers toward alternative actuation modes when duty cycles permit.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of EV Manufacturing Facilities
- IIoT-Enabled Predictive Maintenance Retrofits
- Substitution by Electric Actuators in Precision Tasks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Upswing Valves captured 33.02% of the pneumatic equipment market share in 2025, underscoring their central role in pressure and flow governance inside automated lines. Their dominance persists because every circuit, from pick-and-place robots to bulk conveyors, relies on directional and proportional valves to orchestrate motion sequences. Growth leans toward compact, protocol-agnostic manifolds that shorten installation time and align with smart-factory architectures.
Actuators are accelerating with a 7.46% CAGR, reflecting manufacturers' need for higher payload accuracy and faster cycle rates. Emerson's XV Series pushes 350 NL/min in a slim footprint, allowing designers to shrink cabinets without sacrificing throughput. Air preparation units and precision fittings round out the component mix as clean-air mandates intensify, while sensor accessories flourish thanks to predictive-maintenance adoption. As a result, the pneumatic equipment market continues to migrate from stand-alone parts to fully integrated, data-rich assemblies.
Motion control held 40.02% of 2025 demand across the pneumatic equipment market, reflecting its ubiquity in linear slides, rotary tables, and pressing stations. The segment benefits from pneumatics' favorable power-to-weight ratio and millisecond response, assets prized on high-speed assembly lines. Emphasis is now on feedback-ready cylinders that feed stroke data to MES platforms for traceability.
Material handling posts the swiftest 7.95% CAGR as e-commerce logistics fuels automated sortation centers. SMC's RMH grippers, certified for cobot collaboration, illustrate how soft-touch gripping opens new SKU handling capabilities. Fluid control retains a niche in process industries, while vacuum generation expands in semiconductor wafer transport. Convergence is evident: advanced manifolds are combining positioning, gripping, and vacuum logic in one node, fortifying supplier stickiness in the pneumatic equipment market.
Complete Report Scope:
- By Component
- Actuators
- Valves
- Air Preparation Units (FRLs)
- Fittings and Tubing
- Air Compressors
- Vacuum Generators
- Accessories
- By Function
- Motion Control
- Fluid Control
- Material Handling
- Vacuum Creation
- Power Generation / Air Supply
- By End-user Industry
- Automotive
- Food and Beverage Processing and Packaging
- Aerospace and Defense
- Life Sciences (Pharma and Medical Devices)
- Electronics and Semiconductor
- Chemical and Petrochemical
- Packaging Machinery
- Other End-user Industries
- By Pressure Range
- Low Pressure (less than 7 bar)
- Medium Pressure (7 - 15 bar)
- High Pressure (above 15 bar)
- By Geography
- North America
- United States
- Canada
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- ASEAN-5
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 34.21% of global 2025 revenue owing to mature aerospace, pharmaceutical, and automotive sectors that demand high-specification solutions. Siemens' USD 10 billion commitment to new Texas and California plants illustrates the region's ongoing reshoring trend, which lifts component orders for motion, valve, and compressor packages. Imminent DOE compressor rules are sparking retrofit waves that stabilize equipment replacement cycles.
Asia Pacific posts the steepest 7.66% CAGR and is set to narrow the gap by 2031 as China, India, and ASEAN states erect new fabs and battery plants. Atlas Copco's USD 46.5 million purchase of Korea-based Kyungwon Machinery signals strategic moves to localize supply and meet skyrocketing regional demand. Government incentives for semiconductor self-reliance in India and Vietnam add fresh pull for ultra-clean pneumatics.
Europe maintains a solid share, buoyed by stringent energy and sustainability directives. Bosch Rexroth's EUR 160 million plant in Mexico underscores European OEMs' split-market strategy: retain R&D at home while building cost-effective capacity near the U.S. customer base. Smaller but rising opportunities in South America and the Middle East hinge on petrochemical diversification projects that require rugged high-pressure pneumatic arrays, adding incremental volume to the pneumatic equipment market.
- Festo SE and Co. KG
- Emerson Electric Co.
- SMC Corporation
- Parker-Hannifin Corporation
- Siemens AG
- Ingersoll Rand Inc.
- Atlas Copco AB
- Bosch Rexroth AG
- Norgren Ltd. (IMI plc)
- Airtac International Group
- CKD Corporation
- Camozzi Automation S.p.A.
- Danfoss A/S
- Honeywell International Inc.
- Eaton Corporation plc
- ROSS Operating Valve Co.
- Bimba Manufacturing LLC (IMI)
- Janatics India Pvt Ltd
- Chicago Pneumatic Tool Co. LLC
- Koki Holdings Co., Ltd.
- Yamaha Motor Co., Ltd. (Robotics)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing automation across industries
- 4.2.2 Demand for energy-efficient compressed-air systems
- 4.2.3 Rapid growth of hygienic FandB processing lines
- 4.2.4 Expansion of EV manufacturing facilities
- 4.2.5 Micro-fluidic assembly demand for micro-actuators
- 4.2.6 IIoT-enabled predictive maintenance retrofits
- 4.3 Market Restraints
- 4.3.1 High lifetime maintenance and energy costs
- 4.3.2 Substitution by electric actuators in precision tasks
- 4.3.3 ESG-driven penalties on compressed-air leakage
- 4.3.4 Shortage of ultra-clean compressed air for semicon fabs
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Macroeconomic Impact Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Actuators
- 5.1.2 Valves
- 5.1.3 Air Preparation Units (FRLs)
- 5.1.4 Fittings and Tubing
- 5.1.5 Air Compressors
- 5.1.6 Vacuum Generators
- 5.1.7 Accessories
- 5.2 By Function
- 5.2.1 Motion Control
- 5.2.2 Fluid Control
- 5.2.3 Material Handling
- 5.2.4 Vacuum Creation
- 5.2.5 Power Generation / Air Supply
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Food and Beverage Processing and Packaging
- 5.3.3 Aerospace and Defense
- 5.3.4 Life Sciences (Pharma and Medical Devices)
- 5.3.5 Electronics and Semiconductor
- 5.3.6 Chemical and Petrochemical
- 5.3.7 Packaging Machinery
- 5.3.8 Other End-user Industries
- 5.4 By Pressure Range
- 5.4.1 Low Pressure (less than 7 bar)
- 5.4.2 Medium Pressure (7 - 15 bar)
- 5.4.3 High Pressure (above 15 bar)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN-5
- 5.5.4.6 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Festo SE and Co. KG
- 6.4.2 Emerson Electric Co.
- 6.4.3 SMC Corporation
- 6.4.4 Parker-Hannifin Corporation
- 6.4.5 Siemens AG
- 6.4.6 Ingersoll Rand Inc.
- 6.4.7 Atlas Copco AB
- 6.4.8 Bosch Rexroth AG
- 6.4.9 Norgren Ltd. (IMI plc)
- 6.4.10 Airtac International Group
- 6.4.11 CKD Corporation
- 6.4.12 Camozzi Automation S.p.A.
- 6.4.13 Danfoss A/S
- 6.4.14 Honeywell International Inc.
- 6.4.15 Eaton Corporation plc
- 6.4.16 ROSS Operating Valve Co.
- 6.4.17 Bimba Manufacturing LLC (IMI)
- 6.4.18 Janatics India Pvt Ltd
- 6.4.19 Chicago Pneumatic Tool Co. LLC
- 6.4.20 Koki Holdings Co., Ltd.
- 6.4.21 Yamaha Motor Co., Ltd. (Robotics)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


