|
시장보고서
상품코드
2123769
혐기성 접착제 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Anaerobic Adhesives - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
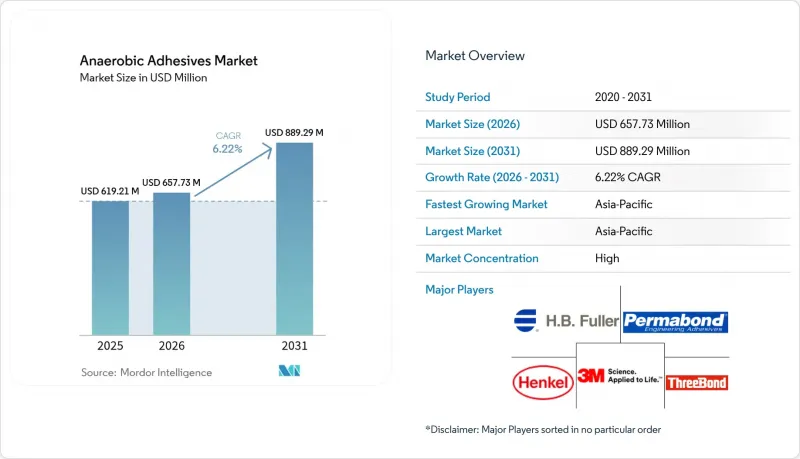
에 의하면, 혐기성 접착제 시장 규모는 2025년에 6억 1,921만 달러로 평가되었고 2026년 6억 5,773만 달러에서 2031년까지 8억 8,929만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.22%를 나타낼 전망입니다.
본 보고서에서는 업계를 제품 유형(나사 잠금제, 나사용 실란트 등), 기판(금속, 플라스틱·복합재료, 기타), 최종 이용 산업(자동차 및 운송, 전기 및 전자, 기타) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류하고 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 혐기성 접착제 시장 동향 및 인사이트
중국, 인도, 멕시코의 자동차 생산 회복
2024년에는 전기차(EV) 생산 대수가 급증하여, 중국은 EV 생산 점유율에서 35%를 넘어섰습니다. 배터리 팩과 구동 모터에는 격렬한 열 사이클과 진동을 견딜 수 있는 혐기성 스레드 락제가 채택되고 있습니다. 모듈식 차량 플랫폼에서는 균일한 클램핑 하중의 필요성이 높아지고 있으며, 화학계 패스너는 대규모 생산에서도 필요한 동심도를 확보합니다. 헨켈(Henkel)에 따르면, 아시아의 신형 전기차 설계 중 60% 이상에서 자동차 등급의 혐기성 접착제가 사양으로 채택되고 있으며, 이는 차세대 구동계에서 화학계 잠금제가 필수적임을 입증합니다. 이러한 요인들이 향후 수년에 걸쳐 수요의 급증세를 뒷받침하며, 혐기성 접착제 시장에서 아시아태평양의 주도적 입지를 공고히 하고 있습니다.
소비자용 및 자동차용 전자기기의 급속한 소형화
휴대용 기기 및 차량용 컨트롤러의 평균 나사 직경은 계속해서 줄어들고 있으며, 각 제조업체는 과도한 압출을 일으키지 않으면서 미세한 나사산에 침투하는 저점도의 모세관 현상을 이용한 나사 잠금제의 채택을 피할 수 없게 되었습니다. 현대 승용차에는 약 3,000개의 전자 하위 어셈블리가 탑재되어 있으며, 각각은 진동에 의한 풀림의 영향을 받기 쉬운 상태입니다. 제어된 초기 탈착 강도를 갖춘 전용 설계의 혐기성 등급은 고밀도 기판을 보호하면서 정비성을 유지합니다. 각 공급업체들은 마이크로 디스펜스 포장 및 정밀 도포 장치를 시장에 출시함으로써 이러한 수요를 활용하고 있으며, 혐기성 접착제 시장 전체의 수탁 제조 라인에서의 채택을 가속화하고 있습니다.
원자재 가격 변동
메타크릴레이트 모노머 가격의 빈번한 변동은 특히 헤지 능력이 없는 지역의 배합 제조업체에서 매출 총이익률을 압박하고 있습니다. 아시아 주요 화학 산업단지의 생산 중단은 공급망 리스크를 높이고, 혐기성 접착제 시장 전체에 재고 과잉 축적을 초래하고 있습니다. 대기업들은 전단 강도를 유지하면서 원가 변동을 억제하는 대체 원료 배합으로 이에 대응하고 있으며, 이를 통해 중소 경쟁사들에 비해 가격 결정력을 확보하고 있습니다.
부문 분석
2025년, 스레드 락제는 매출의 47.20%를 차지하며, 기계적 장치보다 화학적 잠금 방식이 정착되었음을 반영하고 있습니다. 진동 상태에서도 클램프 하중을 유지하는 독보적인 능력 덕분에 구동계, 중장비, 정밀 기기 조립에 있어 여전히 필수적인 존재로 자리 잡고 있습니다. 현재 스테인리스 스틸, 고온 영역, 마이크로 나사를 대상으로 한 특수 제품이 등장하며 대상 시장이 확대되고 있습니다. 나사용 실란트는 시장 규모는 작지만, 유체 처리 시스템에서 밀봉과 체결을 동시에 수행해야 할 필요성이 높아짐에 따라 연평균 성장률(CAGR) 6.85%로 다른 모든 제품을 능가하는 성장이 예상됩니다. 이러한 이중 기능성 덕분에 플랜트 엔지니어에게는 매력적인 총소유비용(TCO)상의 이점이 제공됩니다.
각 제조업체는 혐기성 경화와 UV 경화를 결합한 듀얼 경화 시스템에 대한 연구를 강화하고 있으며, 수 초 만에 고정할 수 있으면서도 밀폐된 금속 접합부에서 혐기성 경화를 통한 최종 강도를 실현하고 있습니다. 이러한 혁신 기술로 인해 타크트 타임이 단축되어 대량 생산되는 전자기기 제조를 뒷받침하고 있습니다. 고정용 화합물은 기존의 베어링 접착의 범위를 넘어 풍력 터빈 조립으로 용도를 확대하고 있으며, 새로운 수익원을 창출하고 있습니다. 개스킷용 실란트는 틈새 시장이지만, 고압 하에서 기존의 엘라스토머 개스킷이 기능 장애를 일으키는 강성 플랜지의 문제를 해결하여 혐기성 접착제 시장의 추가적인 다각화를 촉진하고 있습니다.
지역별 분석
2025년에는 아시아태평양이 소비량의 47.60%를 차지하며 1위를 유지했습니다. 이러한 우위는 중국의 전기차 붐과 인도의 전자기기 산업 발전에 힘입은 것입니다. 중국의 OEM 기업들은 신규 전기차 플랫폼의 60% 이상에 혐기성 나사 고정제를 채택하고 있으며, 정책적 인센티브가 현지 조달을 가속화하여 지역 내 지출을 확대되고 있습니다. 인도의 ‘메이크 인 인디아(Make in India)’ 이니셔티브는 다국적 스마트폰 및 자동차 부품 공급업체들을 유치하고 있으며, 이들 기업은 접착제 소모품과 함께 디스펜싱 라인을 수입함으로써 남아시아의 혐기성 접착제 시장 규모를 확대되고 있습니다. 성숙한 일본 및 한국의 공장은 최고 수준의 사양 기준을 유지하고 있어 고품질 내열 등급에 대한 수요를 촉진하고 있습니다.
북미는 인증된 배합이 필요한 항공우주, 방위, 풍력 발전 프로젝트에서 여전히 매우 중요한 시장입니다. 미국에서는 저아웃가스 등급이 NASA 및 ESA의 사양을 충족하는 위성 하드웨어 분야에서 높은 수익률의 매출을 이끌고 있습니다. 멕시코에서 확장되고 있는 자동차 조립 회랑에는 미리 도포된 나사 잠금 필름을 적용하는 1차 패스너 코팅 기업들이 진출하여 국경을 넘는 거래량을 끌어올리고 있습니다. 캐나다는 규모는 작지만, 대서양 횡단 회랑 전역의 풍력 터빈 개조를 위해 리테이닝 컴파운드를 대량으로 구매하고 있습니다.
유럽은 혁신의 리더로서의 입지를 확고히 하고 있습니다. 엄격한 REACH 규제로 인해 프탈레이트 에스테르나 TCE를 포함하지 않는 라벨 프리 화학제품에 대한 투자가 촉진되고 있습니다. 독일의 고급 자동차 제조업체들은 무용제형 나사 고정제를 공동 개발하고 있으며, 이것이 혐기성 접착제 시장 전망 수익 기반이 되고 있습니다. 프랑스와 영국에서는 육상 풍력 발전 설비에 예측 유지보수가 도입되어 센서 어레이와 고신뢰성 고정용 화합물이 결합되어 있습니다. 남미, 중동 및 아프리카에서는 아직 시장이 발전 단계에 있지만, 광업 및 에너지 인프라 분야에서 꾸준히 도입이 진행되고 있으며, 현지 기술력과 규제가 성숙해지면 장기적인 가능성이 시사되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the anaerobic adhesives market size was valued at USD 619.21 million in 2025 and estimated to grow from USD 657.73 million in 2026 to reach USD 889.29 million by 2031, at a CAGR of 6.22% during the forecast period (2026-2031).
This report Segments the Industry by Product Type (Threadlockers, Thread Sealants, and More), Substrate Material (Metal, Plastics and Composites, and Others), End-Use Industry (Automotive and Transportation, Electrical and Electronics, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Anaerobic Adhesives Market Trends and Insights
Recovering automotive production in China, India and Mexico
Electric-vehicle output rose sharply in 2024, with China surpassing 35% EV production share. Battery packs and traction motors now rely on anaerobic threadlockers that withstand intense thermal cycling and vibration. Modular vehicle platforms magnify the need for uniform clamp load, and chemical fasteners provide the required concentricity at scale. Henkel notes specification of automotive-grade anaerobic formulations in more than 60% of new EV designs in Asia, underscoring the indispensability of chemical locking for next-generation drivetrains. These factors anchor a multi-year demand surge and reinforce the Asia-Pacific leadership in the anaerobic adhesives market.
Rapid miniaturisation in consumer and automotive electronics
Average thread diameters in handheld gadgets and in-vehicle controllers continue to shrink, compelling manufacturers to adopt low-viscosity, capillary threadlockers that flow into micro-threads without excess squeeze-out. A modern passenger car now contains about 3,000 electronic sub-assemblies, each vulnerable to vibration-induced loosening. Purpose-built anaerobic grades with controlled breakaway strength preserve serviceability while safeguarding high-density boards. Suppliers capitalise by launching micro-dispense packaging and precision dosing equipment, speeding adoption across contract manufacturing lines throughout the anaerobic adhesives market.
Volatile feedstock prices
Frequent swings in methacrylate-monomer costs squeeze gross margins, particularly for regional formulators lacking hedging capability. Production disruptions in key Asian chemical parks raise supply-chain risk and prompt inventory inflation across the anaerobic adhesives market. Large players counter with alternative raw-material recipes that hold shear strength while dampening cost volatility, giving them pricing leverage over smaller rivals.
Other drivers and restraints analyzed in the detailed report include:
- Accelerating shift toward predictive maintenance in wind turbines
- Growing OEM preference for lightweight, vibration-resistant fastening in e-mobility
- Regulatory pressure to reduce hazardous stabilisers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Threadlockers generated 47.20% revenue in 2025, reflecting entrenched preference for chemical locking over mechanical devices. Their unmatched ability to maintain clamp load under vibration keeps them integral to drivetrain, heavy-machinery, and precision instrumentation assembly. Specialty variants now target stainless steel, high-temperature zones, and micro-threads, widening the addressable pool. Thread sealants, although smaller, will outpace all other products with a 6.85% CAGR as fluid-handling systems demand simultaneous sealing and fastening. This double-functionality gives plant engineers a compelling cost-of-ownership advantage.
Manufacturers intensify research and devlopment on dual-cure systems blending anaerobic and UV triggers, enabling fixture within seconds yet delivering final anaerobic strength in enclosed metal joints. These innovations shorten takt times and support high-volume electronics production. Retaining compounds are scaling beyond traditional bearing bonds into wind-turbine assemblies, creating fresh revenue layers. Gasket sealants, though niche, solve rigid-flange challenges where legacy elastomer gaskets fail under high pressure, further diversifying the anaerobic adhesives market.
Complete Report Scope:
- By Product Type
- Threadlockers
- Thread Sealants
- Retaining Compounds
- Gasket Sealants
- By Substrate Material
- Metal
- Plastics and Composites
- Others (Ceramic, Glass)
- By End-Use Industry
- Automotive and Transportation
- Electrical and Electronics
- Industrial
- Building and Construction
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific led with 47.60% consumption in 2025, a dominance underpinned by China's EV surge and India's electronics push. Chinese OEMs embed anaerobic threadlockers in over 60% of new EV platforms, and policy incentives accelerate local sourcing, deepening regional expenditure. India's Make-in-India initiative draws multinational smartphone and auto suppliers that import dispensing lines alongside adhesive consumables, advancing the anaerobic adhesives market size for South Asia. Mature Japanese and South Korean factories maintain top-tier specification standards, spurring demand for premium high-temperature grades.
North America remains pivotal for aerospace, defense, and wind-energy projects that require certified formulations. The United States fuels high-margin sales in satellite hardware, where low-outgassing grades meet NASA and ESA specifications. Mexico's expanding car-assembly corridor attracts Tier-1 fastener coaters applying pre-applied threadlock films, lifting cross-border volumes. Canada, though smaller, buys large packages of retaining compounds for wind-turbine refurbishments across the Atlantic corridor.
Europe ranks as an innovation leader. Stringent REACH rules motivate investment in label-free chemistries that shun phthalates and TCE. Germany's premium carmakers co-develop solvent-free threadlockers, anchoring future revenue for the anaerobic adhesives market. France and the United Kingdom deploy predictive maintenance in onshore wind fleets, pairing sensor arrays with high-reliability retaining compounds. South America and Middle East and Africa remain nascent but see steady uptake in mining and energy infrastructure, signalling long-run potential once local skills and regulations mature.
- 3M
- Anabond
- Chemence/Krylex
- Dymax
- H.B. Fuller Company
- Henkel AG & Co. KGaA
- Hernon Manufacturing
- Hi Bond Chemicals
- Kisling AG
- Loxeal S.r.l.
- Metlok Private Limited
- Novachem Corporation ltd
- Panacol-Elosol GmbH
- Permabond
- ThreeBond Holdings Co., Ltd.
- TOAGOSEI CO.,LTD.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Recovering Automotive Production in China, India and Mexico
- 4.2.2 Rapid Miniaturisation in Consumer and Automotive Electronics Raising Demand for Threadlockers
- 4.2.3 Accelerating Shift Toward Predictive Maintenance in Wind Turbines Boosting Retaining Compounds
- 4.2.4 Growing OEM Preference for Lightweight, Vibration-Resistant Fastening Solutions in E-Mobility
- 4.2.5 Increased adoption in aerospace for critical, high-stress joints.
- 4.3 Market Restraints
- 4.3.1 Volatile Feedstock Prices
- 4.3.2 Regulatory Pressure to Reduce Hazardous Stabilisers in Formulations (EU REACH, TSCA)
- 4.3.3 Skilled-Labour Gap in Emerging Economies for Precision Assembly Applications
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Threadlockers
- 5.1.2 Thread Sealants
- 5.1.3 Retaining Compounds
- 5.1.4 Gasket Sealants
- 5.2 By Substrate Material
- 5.2.1 Metal
- 5.2.2 Plastics and Composites
- 5.2.3 Others (Ceramic, Glass)
- 5.3 By End-Use Industry
- 5.3.1 Automotive and Transportation
- 5.3.2 Electrical and Electronics
- 5.3.3 Industrial
- 5.3.4 Building and Construction
- 5.3.5 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 3M
- 6.4.2 Anabond
- 6.4.3 Chemence/Krylex
- 6.4.4 Dymax
- 6.4.5 H.B. Fuller Company
- 6.4.6 Henkel AG & Co. KGaA
- 6.4.7 Hernon Manufacturing
- 6.4.8 Hi Bond Chemicals
- 6.4.9 Kisling AG
- 6.4.10 Loxeal S.r.l.
- 6.4.11 Metlok Private Limited
- 6.4.12 Novachem Corporation ltd
- 6.4.13 Panacol-Elosol GmbH
- 6.4.14 Permabond
- 6.4.15 ThreeBond Holdings Co., Ltd.
- 6.4.16 TOAGOSEI CO.,LTD.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Increasing Research And Development and Usage of Bio-based Raw Materials