|
시장보고서
상품코드
2123773
함침 수지 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Impregnating Resins - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
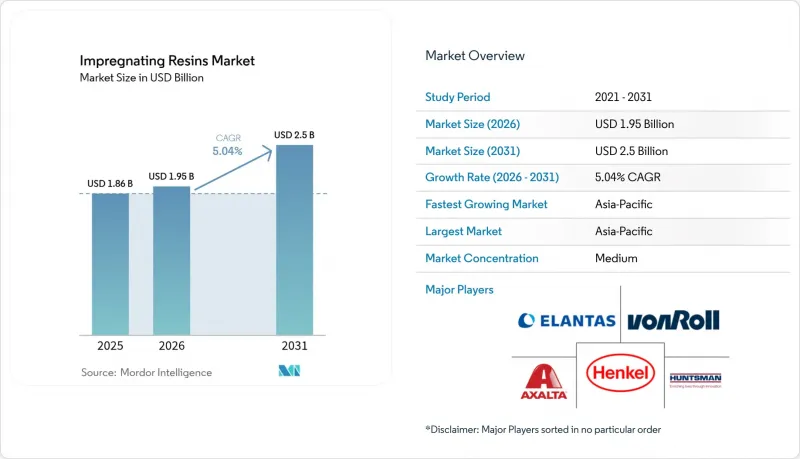
함침 수지 시장 규모는 2025년 18억 6,000만 달러에서 2026년에는 19억 5,000만 달러로 확대되어 2031년까지 25억 달러에 이를 것으로 예측되며, 2026년부터 2031년까지 CAGR 5.04%로 성장할 전망입니다.
본 보고서는 기술별(무용제 수지 및 용제계 수지), 수지 유형별(에폭시, 폴리에스터, 폴리에스터이미드, 기타 수지),용도별(모터 및 발전기, 가전제품, 변압기 등), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 함침 수지 시장 동향 및 인사이트
고효율 전기 모터에 대한 수요 급증
최저 에너지 성능 기준의 상향 조정으로 인해 허용되는 모터의 손실이 줄어들고 있으며, 각 OEM 업체들은 부분 방전의 원인이 되는 공극을 제거하기 위해 VPI(바인더 충전) 기술을 도입할 수밖에 없습니다. 유럽의 에코디자인 지침에서는 0.75kW 이상의 모터에 대해 IE3 효율을 요구하고 있는 반면, 중국의 GB 18613-2020은 IEC 60034-30-1의 효율 등급을 준수하고 있습니다. 70%를 초과하는 슬롯 충진율과 집중된 영구 자석의 핫스팟으로 인해 수지의 성능은 180°C의 유리 전이 온도로 상승하고 있습니다. IEC 60034-18-41의 부분 방전 시험 준수를 위해서는 VPI가 전제조건으로 포함되어 있으며, 전 세계 모터가 IE4 및 IE5로 전환됨에 따라 수지에 대한 장기적인 수요가 확고해지고 있습니다.
OEM의 무용제 함침 공정으로의 전환
미국 내 신규 도장 시설의 금속 HAP 상한치(건조 표준 입방피트당 0.0079 그레인)로 인해, 열산화 장치와 병용하지 않는 한 용제계 바니시는 경제적으로 부적합합니다. 유럽의 산업 배출 지침과 중국의 ‘청천 행동 계획’도 이러한 상한치를 반영하고 있습니다. 새로운 무용제 화학제품을 통해 자동 트리클 함침 라인의 경화 주기가 6시간에서 90분 미만으로 단축됩니다. Wacker Chemie사의 SILRES H62 C는 실온에서 24시간 이내에 경화되어 소성 후 오븐이 필요 없으며, 공장의 에너지 사용량을 약 40% 절감합니다.
VOC 및 HAPS 규제 강화
갱신된 미국 환경보호청(EPA) 및 EU의 배출 기준을 준수하기 위해 기존 공장들은 설비당 0.8-150만 달러의 비용이 드는 산화 장치를 설치해야만 하며, 이는 수익성을 압박하고 확장 계획을 지연시키고 있습니다. 사내에 배합 기술 전문 지식이 없는 소규모 모터 제조업체는 무용제 시스템으로 전환하는 데 막대한 검증 비용이 소요되기 때문에 많은 경우 단가를 상승시키는 외부 함침 위탁에 의존할 수밖에 없습니다. 유럽이 중국산 에폭시 수지 수입에 대해 최대 40.8%의 반덤핑 관세를 부과하고 있는 점도 원자재 가격을 더욱 상승시켜, 지역 OEM 제조업체들의 상황을 더욱 복잡하게 만들고 있습니다.
부문 분석
2025년, 무용제 수지는 함침 수지 시장의 64.23% 점유율을 차지하며, 2031년까지 연평균 5.15%의 성장이 예상됩니다. 발열성 경화 특성으로 인해 용제 증발이 제거되고 사이클 시간이 단축될 뿐만 아니라, 40 CFR Part 63, Subpart HHHHH에서 의무화하고 있는 수백만 달러 규모의 열산화 장치 설치를 피할 수 있습니다. 기존의 소성·경화 라인에 비해 최대 40%의 에너지 절감 효과를 얻을 수 있으므로, 전기 요금이 비교적 저렴한 지역에서도 무용제 시스템은 매력적인 선택지가 되고 있습니다. 무용제 화학 기술과 자동 권선 처리를 결합한 트리클 함침기는 대형 모터 OEM에서 수탁 제조업체로 보급이 확대되고 있으며, 택트 타임을 90분 미만으로 단축하고 있습니다.
용제계 바니시는 배출 규제의 시행이 미흡한 개조 라인이나 신흥 시장에서는 여전히 사용되고 있습니다. 대부분의 경우, 이미 수년 전에 감가상각이 완료된 구형 탱크나 오븐이 도입되어 있어 운영 예산 부담이 경감되고 있습니다. 그러나 수입되는 대체 용매에 대한 세관 검사가 엄격해지고 세금 부담이 증가함에 따라, 각 컨버터 업체들은 계획된 모터 모델 변경에 맞추어 2027년부터 2029년까지 무용제화로의 업그레이드를 위한 설비 투자 예산을 편성하고 있습니다.
지역별 분석
아시아태평양은 2025년 함침 수지 시장 점유율의 41.24%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 5.14%로 성장할 전망입니다. 중국의 ‘듀얼 크레딧(Dual Credit)’ 정책에 따라 2024년에는 1,020만 대의 신에너지차(NEV)가 생산될 예정이며, 2035년까지 NEV 판매 비중을 50%로 높이는 것을 목표로 하고 있어, 이것이 대규모 구동 모터 수요의 기반이 되고 있습니다. 인도의 생산 연계형 인센티브 제도에서는 전자 분야에 23억 달러, 반도체 팹에 100억 달러가 배정되어, 폴리에스테르이미드 및 에폭시 등급의 국내 소비를 촉진하고 있습니다. 일본의 보조금 프로그램은 팹 건설 비용의 최대 50%를 지원하며, 첨단 패키징에 대응하는 저염화물 에폭시 언더필을 위한 국내 공급망을 구축하고 있습니다. 한국의 반도체 제조업체들은 시스템 인 패키지(SiP) 모듈용 속경화형 에폭시의 표준화를 추진하고 있는 반면, 태국과 베트남은 계약 함침 업체를 유치하기 위해 수년에 걸친 면세 조치를 제공하며 지역 간 생산 능력의 균형을 맞추고 있습니다.
북미에서는 ‘인플레이션 억제법’에 따라 3,690억 달러 규모의 청정 에너지 장려책이 활용되고 있으며, 이 법에서는 소비자 대상 세액 공제가 국내 조달 비율 기준과 연계되어 있습니다. 각 자동차 제조업체들은 미시간주, 켄튀르키예주, 테네시주의 트랙션 모터 조립 라인을 위해 수백억 규모의 설비 투자를 발표했으며, 모두 미국 환경보호청(EPA)의 유해 대기 오염 물질(HAP) 상한 기준을 충족하는 무용제 에폭시 수지 배합을 지정하고 있습니다. 캐나다의 ‘전략적 혁신 기금’과 멕시코로의 니어쇼어링을 통한 자금 유입으로, USMCA(미국·멕시코·캐나다 협정)의 지역 부가가치율 75% 규정에 따라 수지를 지역 내에서 조달하는 체제가 마련되었습니다.
유럽에서는 ‘그린 딜’의 2035년 제로 배출 목표와 유로 7 기준이 지침이 되고 있으며, 독일, 프랑스, 이탈리아에서 클래스 H 트랙션 모터용 절연재의 도입이 가속화되고 있습니다. 북해 및 발트해의 해상 풍력 발전소 건설 확대에 따라, 15MW 발전기용 클래스 C 에폭시 수지의 채택이 진행되고 있습니다. 아시아산 에폭시 수지 수입에 대한 반덤핑 관세로 인해, 국내 배합 제조업체에게 시장 점유율 확대의 기회가 생기고 있습니다. 다만, 최근 공장 폐쇄로 인해 단기적으로는 무용제 수지공급이 제한되고 있습니다. 동유럽 및 러시아에서는 지정학적 역풍이 있음에도 불구하고, 철도용 및 유전용 모터용 폴리에스터 수지 수요가 유지되고 있습니다.
남미 성장의 중심은 플렉스 연료 하이브리드차로의 전환이 진행 중인 브라질의 자동차 생산 대수 230만 대입니다. 칠레의 전기화가 진행되는 구리 광산과 콜롬비아의 재생에너지 입찰로 인해, 대형 발전기용 클래스 H 요건이 도입되고 있습니다. 중동 및 아프리카에서는 사우디아라비아의 NEOM이나 남아프리카공화국의 송전망 현대화와 같은 메가 프로젝트를 통해 수요가 서서히 증가하고 있지만, 환율 변동이 특수 수지 수입의 수익성에 영향을 미치고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the impregnating resins market size is expected to increase from USD 1.86 billion in 2025 to USD 1.95 billion in 2026 and reach USD 2.5 billion by 2031, growing at a CAGR of 5.04% over 2026-2031.
This report is Segmented by Technology (Solventless Resins and Solvent-Based Resins), Resin Type (Epoxy, Polyester, Polyester-Imide, and Other Resin Types), Application (Motors and Generators, Home Appliances, Transformers, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Impregnating Resins Market Trends and Insights
Surging Demand for High-Efficiency Electric Motors
Escalating minimum energy-performance standards are shrinking permissible motor losses and forcing OEMs to adopt VPI to eliminate voids that spark partial discharge. The European Ecodesign Directive requires IE3 efficiency for >=0.75 kW motors, while China's GB 18613-2020 is aligned with IEC 60034-30-1 efficiency classes. Slot-fill factors above 70% and concentrated permanent-magnet hot spots are pushing resin performance toward glass-transition temperatures of 180 °C. Compliance with IEC 60034-18-41 partial-discharge testing embeds VPI as a prerequisite, locking in long-term resin consumption as global motor fleets shift to IE4 and IE5.
OEM Shift toward Solvent-Free Impregnation Processes
Metal HAP ceilings of 0.0079 grains per dry standard cubic foot for new U.S. coating facilities make solvent-based varnishes uneconomical unless paired with thermal oxidizers. Europe's Industrial Emissions Directive and China's Blue-Sky Action Plan mirror these caps. New solventless chemistries cut cure cycles from six hours to under ninety minutes on automated trickle-impregnation lines. Wacker Chemie's SILRES H62 C cures at room temperature within twenty-four hours, removes post-bake ovens, and slashes plant energy use by roughly 40%.
VOC and HAPS Regulatory Tightening
Compliance with updated U.S. EPA and EU emission standards obliges legacy plants to install oxidizers that cost USD 0.8-1.5 million each, squeezing margins and delaying expansions. Small motor shops lacking in-house formulation expertise face high validation costs to switch to solventless systems, often resorting to contract impregnation that inflates unit costs. European anti-dumping duties of up to 40.8% on Chinese epoxy imports further elevate raw-material prices, adding complexity for regional OEMs.
Other drivers and restraints analyzed in the detailed report include:
- Grid-Scale Wind-Turbine Installation Growth
- EV Traction-Motor Production Acceleration
- Price Volatility of Bisphenol-A and Styrene Feedstocks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solventless resins captured 64.23% of the impregnating resins market share in 2025 and are forecast to grow at 5.15% through 2031. Their exothermic cure eliminates solvent evaporation, shortens cycle time, and bypasses multi-million-dollar thermal oxidizers mandated under 40 CFR Part 63, Subpart HHHHH. Energy savings reach 40% compared with conventional bake-and-cure lines, making solventless systems attractive even in geographies with modest electricity tariffs. Trickle-impregnation machines that marry solventless chemistry with automated winding handling are spreading from large motor OEMs to contract shops, compressing takt times to under ninety minutes.
Solvent-based varnishes persist in retrofit lines and developing markets where emission enforcement is patchy. An installed base of legacy tanks and ovens, often amortized years ago, cushions operating budgets. Yet, as imported replacement solvents face tighter customs checks and rising taxes, converters are budgeting capex for solventless upgrades in the 2027-2029 window, aligning with planned motor model changes.
Complete Report Scope:
- By Technology
- Solventless Resins
- Solvent-based Resins
- By Resin Type
- Epoxy
- Polyester
- Polyester-imide
- Other Resin Types (Polyurethane, silicone, etc.)
- By Application
- Motors and Generators
- Home Appliances
- Transformers
- Electrical and Electronic Components
- Automotive Components
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordic Countries
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- South Africa
- Nigeria
- Egypt
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 41.24% impregnating resins market share in 2025 and is set to grow at a 5.14% CAGR through 2031. China's dual-credit policy yielded 10.2 million new-energy vehicles in 2024 and targets a 50% NEV sales mix by 2035, anchoring large-scale traction-motor demand. India's Production-Linked Incentive schemes earmark USD 2.3 billion for electronics and USD 10 billion for semiconductor fabs, catalyzing local consumption of polyester-imide and epoxy grades. Japan's subsidy program covers up to 50% of fab construction costs, building a domestic supply chain for low-chloride epoxy underfill compatible with advanced packaging. South Korean chipmakers are standardizing fast-cure epoxy for system-in-package modules, while Thailand and Vietnam offer multi-year tax holidays that attract contract impregnation houses, balancing regional capacity.
North America leverages USD 369 billion in clean-energy incentives under the Inflation Reduction Act, which ties consumer tax credits to domestic content thresholds. Automakers have announced tens of billions in capex for traction-motor assembly lines in Michigan, Kentucky, and Tennessee, all specifying solventless epoxy formulations that satisfy the U.S. EPA's HAP ceiling. Canada's Strategic Innovation Fund and Mexico's near-shoring inflows round out a regional corridor that localizes resin sourcing under USMCA's 75% regional-value rules.
Europe is guided by the Green Deal's 2035 zero-emission target and Euro 7 standards, accelerating Class H traction-motor insulation in Germany, France, and Italy. Offshore wind build-outs in the North Sea and Baltic Sea are driving Class C epoxy adoption for 15 MW generators. Anti-dumping duties on Asian epoxy imports open share for domestic formulators, though recent plant closures constrain near-term solventless supply. Eastern Europe and Russia maintain polyester demand for rail and oil-field motors, despite geopolitical headwinds.
South America's growth centers on Brazil's 2.3 million-unit automotive output, which is pivoting to flex-fuel hybrids. Chile's electrified copper mines and Colombia's renewable auctions are introducing Class H requirements for heavy-duty generators. The Middle East and Africa add incremental demand via megaprojects such as Saudi Arabia's NEOM and South Africa's grid-modernization, though currency volatility impacts import economics for specialty resins.
- 3M
- AEV Group
- Axalta Coating Systems, LLC
- BASF
- Borger GmbH
- Chetak Manufacturing Company
- ALTANA (ELANTAS)
- Henkel AG and Co. KGaA
- Huntsman International LLC
- Momentive
- NIPPON RIKA INDUSTRIES CORPORATION
- Resonac Holdings Corporation
- Von Roll
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Demand for High-Efficiency Electric Motors
- 4.2.2 OEM Shift toward Solvent-Free Impregnation Processes
- 4.2.3 Grid-Scale Wind-Turbine Installation Growth
- 4.2.4 EV Traction-Motor Production Acceleration
- 4.2.5 Miniaturisation of Consumer Electronics
- 4.3 Market Restraints
- 4.3.1 VOC and HAPS Regulatory Tightening
- 4.3.2 Price Volatility of Bisphenol-A and Styrene Feedstocks
- 4.3.3 Capital-Intensive Vacuum-Pressure Equipment
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Technology
- 5.1.1 Solventless Resins
- 5.1.2 Solvent-based Resins
- 5.2 By Resin Type
- 5.2.1 Epoxy
- 5.2.2 Polyester
- 5.2.3 Polyester-imide
- 5.2.4 Other Resin Types (Polyurethane, silicone, etc.)
- 5.3 By Application
- 5.3.1 Motors and Generators
- 5.3.2 Home Appliances
- 5.3.3 Transformers
- 5.3.4 Electrical and Electronic Components
- 5.3.5 Automotive Components
- 5.3.6 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Malaysia
- 5.4.1.6 Thailand
- 5.4.1.7 Indonesia
- 5.4.1.8 Vietnam
- 5.4.1.9 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Nordic Countries
- 5.4.3.7 Russia
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.4.4 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 South Africa
- 5.4.5.5 Nigeria
- 5.4.5.6 Egypt
- 5.4.5.7 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 3M
- 6.4.2 AEV Group
- 6.4.3 Axalta Coating Systems, LLC
- 6.4.4 BASF
- 6.4.5 Borger GmbH
- 6.4.6 Chetak Manufacturing Company
- 6.4.7 ALTANA (ELANTAS)
- 6.4.8 Henkel AG and Co. KGaA
- 6.4.9 Huntsman International LLC
- 6.4.10 Momentive
- 6.4.11 NIPPON RIKA INDUSTRIES CORPORATION
- 6.4.12 Resonac Holdings Corporation
- 6.4.13 Von Roll
- 6.4.14 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment