

|
시장보고서
상품코드
2123791
중재적 종양학 기기 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Interventional Oncology Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
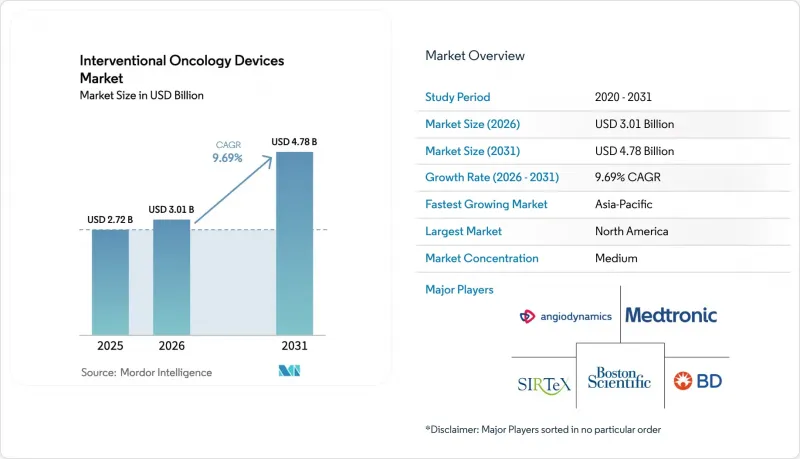
에 의하면, 중재적 종양학 기기 시장 규모는 2025년 27억 2,000만 달러로 평가되었고, 2026년에는 30억 1,000만 달러로 추정되고, 2026-2031년 CAGR 9.69%로 성장을 지속할 전망이며, 2031년에는 47억 8,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품 유형별(절제 기기, 색전 기기 등), 시술 유형별(절제, 색전, 병용 요법), 암 유형별(간암 등), 최종 사용자별(병원, 암 전문 의료 센터 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 중재적 종양학 기기 시장 동향 및 인사이트
암 유병률 증가가 중재적 치료 수요를 견인
2024년 전 세계 신규 암 발병 건수는 2,000만 건에 달했으며, 2020년 대비 15% 증가했습니다. 그중 영상 유도 치료의 주요 대상이 되는 간, 폐, 신장암은 420만 건의 진단을 차지하고 있습니다. 국제원자력기구(IAEA)는 전 세계적으로 1만 2,000대의 선형 가속기가 부족하다고 추산하고 있으며, 이에 따라 종양 전문의들은 대체 수단으로 카테터를 이용한 색전술이나 경피적 절제술에 주목하고 있습니다. 중국의 ‘제14차 5개년 계획’에서는 2027년까지 콘빔 CT를 갖춘 500곳의 암 센터를 설립하기 위해 28억 달러가 배정되었으며, 이에 따라 아시아태평양의 의료기기 출하량의 5분의 1에 가까운 수요가 예상됩니다. 65세 이상 인구가 33%를 차지하는 일본의 인구 구조는 간세포암의 연간 9% 증가와 관련이 있으며, 이 환자군에 대해서는 절제술보다 방사선 색전술을 통한 치료가 점점 더 많이 시행되고 있습니다. 또한, 미국의 대학 병원에서도 외부 방사선 치료 대기자 명단이 보고되고 있으며, 이로 인해 중재적 종양학 클리닉으로의 조기 의뢰가 증가하여 일일 절제술 건수가 18% 증가했습니다.
영상 유도 내비게이션 및 실시간 융합 기술의 발전
AI 내비게이션을 통해 시술 전 계획 수립 시간이 45분에서 12분으로 단축되어, 방사선과 의사는 하루에 4건에서 6건의 사례를 처리할 수 있게 되었습니다. Philips의 ‘LumiGuide’는 사전에 획득한 CT 영상에 실시간 초음파 영상을 중첩시킴으로써 폐 생검 시 바늘 재위치 조정 횟수를 38% 줄였습니다. FDA 승인을 받은 ‘LungVision’은 기관지경 영상과 3D 지도를 결합하여 주변 결절의 절제 시간을 22분 단축하는 동시에 기흉 발생률을 4.5%로 낮춥니다. 매사추세츠 종합병원에서 진행된 Apple Vision Pro의 초기 임상 운영에서는 홀로그래픽을 통해 간 절제 경계가 시야 내에 투영되어, 양성 절제 경계 발생률을 19% 줄였습니다. 내비게이션 기술이 단순한 보조 도구에서 표준 치료에 필수적인 의료기기로 진화하는 가운데, 이러한 혁신 기술이 중재적 종양학 기기 시장을 강화하고 있습니다.
높은 설비 투자 비용이 자원이 제한된 환경에서의 도입을 방해하고 있습니다.
턴키 방식의 중재적 종양학 스위트 가격은 280만 달러로, 이 금액은 인도 공립 병원의 78%, 브라질의 65%에 해당하는 연간 설비 투자 예산을 초과합니다. 마이크로파 발생기만 해도 18만-25만 달러에 판매되고 있으며, 1건당 일회용 소모품 비용은 8,500달러에 달하는데, 이는 인도네시아와 나이지리아의 본인 부담액 중앙값의 4배에 해당합니다. 동남아시아의 리스 이용률은 고작 12%에 그치고 있으며, 서유럽의 41%와 비교하면 기술 보급이 4-6년 뒤처지는 셈입니다. 18%-35%의 수입 관세와 90일의 리드타임이 이용률을 더욱 낮추고 있어, 투자 회수에 필요한 손익분기점인 60%를 밑돌고 있습니다.
부문 분석
색전 요법용 기기는 30일 동안 약물을 방출하는 비드가 간세포암의 종양 제어율을 2배로 높이기 때문에 연평균 성장률(CAGR) 12.29%로 성장하여, 중재적 종양학 기기 시장 전체의 성장률을 상회할 것으로 예측됩니다. 절제 기기는 간 및 폐에서의 적용을 배경으로, 2025년에도 여전히 중재적 종양학 기기 시장의 46.71% 점유율을 차지했습니다. 그러나 2023년 이후 평균 판매 가격은 연평균 8% 하락하고 있습니다. 이는 기존 제조업체보다 마이크로파 발생 장치 가격을 35% 낮게 책정한 저비용 중국계 신규 진출기업의 압박에 기인한 것입니다. 비가역적 전기 천공법은 CPT에 의한 보험 급여가 시작됨에 따라 췌장 적응증 분야에서 보급이 확대되고 있으며, 그 결과 시술당 수익이 77% 증가했습니다.
내비게이션 및 영상 진단 시스템은 독자적인 AI 알고리즘을 통해 계획 시간을 단축하고 수술실의 처리 능력을 향상시켜 42%의 매출총이익률을 실현하고 있으며, 연간 200건 이상의 사례를 다루는 병원에 대해 35만 달러라는 가격 설정을 수용하도록 하는 데 성공했습니다. 부수적인 일회용 제품의 매출은 사례 수에 비례하여 증가하고 있지만, Premier Inc.가 협상한 공동 구매 계약에 따라 두 자릿수의 가격 양보를 할 수밖에 없는 상황입니다. 색전용 마이크로스피어는 고액의 보험 급여가 인정되고 있으며, 이리노테칸을 함유한 비드를 사용함으로써 대장암 전이에서의 객관적 반응률이 일반적인 색전 요법의 53%에 비해 71%로 상승했습니다.
병용 요법은 카테고리 1A 가이드라인 지정을 획득한 생존율 향상이 원동력이 되어 연평균 성장률(CAGR) 13.09%의 궤도에 올라 있습니다. 절제술은 2025년 중재적 종양학 기기 시장 규모의 49.13%를 차지했으나, 북미 및 서유럽에서의 보급률이 정점에 도달함에 따라 성장률은 8.2%로 둔화되고 있습니다. 색전술은 Y-90 기술의 혁신을 활용하여 연평균 성장률(CAGR) 10.1%를 달성하고 있습니다. 선량 측정 기술의 발전으로 종양에 150 그레이의 선량을 조사하면서도 정상 조직에 미치는 영향을 최소화할 수 있게 되었으며, 그 결과 절제 불가능한 간세포암의 생존 기간 중앙값이 10.7개월에서 16.4개월로 연장되었습니다.
화학색전 요법은 동맥 혈류량을 68% 감소시킴으로써 종양에 인접한 혈관의 열 흡수를 줄이고, 절제 마진을 1.2cm 확대합니다. 메드트로닉사의 임피던스 제어에 의한 출력 제어 기술은 탄화나 중첩으로 인한 손상을 줄여, 기존에는 위험이 높았던 부위에서도 이 치료법을 시행할 수 있게 해줍니다. FDA의 ‘획기적 치료법 지정(Breakthrough Designation)’은 임상시험 기간을 단축하고 보험 환급 승인을 가속화함으로써 추가적인 호재로 작용하고 있습니다.
지역별 분석
북미는 2025년 매출의 41.64%를 차지했습니다. 이는 마이크로파 간 절제술의 요금표가 12% 인상되어 1건당 3,847달러가 된 점과, CMS(미국 의료보험센터)의 90일간의 잠정 적용 방침에 힘입은 결과입니다. 미국 내 보급률이 높고, 이미 4,200개의 시술실에 콘빔 CT가 도입되어 있어 성장률은 7.8%로 둔화되고 있습니다. 캐나다에서는 온타리오주와 브리티시컬럼비아주가 Y-90 방사선 색전술을 공적 보험 적용 대상에 추가하여 1만 2,000명의 환자가 혜택을 받음에 따라 성장률이 9.4%로 상승했습니다. 멕시코 시장은 11.2%의 속도로 확대되고 있으며, 2025년에는 1만 8,000명의 미국인 환자가 60% 저렴한 비용과 4주 더 짧은 대기 시간을 위해 국경을 넘어 간 절제술을 받았습니다.
아시아태평양은 연평균 성장률(CAGR) 14.08%를 기록하며 성장의 원동력이 되고 있습니다. 중국은 2024-2025년 47종의 의료기기를 승인하고, 500곳의 암 센터에 28억 달러를 배정했으며, 이는 해당 지역 출하량의 18%를 차지합니다. 일본에서는 고령 인구가 많다는 점을 감안하여, 골전이 치료를 위한 냉동 절제술이 진료보수 기준에 추가되었으며, 1회당 42만 엔(약 3,200달러)으로 책정되었습니다. 인도에서는 ‘아유슈만 바라트’ 보험 제도 하에서 5억 명의 국민에 대한 치료비가 환급되게 되어 16.1%라는 가장 높은 성장률을 기록하고 있습니다.
스칸디나비아 지역에서는 가치 기반 조달 입찰에서 저침습 치료를 우선시함으로써 시장의 일부 침체를 상쇄하고 있습니다. 중동 및 아프리카은 GCC(걸프협력회의) 회원국 국민에게 치료비의 40%를 보조하는 두바이와 리야드의 의료 관광 거점에 힘입어 12.6%의 연평균 성장률(CAGR)을 기록하고 있습니다. 남미는 10.9%의 성장률을 보이고 있으며, 2025년 3월 브라질 국민건강보험제도(SUS)에서 마이크로파 절제술에 대한 보험 적용이 시작된 것이 주요 견인 요인으로 작용하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the interventional oncology devices market size is expected to grow from USD 2.72 billion in 2025 to USD 3.01 billion in 2026 and is forecast to reach USD 4.78 billion by 2031 at 9.69% CAGR over 2026-2031.
This report is Segmented by Product Type (Ablation Devices, Embolization Devices, and More), Procedure Type (Ablation, Embolization, Combination Therapies), Cancer Type (Liver, and More), End User (Hospitals, Cancer Specialty Centers, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Interventional Oncology Devices Market Trends and Insights
Rising Prevalence of Cancer Driving Interventional Demand
Global cancer incidence climbed to 20 million new cases in 2024, a 15% rise over 2020, with liver, lung, and kidney tumors prime targets for image-guided therapy, making up 4.2 million diagnoses.The International Atomic Energy Agency estimates a global deficit of 12,000 linear accelerators, prompting oncologists to turn to catheter-based embolization and percutaneous ablation as capacity substitutes. China's 14th Five-Year Plan allocates USD 2.8 billion to establishing 500 cancer centers equipped with cone-beam CT suites by 2027, creating a pipeline that accounts for nearly one-fifth of the Asia-Pacific device shipments. Japan's demographic profile, with 33% of citizens over 65 years, is linked to a 9% yearly increase in hepatocellular carcinoma, a cohort increasingly treated with radioembolization rather than resection. U.S. academic hospitals also report waitlists for external-beam therapy, prompting earlier referrals to interventional oncology clinics and increasing daily ablation throughput by 18%.
Advances in Image-Guided Navigation and Real-Time Fusion
AI navigation compresses pre-procedure planning from 45 minutes to 12 minutes, enabling radiologists to complete six cases daily instead of four. Philips' LumiGuide overlays real-time ultrasound on pre-acquired CT, cutting needle repositioning by 38% in lung biopsies. FDA-cleared LungVision combines bronchoscopic video with 3D maps, reducing peripheral-nodule ablation time by 22 minutes while lowering pneumothorax rates to 4.5%. Early clinical use of Apple Vision Pro at Massachusetts General Hospital projects holographic liver margins into the field of view, slicing positive margins by 19%. These innovations fortify the interventional oncology devices market as navigation evolves from accessory to standard-of-care capital equipment.
High Capital Costs Limiting Adoption in Resource-Constrained Settings
A turnkey interventional oncology suite costs USD 2.8 million, a figure exceeding the annual capital budgets of 78% of public hospitals in India and 65% in Brazil. Microwave generators alone sell for USD 180,000-USD 250,000, while per-case disposables add USD 8,500-four times the median out-of-pocket expenditure in Indonesia and Nigeria. Leasing penetration in Southeast Asia is only 12%, compared to 41% in Western Europe, which delays diffusion by four to six years. Import tariffs of 18%-35% and 90-day lead times further erode utilization, which falls below the 60% breakeven needed for payback.
Other drivers and restraints analyzed in the detailed report include:
- Growing Shift to Outpatient and Ambulatory Settings
- Expansion of Combination Therapy Protocols
- Lack of Standardized Response Criteria and False-Positive Imaging
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Embolization devices are expected to grow at a 12.29% CAGR, outpacing the interventional oncology devices market, as 30-day drug-eluting beads double tumor control rates in hepatocellular carcinoma. Ablation devices still accounted for a 46.71% share of the interventional oncology devices market in 2025, driven by applications in the liver and lung. Yet, average selling prices have fallen 8% annually since 2023, pressured by low-cost Chinese entrants that price microwave generators 35% below those of incumbents. Irreversible electroporation is gaining traction in pancreatic indications after CPT reimbursement kicked in, resulting in a 77% increase in per-procedure revenue.
Navigation and imaging systems deliver 42% gross margins because proprietary AI algorithms reduce planning time and increase suite throughput, persuading hospitals that perform 200 or more cases annually to accept price tags of USD 350,000. Ancillary disposables mirror case volume but face double-digit price concessions under group-purchasing contracts negotiated by Premier Inc. Embolic microspheres command premium reimbursement, as irinotecan-loaded beads increase the objective response rate in colorectal metastases to 71% compared to 53% for bland embolization.
Combination therapies are on a 13.09% CAGR trajectory, fueled by survival benefits that earned Category 1A guideline status. Ablation held a 49.13% share of the 2025 interventional oncology devices market size, but growth is moderating to 8.2% as penetration plateaus in North America and Western Europe. Embolization procedures leverage Y-90 innovation to achieve a 10.1% CAGR; dosimetry advances now deliver 150 Gray to tumors while sparing parenchyma, thereby extending median survival in unresectable hepatocellular carcinoma from 10.7 to 16.4 months.
Chemoembolization reduces arterial flow by 68%, thereby mitigating the heat sink in vessels adjacent to tumors and enlarging the ablation margins by 1.2 cm. Medtronic's impedance-regulated power control reduces charring and overlap injury, making the regimen feasible in previously risky locations. The FDA breakthrough designation shortens trial timelines and accelerates reimbursement, providing another tailwind.
Complete Report Scope:
- By Product Type
- Ablation Devices
- Thermal Ablation
- Non-thermal Ablation
- Embolization Devices
- Embolic Agents
- Delivery Accessories
- Navigation & Imaging Systems
- Ancillary Disposables
- Ablation Devices
- By Procedure Type
- Ablation
- Embolization
- Combination Therapies
- By Cancer Type
- Liver
- Lung
- Breast
- Kidney
- Prostate
- Bone Metastases
- Pancreatic
- Other Cancers
- By End User
- Hospitals
- Cancer Specialty Centers
- Ambulatory Surgical Settings
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 41.64% of 2025 revenue, supported by a 12% fee-schedule bump on microwave liver ablation to USD 3,847 per case and CMS's 90-day provisional-coverage policy. U.S. penetration is high, 4,200 suites are already equipped with cone-beam CT, so growth slows to 7.8%. Canada's growth rate increased to 9.4% after Ontario and British Columbia added Y-90 radioembolization to public coverage, benefiting 12,000 patients. Mexico's market expands at 11.2% as 18,000 U.S. patients crossed the border for 60% cheaper liver ablation and four-week shorter wait times in 2025.
Asia-Pacific is the growth engine with a 14.08% CAGR. China approved 47 devices for 2024-2025 and earmarked USD 2.8 billion for 500 cancer centers, accounting for 18% of regional shipments. Japan has added cryoablation of bone metastases to its fee schedule at JPY 420,000 (approximately USD 3,200) per procedure, catering to its large elderly population. India grows at the fastest rate of 16.1% under the Ayushman Bharat insurance plan, which now reimburses treatment for 500 million citizens.
Scandinavia offsets some softness by favoring minimally invasive care in value-based procurement tenders. The Middle East & Africa enjoy a 12.6% CAGR, aided by medical tourism hubs in Dubai and Riyadh that subsidize 40% of the costs for GCC nationals. South America advances at 10.9%, led by Brazil's March 2025 reimbursement of microwave ablation under the SUS national health plan.
- AngioDynamics
- Beckton Dickinson
- Boston Scientific
- Cook Group
- Guerbet Group
- HealthTronics
- IceCure Medical
- Johnson & Johnson
- Medtronic
- Merit Medical Systems
- Profound Medical
- Siemens Healthineers
- Sirtex Medical
- Stryker
- Terumo Corp.
- Varian Medical Systems
- Medwaves Inc.
- Mirabilis Medical
- Monteris Medical
- ABK Biomedical Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence of Autoimmune Diseases
- 4.2.2 Advances in Immunoassay & Molecular Diagnostics
- 4.2.3 Growing Awareness & Early-Detection Initiatives
- 4.2.4 Expansion of Automated Multiplex Testing Platforms
- 4.2.5 AI-Enabled Pattern Recognition Reducing Turnaround
- 4.2.6 Commutable Reference Materials Speeding Approvals
- 4.3 Market Restraints
- 4.3.1 High Cost of Advanced Diagnostics in LMICs
- 4.3.2 Lack of Standardized Criteria / False Positives
- 4.3.3 Specialty Reagent Supply-Chain Vulnerabilities
- 4.3.4 Heightened Regulatory Scrutiny of Multiplex Assays
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Product Type
- 5.1.1 Ablation Devices
- 5.1.1.1 Thermal Ablation
- 5.1.1.2 Non-thermal Ablation
- 5.1.2 Embolization Devices
- 5.1.2.1 Embolic Agents
- 5.1.2.2 Delivery Accessories
- 5.1.3 Navigation & Imaging Systems
- 5.1.4 Ancillary Disposables
- 5.1.1 Ablation Devices
- 5.2 By Procedure Type
- 5.2.1 Ablation
- 5.2.2 Embolization
- 5.2.3 Combination Therapies
- 5.3 By Cancer Type
- 5.3.1 Liver
- 5.3.2 Lung
- 5.3.3 Breast
- 5.3.4 Kidney
- 5.3.5 Prostate
- 5.3.6 Bone Metastases
- 5.3.7 Pancreatic
- 5.3.8 Other Cancers
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Cancer Specialty Centers
- 5.4.3 Ambulatory Surgical Settings
- 5.4.4 Other End Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 AngioDynamics
- 6.3.2 Becton, Dickinson & Company
- 6.3.3 Boston Scientific Corporation
- 6.3.4 Cook Medical
- 6.3.5 Guerbet Group
- 6.3.6 HealthTronics Inc.
- 6.3.7 IceCure Medical
- 6.3.8 Johnson & Johnson (Ethicon)
- 6.3.9 Medtronic
- 6.3.10 Merit Medical Systems
- 6.3.11 Profound Medical Corp.
- 6.3.12 Siemens Healthineers
- 6.3.13 Sirtex Medical
- 6.3.14 Stryker Corp.
- 6.3.15 Terumo Corp.
- 6.3.16 Varian Medical Systems
- 6.3.17 Medwaves Inc.
- 6.3.18 Mirabilis Medical
- 6.3.19 Monteris Medical
- 6.3.20 ABK Biomedical Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


