|
시장보고서
상품코드
2123988
알루미늄 뚜껑 및 마개 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Aluminum Caps And Closures - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
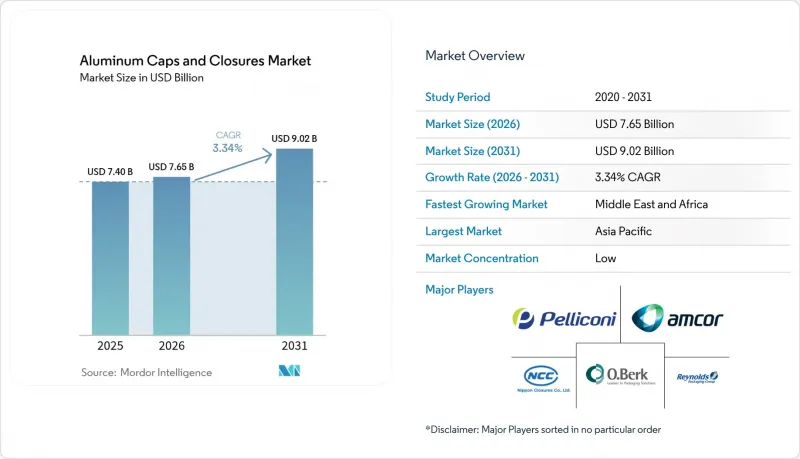
에 의하면, 알루미늄 뚜껑 및 마개 시장 규모는 2025년 74억 달러로 평가되었고, 2026년에는 76억 5,000만 달러로 추정되고, 2026-2031년 CAGR 3.34%로 성장을 지속할 전망이며, 2031년까지 90억 2,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 뚜껑 유형별(스크류 뚜껑, 크라운 코르크, 래그/프레스 트위스트 등), 용도별(음료, 식품, 의약품, 화장품 및 퍼스널케어 등), 목 마감 직경별(20mm 이하, 21-30mm, 기타), 유통 채널별(직접 판매 채널, 간접 판매 채널), 지역별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 알루미늄 뚜껑 및 마개 시장 동향 및 인사이트
북미에서 프리미엄 RTD 칵테일의 알루미늄 병 사용 증가
프리미엄 레디 투 드링크(RTD) 칵테일 브랜드들은 재활용성을 유지하면서 고급스러운 포지셔닝을 어필하기 위해 2024년 한 해 동안 알루미늄 병을 도입했습니다. 일부 브랜드에서는 기존 캔에 비해 40-60%의 가격 프리미엄이 기록되었으며, 이는 소비자들이 병 특유의 견고한 촉감과 재밀봉 기능을 중요하게 여기고 있음을 보여줍니다. 알루미늄의 차단 성능은 식물 추출물을 자외선과 산소로부터 보호하여 증류주 기반 제품의 유통 기한을 연장합니다. 환경 보호를 목적으로 하는 비영리 단체와의 브랜드 협업은 지속가능성에 대한 노력을 강화하고, 소형 스틸이나 PET 용기로는 실현할 수 없는 마케팅상의 긍정적인 인상을 만들어내고 있습니다. 이러한 현상은 일회용 증류주에 위변조 방지 기능을 갖추면서도 우아한 뚜껑이 요구되는 유럽의 여행 소매 채널로도 확산되고 있습니다.
EU 음료 포장재에 대한 테더가 부착된 뚜껑 의무화(지침 2019/904)
2024년 7월 이후, EU의 음료 병에는 테더가 부착된 뚜껑의 채택이 의무화되어, 탄산음료 및 생수 각 부문에서 패키지 재설계가 진행되고 있습니다. 플라스틱 재질의 테더가 부착된 시스템에 대한 소비자의 초기 반발을 받아들여, 프리미엄 미네랄워터 및 주스 브랜드들은 힌지 구조가 내장된 알루미늄 재질의 나사식 뚜껑을 채택하기 시작했습니다. 알루미늄은 무한히 재활용이 가능하며 자원 회수 시설에서 쉽게 분리할 수 있기 때문에 브랜드 소유자는 끈이 달린 뚜껑에 대한 규제와 향후 도입될 금속 회수율 90% 목표 모두를 충족할 수 있습니다. 다국적 기업들은 생산 라인 변경에 따른 복잡성을 피하기 위해 EU 이외 시장에서도 포장 형식을 통일하고 있으며, 이로 인해 부가가치가 높은 알루미늄 뚜껑에 대한 단기적인 수요가 더욱 증가하고 있습니다.
LME 알루미늄 가격 변동이 가공업체의 이익률을 압박
2025년 2월, 알루미늄 잉곳 가격은 톤당 2,662달러에 달했으며, 6개월 동안 15% 이상 변동함에 따라 장기 고정 계약으로 판매하는 가공업체의 이익이 압박받고 있습니다. 헤지 프로그램이 없는 중소 뚜껑 제조업체들은 이익률 악화에 직면해 있으며, 정교한 리스크 관리 부서를 갖춘 다국적 기업들에게 매력적인 인수 대상으로 떠오르고 있습니다. 러시아 수출의 불확실성, 유럽의 제련 전력 비용 급등, 그리고 미국의 새로운 컨테이너 관세가 모두 가격 변동을 더욱 증폭시키고 있습니다. 공급을 안정화하기 위해 주요 컨버터 기업들은 재활용 재료의 비율을 높이고, 스크랩에 대한 내성이 높은 합금 배합을 모색하고 있습니다. 이러한 접근 방식은 탄소 배출 감축 약속에 부합하지만, 소둔로 업그레이드를 위한 설비 투자가 필요합니다.
부문별 분석
스크류 뚜껑은 음료, 조미료, 의약품 등 폭넓은 분야에서 사용되고 있어 2025년 기준 50.74%의 점유율을 차지하며 여전히 지배적인 위치를 유지했습니다. 이 점유율은 2025년 알루미늄 뚜껑 및 마개 시장 규모 중 37억 5,000만 달러에 해당했으며, 입증된 밀봉 신뢰성을 반영하고 있습니다. 이지 오픈 엔드는 규모는 작지만, 소비자들이 캔 커피나 즉석식사에서 편의성을 중시하는 경향이 있어 2031년까지 연평균 성장률(CAGR) 6.38%로 가장 빠르게 성장하고 있습니다. 연속 나사식 ROPP의 변형 제품은 변조 방지 기능과 고급스러운 외관을 모두 갖추고 있어 크래프트 증류주 시장에서 지지를 넓혀가고 있습니다. 크라운 코르크는 기존 맥주 포장 시장에서 여전히 중요한 위치를 차지하고 있지만, 풀바디 슬림 캔으로의 전환이 진행되고 있어 그 성장은 완만한 수준에 그치고 있습니다. 러그식, 프레스 트위스트식 및 특수한 플립오프식 디자인은 변조 방지가 요구되는 식품 및 의약품 용도로 사용되고 있으며, 이는 해당 부문이 범용 솔루션에서 용도 특화형 솔루션으로 전환되고 있음을 보여줍니다.
더 안전하고 손가락에 부담이 적은 이지 오픈 탭을 구현하는 다이컷 및 스코어링 기술에 대한 투자가 진행되고 있으며, 고령자용 영양 음료 등 새로운 대량 유통 채널을 개척하고 있습니다. 또한, 각 뚜껑 제조업체들은 장식 공간을 희생하지 않으면서도 추적성 규정을 준수하기 위해 레이저 조각을 통한 QR 코드 삽입도 추진하고 있습니다. 이러한 부가가치는 단위당 수익성을 높여, 원자재비가 상승했을 때의 이익률을 뒷받침하고 있습니다. 대조적으로, 표준적인 스크류 뚜껑 형태는 상품화(commoditization)에 직면해 있으며, 제조업체들은 pH 수치가 높은 음료의 유통 기한을 연장하는 라이너의 화학적 개선을 통해 차별화를 꾀해야 할 필요에 직면해 있습니다.
2025년, 음료 부문은 알루미늄 뚜껑 및 마개 시장에서 46.02%의 점유율을 차지한 것으로 평가되었으며, 이는 34억 1,000만 달러에 해당합니다. 이 부문에는 탄산이 포함되지 않은 물, 탄산음료, 맥주,와인, 프리미엄 증류주가 포함되며, 각각 미묘한 차이가 있는 마개에 대한 수요가 있습니다. 프리미엄 주류 제조업체들은 브랜딩의 매개체로서 알루미늄을 중시하는 반면, 탄산 청량음료 충전 업체들은 EU의 테더링 규정을 최저 비용으로 준수하는 방안을 모색하고 있습니다. 제약 분야 수요는 연평균 성장률(CAGR) 6.76%로 확대되고 있으며, 2031년까지 2억 8,400만 달러의 부가가치를 창출할 전망입니다. 이러한 성장은 무균성을 확보하기 위해 ‘플립오프(flip-off)’ 방식의 찢어지는 밀봉을 지정하는 생물학적 제제의 출시로 뒷받침되고 있습니다. 식품 용도는 매끄러운 따르기 편의성을 추구하여 금속 러그 뚜껑을 채택하는 고급 오일 및 소스에 힘입어 안정적인 추세를 유지하고 있습니다. 퍼스널케어 브랜드들은 알루미늄의 재활용 가능성을 내세워 혼합 소재 뚜껑을 대체하려 하고 있으며, 재활용 가능한 알루미늄 에어로졸 용기를 채택한 주목도 높은 데오드란트 제품의 출시가 그 증거입니다.
업계 전반에 걸친 지식 공유가 혁신을 가속화하고 있습니다. 음료 캔 공급업체는 퍼스널케어 기업과 제휴하여 로션과의 호환성을 높이기 위해 내부 코팅을 개선함으로써 대상 시장을 확대되고 있습니다. 산업용 화학제품용 뚜껑은 틈새 시장이지만, 특수 라이너와 결합함으로써 알루미늄의 내식성 이점을 누리고 있습니다. 이러한 광범위한 용도에서의 범용성은 균형 잡힌 포트폴리오 구성을 뒷받침하며, 특정 부문의 경기 순환적 침체에 대한 헤지 역할을 하고 있습니다.
지역별 분석
2025년, 아시아태평양은 중국의 활발한 음료 생산과 인도의 포장 상품 시장 확대에 힘입어 전 세계 매출의 40.20%를 차지했습니다. 2024년 11월 중국이 수입 재생 알루미늄에 대한 관세를 철폐함에 따라 비용 경쟁력이 향상되었고, 제련소는 1차 금속에 비해 할인된 가격으로 코일을 공급할 수 있게 되었습니다. 일본과 한국은 뚜껑 성형 프레스와 비전 검사 시스템을 지역 내로 수출함으로써 기술적 고도화에 일조했습니다. 동남아시아 수요는 도시화 진전에 더해, 위조 방지 뚜껑을 필수로 하는 유럽 및 미국의 패스트푸드 체인 수요에 힘입어 현지 뚜껑 생산 라인 확장을 뒷받침했습니다. 인도에서는 식용유 포장에 QR 코드를 통한 추적성을 의무화하는 규격 개정이 이루어졌으며, 이로 인해 프리미엄 러그 뚜껑의 가치 점유율이 상승하고 외국 기업의 합작 투자 유치가 이루어졌습니다.
중동 및 아프리카는 가장 빠르게 성장하는 지역으로, 2031년까지 연평균 성장률(CAGR)이 6.89%를 나타낼 것으로 예측됩니다. 나이지리아와 케냐의 음료 산업에 대한 투자에 더해, 걸프 국가들의 담수 처리된 생수 생산 능력이 수요를 뒷받침하고 있습니다. 그러나 순환형 경제 인프라가 제한적이어서 알루미늄 뚜껑 및 마개 시장의 확산 속도는 둔화되고 있습니다. 이집트가 식품 등급 전용 재활용 공장을 설립하려는 움직임은 진전을 보이고 있지만, 광범위한 도입을 위해서는 경제적으로 지속 가능한 회수 경로의 실증이 필요합니다. 남아프리카공화국의 확립된 알루미늄 제련 거점과 항만의 연결성은 내륙국인 주변 국가들로의 수출 기회를 창출하고 있습니다.
유럽은 성숙한 시장이지만, 규제가 전 세계 사양을 주도하고 있기 때문에 여전히 매우 중요한 시장입니다. 2024년 7월로 설정된 테더드 뚜껑 도입 기한으로 인해, 충전 업체들은 PET 용기와 알루미늄 용기의 설계를 동시에 재검토해야만 했으며, 이로 인해 뚜껑 전문 기업들은 엔지니어링 컨설팅 수익을 창출할 수 있었습니다. 독일의 기계 공학 클러스터는 토크 모니터링 기능을 통합하고 분당 600개의 생산 능력을 갖춘 연속 나사식 스크류 뚜껑 충전기를 개발하여 성능 기준을 한 단계 높였습니다. 이탈리아의 한 디자인 회사는 프리미엄 주류용 엠보싱 가공과 컬러 시프트 잉크를 맞춤 제작하여, 지속가능성의 관점에서 뚜껑이 코르크에서 알루미늄으로 전환되는 과정에서도 고급스러운 인상을 유지하고 있습니다.
북미 시장에서는 재밀봉 가능한 알루미늄 병에 담긴 크래프트 음료와 RTD(Ready-to-Drink) 칵테일로 소비자의 선호가 이동하는 것이 호재로 작용하고 있습니다. 2025년 4월 부과된 미국의 관세 장벽으로 인해 국내 캔용 강재 생산이 확대되고, 현지 공급이 부족해져 리쇼어링이 촉진됨에 따라 간접적으로 뚜껑용 코일 제조업체를 지원하게 되었습니다. 주요 맥주 수출국인 멕시코에서는 비용과 공급 리스크의 균형을 맞추기 위해 알루미늄과 강철 뚜껑을 병용하고 있지만, 유럽용 프리미엄 병 제품 라인에서는 알루미늄 뚜껑이 여전히 일정한 입지를 유지하고 있습니다. 브라질을 필두로 한 남미 국가들에서는 자체 제작한 뚜껑 모듈을 갖춘 새로운 음료 캔 생산 라인에 투자하여 리드 타임을 단축하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the aluminium caps and closures market size is expected to grow from USD 7.40 billion in 2025 to USD 7.65 billion in 2026 and is forecast to reach USD 9.02 billion by 2031 at 3.34% CAGR over 2026-2031.
This report is Segmented by Cap Type (Screw Caps, Crown Cork, Lugs/Press Twist, and More), Application (Beverages, Food, Pharmaceutical, Cosmetics and Personal Care, and More), Neck Finish Diameter ( Less Than and Equal To 20mm, 21-30mm, and More), Distribution Channel (Direct Sales Channels, and Indirect Sales Channels) and Geography. The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Aluminum Caps And Closures Market Trends and Insights
Rise of Premium RTD-Cocktail Aluminium Bottling in North America
Premium ready-to-drink cocktail brands introduced aluminium bottles throughout 2024 to signal upscale positioning while retaining recyclability. Several brands recorded 40-60% price premiums versus conventional cans, indicating consumers value tactile rigidity and re-close functionality. The barrier performance of aluminium protects botanical extracts from UV light and oxygen, supporting shelf life for spirit-based formulations. Brand collaborations with environmental non-profits reinforce sustainable credentials, creating a marketing halo that smaller steel or PET formats cannot match. The phenomenon is spilling into European travel-retail channels where single-serve spirits require tamper-evident yet elegant closures.
Mandatory Transition to Tethered Caps in EU Beverage Packaging (Directive 2019/904)
Since July 2024, EU beverage bottles must feature tethered closures, sparking redesign activity across carbonated soft drink and water segments.Early consumer pushback against plastic tethered systems led premium water and juice brands to adopt aluminium screw-top variants with integrated hinge mechanisms. Because aluminium is infinitely recyclable and easily detached in material-recovery facilities, brand owners meet both tethered-cap rules and forthcoming 90% metal-collection targets. Multinationals are harmonizing pack formats across non-EU markets to avoid line-change complexity, magnifying near-term demand for value-added aluminium closures.
Volatile LME Aluminium Prices Compressing Converter Margins
Aluminium ingot reached USD 2,662 per ton in February 2025, swinging more than 15% within six months and squeezing converters that sell on long-term fixed contracts. Smaller closure firms without hedging programs face eroded margins, making them attractive acquisition targets for multinationals with advanced risk-management desks. Russian export uncertainty, elevated European smelting power costs, and new US container duties all amplify volatility. To stabilize supply, leading converters raise recycled content and explore alloy recipes with higher scrap tolerance, an approach aligned with carbon-reduction pledges yet requiring capital spend on upgraded annealing furnaces.
Other drivers and restraints analyzed in the detailed report include:
- Beverage-Grade Recycled Aluminium Capacity Expansions in China
- Pharma Shift to Flip-Off Tear-Down Aluminium Seals for Biologics
- Brand-Owner Switch to PET Tethered Caps in Carbonated Soft Drinks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Screw caps retained dominance with 50.74% share in 2025 as they span beverages, condiments, and pharmaceuticals. That share equals USD 3.75 billion of the aluminium caps and closures market size in 2025, reflecting their proven sealing reliability. Easy-open ends, while smaller, are gaining fastest at a 6.38% CAGR through 2031 as consumers gravitate toward convenience features in canned coffee and ready meals. Continuous-thread ROPP variants secure traction in craft spirits because they reconcile tamper evidence with luxury visual cues. Crown corks hold relevance in traditional beer packaging, yet their growth is modest given the migration toward full-body slim cans. Lug, press-twist, and specialized flip-off designs serve tamper-sensitive food and pharma uses, illustrating the segmentation's shift from generalist to application-specific solutions.
Investment is flowing into die-cutting and scoring technologies that create safer, finger-friendly easy-open tabs, unlocking new mass channels like senior-nutrition beverages. Closure makers are also integrating laser-etched QR codes for trace-and-trace compliance without compromising decoration space. These embellishments carry higher unit economics, cushioning margins when raw-material costs rise. In contrast, standard screw-cap formats face commoditization, pressing manufacturers to differentiate through liner chemistry improvements that extend shelf life in aggressive-pH drinks.
Beverages commanded 46.02% share in 2025, equivalent to USD 3.41 billion of the aluminium caps and closures market. The segment covers still water, carbonated drinks, beer, wine, and premium spirits, each with nuanced closure needs. Premium alcohol producers elevate aluminium as a branding canvas, whereas carbonated soft-drink fillers chase lowest cost compliance to EU tethering. Pharmaceutical demand is expanding at a 6.76% CAGR, adding USD 284 million incremental value by 2031. Growth rests on biologic drug launches that specify flip-off tear-down seals to ensure sterile integrity. Food applications remain steady, propelled by gourmet oils and sauces pursuing metal lug caps for smooth pour control. Personal-care brands leverage aluminium's recyclability story to displace mixed-material lids, evidenced by high-profile deodorant launches in recyclable aluminium aerosols.
Cross-sector learning accelerates innovation: beverage can suppliers partner with personal-care companies to adapt internal varnishes for lotion compatibility, broadening addressable markets. Industrial chemical closures, though niche, benefit from aluminium's corrosion resistance when combined with specialty liners. The versatility across end-uses supports balanced portfolio exposure, hedging against cyclical dips in any one sector.
Complete Report Scope:
- By Cap Type
- Screw Caps
- Crown Cork
- Lug / Press-Twist
- Easy-Open End
- Roll-On Pilfer Proof (ROPP)
- Others (Flip-Off, Tear-Down)
- By Application
- Beverages
- Alcoholic Beverages
- Non-Alcoholic Beverages
- Food
- Pharmaceutical
- Cosmetics and Personal Care
- Industrial and Household Chemicals
- Beverages
- By Neck Finish Diameter
- Less than and Equal to 20 mm
- 21-30 mm
- 31-40 mm
- More than 40 mm
- By Distribution Channels
- Direct Sales Channels
- Indirect Sales Channels
- By Region
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- United Kingdom
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Middle East
- GCC
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific anchored 40.20% of global revenue in 2025, driven by China's prolific beverage output and India's packaged-goods expansion. Cost competitiveness improved after November 2024 when China abolished tariffs on imported recycled aluminium, enabling mills to supply coil at discounts versus primary metal. Japan and South Korea added a layer of technological sophistication, exporting closure presses and vision-inspection systems regionally. Southeast Asian demand benefitted from urbanization and Western quick-service restaurant chains insisting on tamper-proof lids, stimulating local cap conversion lines. India's standards upgrade mandating QR traceability for edible-oil packs nudged value share toward premium lug caps, attracting foreign joint ventures.
The Middle East and Africa represent the fastest-growing territory, forecast at 6.89% CAGR through 2031. Beverage investments in Nigeria and Kenya, plus desalinated bottled-water capacity in the Gulf, underpin volume. However, limited circular-economy infrastructure tempers aluminium caps and closures market penetration. Egypt's move to establish a dedicated food-grade recycling mill marks progress, yet widespread adoption awaits proof of economically viable collection streams. South Africa's established aluminium smelter base and port connectivity create export opportunities into landlocked neighbors.
Europe, though mature, remains pivotal because regulation steers global specifications. The July 2024 tethered-cap deadline forced fillers to redesign PET and aluminium containers simultaneously, generating engineering consulting revenue for closure specialists. Germany's mechanical-engineering cluster pioneered continuous-thread screw-top machines capable of 600 cpm with integrated torque monitoring, raising performance benchmarks. Italy's design houses customized embossing and color-shift inks for premium spirits, preserving perceived luxury even as closures migrate from cork to aluminium for sustainability reasons.
North America's market rides consumer migration to craft beverages and ready-to-drink cocktails packaged in resealable aluminium bottles. US tariff barriers imposed in April 2025 boosted domestic can-stock production, indirectly supporting closure coil producers by tightening local supply and encouraging reshoring. Mexico, a major beer exporter, toggles between aluminium and steel closure options to balance cost and supply risk, yet aluminium retains a foothold in premium bottle lines destined for European customers. South America, led by Brazil, invests in new beverage can lines that include in-house closure modules, shortening lead times.
- Amcor plc
- Crown Holdings Inc.
- Silgan Holdings Inc.
- Guala Closures S.p.A
- Tecnocap Group
- Pelliconi and C. SpA
- Nippon Closures Co. Ltd
- Closure Systems International (CSI)
- Berlin Packaging LLC
- Bericap GmbH
- AptarGroup Inc.
- SKS Bottle and Packaging Inc.
- Hicap Closures Co. Ltd
- Federfin Tech SRL
- Rauh GmbH & Co.
- O.Berk Company
- The Cary Company
- Alutop SAS
- Shandong Lipeng Co. Ltd
- Idea Cap SRL
- Easy Open Lid Industry Corp. (Yiwu)
- RPC Group (PET Power)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rise of Premium RTD-Cocktail Aluminium Bottling in North America
- 4.2.2 Mandatory Transition to Tethered Caps in EU Beverage Packaging (Directive 2019/904)
- 4.2.3 Beverage-Grade Recycled Aluminium Capacity Expansions in China
- 4.2.4 Pharma Shift to Flip-Off Tear-Down Aluminium Seals for Biologics
- 4.2.5 Craft Spirits Migration from Cork to Aluminium ROPP in Europe
- 4.2.6 E-commerce Leakage-Testing Protocols Driving Lug Cap Adoption in India
- 4.3 Market Restraints
- 4.3.1 Volatile LME Aluminium Prices Compressing Converter Margins
- 4.3.2 Brand-Owner Switch to PET Tethered Caps in Carbonated Soft Drinks
- 4.3.3 Tin-Free Steel Crown Cork Substitution in Mexican Beer
- 4.3.4 Limited Food-Grade Recycling Streams in Middle East
- 4.4 Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Intensity of Competitive Rivalry
- 4.7.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Cap Type
- 5.1.1 Screw Caps
- 5.1.2 Crown Cork
- 5.1.3 Lug / Press-Twist
- 5.1.4 Easy-Open End
- 5.1.5 Roll-On Pilfer Proof (ROPP)
- 5.1.6 Others (Flip-Off, Tear-Down)
- 5.2 By Application
- 5.2.1 Beverages
- 5.2.1.1 Alcoholic Beverages
- 5.2.1.2 Non-Alcoholic Beverages
- 5.2.2 Food
- 5.2.3 Pharmaceutical
- 5.2.4 Cosmetics and Personal Care
- 5.2.5 Industrial and Household Chemicals
- 5.2.1 Beverages
- 5.3 By Neck Finish Diameter
- 5.3.1 Less than and Equal to 20 mm
- 5.3.2 21-30 mm
- 5.3.3 31-40 mm
- 5.3.4 More than 40 mm
- 5.4 By Distribution Channels
- 5.4.1 Direct Sales Channels
- 5.4.2 Indirect Sales Channels
- 5.5 By Region
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 France
- 5.5.2.3 Italy
- 5.5.2.4 United Kingdom
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 GCC
- 5.5.5.1.2 Turkey
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Kenya
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Amcor plc
- 6.4.2 Crown Holdings Inc.
- 6.4.3 Silgan Holdings Inc.
- 6.4.4 Guala Closures S.p.A
- 6.4.5 Tecnocap Group
- 6.4.6 Pelliconi and C. SpA
- 6.4.7 Nippon Closures Co. Ltd
- 6.4.8 Closure Systems International (CSI)
- 6.4.9 Berlin Packaging LLC
- 6.4.10 Bericap GmbH
- 6.4.11 AptarGroup Inc.
- 6.4.12 SKS Bottle and Packaging Inc.
- 6.4.13 Hicap Closures Co. Ltd
- 6.4.14 Federfin Tech SRL
- 6.4.15 Rauh GmbH & Co.
- 6.4.16 O.Berk Company
- 6.4.17 The Cary Company
- 6.4.18 Alutop SAS
- 6.4.19 Shandong Lipeng Co. Ltd
- 6.4.20 Idea Cap SRL
- 6.4.21 Easy Open Lid Industry Corp. (Yiwu)
- 6.4.22 RPC Group (PET Power)
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment