

|
시장보고서
상품코드
2123989
수의 CRO 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Veterinary CRO - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 수의 CRO 시장 규모는 2025년에 11억 8,000만 달러, 2026년에 12억 7,000만 달러가 되어, 2031년까지 18억 5,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년까지 CAGR 7.78%로 성장할 전망입니다.
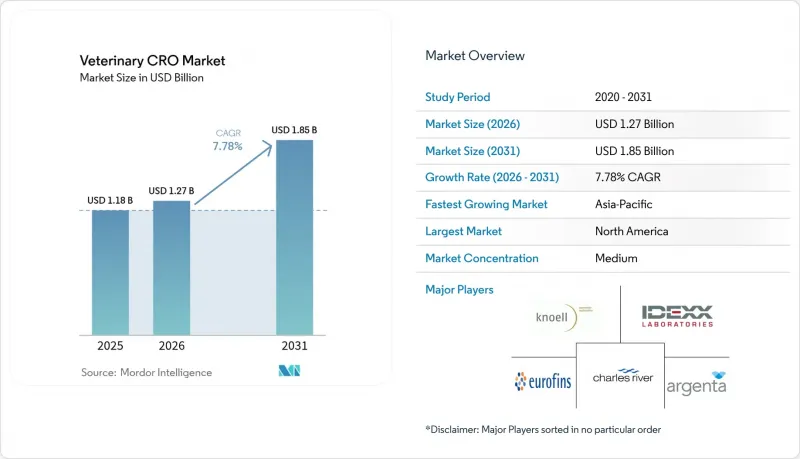
본 보고서는 서비스 유형(임상시험 등),동물 유형별(반려동물(개, 고양이, 기타 반려동물) 및 가축(소, 돼지, 가금류, 기타 가축)), 최종 사용자별(동물용 의약품·바이오기술 기업 등), 적응증별(종양학 등), 지역별(북미, 유럽 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 수의 CRO 시장 동향 및 인사이트
전 세계 동물용 의약품 지출 증가
일반 의약품 및 진단제를 포함한 전 세계 동물용 의약품 매출액은 2025년에 500억 달러를 넘어, 팬데믹 이전 수준보다 크게 증가했습니다. 현재 미국 가구는 반려동물 1마리당 연간 평균 1,500달러를 지출하고 있으며, 이는 2020년 대비 22% 증가한 수치로, 종양학, 순환기학, 신경학 분야의 첨단 임상시험에 대한 수요를 뒷받침하고 있습니다. 축산 농가 역시 마찬가지로 바이오시큐리티 예산을 증액하고 있으며, 농장 운영 비용의 최대 12%를 수의학 서비스 및 백신에 할당하고 있습니다. 반려동물과 생산용 동물 양쪽 모두에서 지출이 확대되는 가운데, 수의 CRO 시장에서는 여러 종에 걸쳐 고정 인프라 비용을 상각할 수 있는 프로젝트가 주목받고 있습니다. 전문 치료에 대한 지불 의향이 높아짐에 따라, 다양한 동물 종을 다룰 수 있는 서비스 제공업체에게는 지속 가능한 수익 기반이 마련되고 있습니다.
동물용 의약품에 대한 유리한 규제 절차
미국의 ‘동물용 의약품 사용자 부담금법(ADUFA) 제5차 개정안’에서는 중증 질환을 대상으로 하는 제품의 심사를 신속화하고, 조건부 승인 범위를 확대하기 위해 연간 3,500만 달러가 배정되고 있습니다. 유럽에서는 ‘플랫폼 기술 마스터 파일(PTMF)’을 통해 하나의 신청 서류로 여러 백신 후보를 포괄할 수 있게 되어, 중복되는 시험이 20% 가까이 감소했습니다. VICH 가이드라인 GL52에 따라 주요 시장 간 약동학 프로토콜이 통일되어, 과거에는 개발 기간을 연장시켰던 지역별 브리징 시험이 불필요해졌습니다. 이러한 호재 덕분에 시장 출시까지의 기간은 단축되지만, 한편으로 문서화 기준도 높아짐에 따라, 스폰서는 규제 측면에서 실적이 있는 CRO의 활용을 요구받고 있습니다. 조건부 승인 절차와 연계된 승인 후 유효성에 대한 약속으로 인해, 제품의 전체 수명 주기 동안 CRO의 관여가 더욱 확대되고 있습니다.
높은 개발 비용과 장기화되는 승인 절차
새로운 수의학용 생물학적 제제를 시장에 출시하려면 최대 1억 5,000만 달러의 비용이 소요되며, 7-9년이 걸릴 수 있습니다. 이는 10년 전의 5-6년에 비해 기간이 길어진 것입니다. 가축용 백신의 현장 시험에는 10-15개의 상업 농장이 참여하기도 하며, 각 사이트마다 20만-40만 달러의 예산이 추가로 소요됩니다. 반려동물의 종양학 연구 역시 비용이 많이 들며, 전문 시설에서 개 100마리를 대상으로 할 경우 500만 미 달러를 초과하기도 합니다. EMA(유럽의약품청)가 정한 식용 동물용 제품에 대한 승인 후 5년간의 모니터링 규정에 따라, 라이프사이클 비용에 200만-400만 달러가 추가로 부담됩니다. 자본 요건 증가는 소규모 혁신 기업 시장 진입을 저해하고, 자금력이 있는 스폰서에게 프로젝트가 집중되는 결과를 초래하여, 그 결과 수의 CRO 시장의 전반적인 성장 속도가 둔화될 가능성이 있습니다.
부문 분석
2025년 매출에서 임상시험이 가장 큰 비중을 차지했으나, 조화로운 VICH 지침에 따라 지역 간 신청 서류 전략이 간소화되는 가운데, 해당 부문의 7.2% 성장률은 규제 및 컨설팅 업무에 대해 예측된 연평균 성장률(CAGR) 9.43%를 밑돌고 있습니다. 독성학 및 안전성 시험은 식용 동물용 치료제에 대한 엄격한 잔류물 제거 규정에 힘입어 약 28%의 점유율을 차지했습니다. GLP 준수 독성 시험과 실시간 생물학적 분석 지원을 결합한 통합형 제공업체들은 수의 CRO 시장에서 점유율을 꾸준히 확대되고 있습니다.
예측 기간 동안, 스폰서가 신속하고 감사에 대응 가능한 신청서를 중시함에 따라 규제 및 컨설팅 분야는 수의 CRO 시장에 대한 기여도를 확대될 전망입니다. ISO 13485 인증은 중요한 차별화 요인으로 부상하고 있으며, 해당 규격을 준수하는 기업은 두 자릿수의 가격 프리미엄을 요구할 수 있게 되었습니다. 서비스 번들링을 통해 신청 서류 작성, 시험 모니터링, 의약품 안전성 감시가 단일 제공업체와의 계약 하에 일괄적으로 수행되는 사례가 증가하고 있어, 자원이 제한적인 스폰서에게 관리가 간소화되고 있습니다.
2025년 매출액 중 반려동물이 57.45%를 차지하며, 그 중심은 인간용 의약품 프로토콜을 모방한 개 및 고양이 프로젝트입니다. 종양학과 피부과는 여전히 가장 가치가 높은 적응증이며, 많은 경우 임상시험 비용을 상쇄하는 반려인 부담 비용에 의해 뒷받침되고 있습니다. 그럼에도 불구하고 아프리카 돼지열병 및 조류 인플루엔자 백신 개발이 가속화됨에 따라, 가축용 프로그램은 수의 CRO 시장에서 더 큰 점유율을 확보할 전망입니다.
각국 정부가 식량 안보를 확보하기 위해 자금을 투입하고 있는 만큼, 가축 임상시험은 연평균 성장률(CAGR) 9.66%를 나타낼 것으로 예측됩니다. 새로운 아프리카 돼지열병(ASF) 백신 후보에 힘입어 돼지 임상시험이 가장 빠르게 성장하고 있습니다. 소의 호흡기 질환 관련 프로젝트와 가금류의 생물안전 규정 또한 임상시험 건수를 증가시키고 있습니다. 이러한 변화로 인해 수익원은 소비자의 자발적 지출에서 공공 자금을 통한 질병 대책 예산으로 다각화되고 있습니다.
지역별 분석
북미는 잘 갖춰진 GLP 인프라, 6,700만 가구에 달하는 반려동물 사육 가구, 그리고 초기 데이터 패키지를 평가하는 FDA의 조건부 승인 절차에 힘입어 2025년 매출의 41.75%를 차지했습니다. 캐나다는 조화로운 심사를 통해 거래량을 확대하고 있으며, 멕시코는 가금류 및 돼지용 백신 개발에 있어 비용 효율적인 거점을 제공합니다. 2031년까지 지역별 연평균 성장률(CAGR)은 6.5%로 둔화되겠지만, 확립된 생산 능력과 반려인들이 프리미엄 치료법에 기꺼이 투자하려는 의지 덕분에 북미는 계속해서 수의 CRO 시장의 최대 구성 요소로 남을 것입니다.
유럽은 지속적인 서비스 수익을 창출하는 EMA(유럽의약청)의 의약품 감시 요건에 힘입어 전 세계 매출의 약 32%를 차지하고 있습니다. 독일의 막대한 돼지 사육 두수, 영국의 항균제 신속 승인 절차, 그리고 프랑스의 광범위한 반려동물 기반 덕분에 임상시험 활동은 서유럽에 집중되어 있습니다. EU 동물 보건법의 감시 요건이 역학 및 진단법 검증 서비스에 대한 수요를 뒷받침하고 있어, 이 지역의 성장률은 7.0%로 예측됩니다.
아시아태평양은 86.5%의 연평균 성장률(CAGR)로 모든 지역을 능가하는 성장이 예상되며, 그 원동력은 중국의 80억 달러 규모의 국내 수의약품 시장과 인도의 방대한 소 사육 두수입니다. AAALAC 인증 확대, 단일클론 항체의 현지 승인, 그리고 정부의 백신 접종 프로그램이 임상시험 건수를 끌어올리고 있습니다. 호주와 일본은 높은 규정 준수 대응 능력을 갖추고 있으나, 규제 절차의 장기화로 인해 당분간 수익 증가는 제한될 전망입니다. 중동 및 아프리카 및 남미는 2025년 매출의 8%를 차지할 것으로 예상되지만, 인프라 격차와 규제 불균형으로 인해 2031년까지 그 점유율은 10% 미만에 머물 것으로 전망됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the veterinary CRO market size is projected to be USD 1.18 billion in 2025, USD 1.27 billion in 2026, and reach USD 1.85 billion by 2031, growing at a CAGR of 7.78% from 2026 to 2031.
This report is Segmented by Service Type (Clinical Trials, and More), Animal Type (Companion Animals [Dogs, Cats, and Other Companion Species], and Livestock [Cattle, Swine, Poultry, and Other Livestocks]), End User (Animal-Health Pharma & Biotech Companies, and More), Indication (Oncology, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Veterinary CRO Market Trends and Insights
Growth in Global Animal Health Expenditure
Global veterinary pharmaceutical sales, including over-the-counter products and diagnostics, exceeded USD 50 billion in 2025, up sharply from pre-pandemic levels. U.S. households now spend an average of USD 1,500 per pet each year, a 22% jump since 2020, which sustains demand for advanced trials in oncology, cardiology, and neurology. Livestock producers have likewise raised biosecurity budgets, allocating up to 12% of farm operating costs to veterinary services and vaccines. As spending expands on both the companion and production sides, the veterinary CRO market attracts projects that amortize fixed infrastructure across species. Heightened willingness to pay for specialty therapies underscores a durable revenue base for providers capable of serving multi-species portfolios.
Favorable Regulatory Pathways for Veterinary Pharmaceuticals
The U.S. Animal Drug User Fee Act V provides USD 35 million a year to expedite reviews and broaden conditional approvals for products targeting serious conditions. In Europe, the Platform Technology Master File enables a single dossier to support multiple vaccine candidates, reducing redundant studies by nearly 20%. VICH guideline GL52 now harmonizes pharmacokinetic protocols across key markets, eliminating region-specific bridging trials that once extended timelines. Although these tailwinds shorten time-to-market, they also elevate documentation standards, prompting sponsors to enlist CROs with proven regulatory track records. Post-approval efficacy commitments linked to conditional pathways further extend CRO engagement across the product life cycle.
High Development Costs and Lengthy Approval Timelines
Bringing a novel veterinary biologic to market can cost up to USD 150 million and take 7-9 years, versus 5-6 years a decade ago. Field trials for livestock vaccines may involve 10-15 commercial farms, with each site adding USD 200,000-400,000 to budgets. Companion-animal oncology studies are similarly expensive, sometimes exceeding USD 5 million for 100 dogs enrolled across specialty centers. The EMA's five-year post-approval monitoring rule for food-animal products adds another USD 2-4 million to lifecycle costs. Escalating capital requirements deter smaller innovators and concentrate projects among well-funded sponsors, which could slow the overall expansion pace of the veterinary CRO market.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Outsourcing of R&D Activities by Animal-Health Companies
- Intensifying Focus on One Health and Zoonotic-Disease Preparedness
- Limited Availability of Specialized Animal Research Infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Clinical trials accounted for the largest share of 2025 revenue, yet the segment's 7.2% growth lags the 9.43% CAGR projected for regulatory and consulting work as harmonized VICH guidelines streamline dossier strategies across regions. Toxicology and safety studies held nearly 28% share, buoyed by stringent residue-depletion rules for food-animal therapies. Integrated providers that pair GLP toxicology with real-time bioanalytical support are steadily increasing their market share in the veterinary CRO market.
Over the forecast horizon, the regulatory-consulting niche is poised to expand its contribution to the veterinary CRO market, as sponsors prize rapid, audit-ready submissions. ISO 13485 certification has emerged as a key differentiator, with compliant firms able to command double-digit price premiums. Service bundling increasingly places dossier preparation, study monitoring, and pharmacovigilance under single-provider contracts, simplifying oversight for resource-constrained sponsors.
Companion species accounted for 57.45% of 2025 revenue, led by canine and feline projects that mimic human medicine protocols. Oncology and dermatology remain the highest-value indications, often supported by owner-paid expenses that offset trial costs. Even so, accelerating vaccine development for African swine fever and avian influenza positions livestock programs to capture a larger share of the veterinary CRO market.
Livestock trials are forecast to post a 9.66% CAGR as governments inject funding to safeguard food security. Swine studies, propelled by new ASF vaccine candidates, are the fastest riser. Cattle respiratory-disease projects and poultry biosecurity mandates also add volume. The shift diversifies revenue streams away from consumer discretionary spending toward publicly financed disease-control budgets.
Complete Report Scope:
- By Service Type
- Clinical Trials
- Toxicology & Safety Studies
- Regulatory & Consulting Services
- Other Specialized Services
- By Animal Type
- Companion Animals
- Dogs
- Cats
- Other Companion Species
- Livestock
- Cattle
- Swine
- Poultry
- Other Livestocks
- Companion Animals
- By End User
- Animal-Health Pharma & Biotech Companies
- Academic & Research Institutes
- Government & Non-Profit Sponsors
- Other End Users
- By Indication
- Oncology
- Infectious Diseases
- Dermatology
- Gastrointestinal Disorders
- Neurology
- Other Indications
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 41.75% of 2025 revenue on the strength of its dense GLP infrastructure, 67 million pet-owning households, and the FDA's conditional-approval pathway that rewards early data packages. Canada adds volume via harmonized reviews, while Mexico offers cost-effective sites for poultry and swine vaccine work. Although regional CAGR moderates to 6.5% through 2031, North America will remain the largest component of the veterinary CRO market thanks to entrenched capacity and owner willingness to fund premium therapies.
Europe accounted for roughly 32% of global revenue, supported by EMA pharmacovigilance mandates that generate recurring service streams. Germany's large swine population, the UK's fast-track antimicrobial process, and France's expansive companion-animal base concentrate trial activity in Western Europe. Regional growth is projected at 7.0%, aided by the EU Animal Health Law's surveillance requirements, which sustain demand for epidemiology and diagnostics validation services.
Asia-Pacific is set to outpace all regions with an 8.65% CAGR, led by China's USD 8 billion domestic veterinary-drug market and India's vast cattle population. Expanded AAALAC accreditation, local approval of monoclonal antibodies, and government vaccination programs drive trial volume. Australia and Japan add high-compliance capacity, though longer regulatory timelines temper immediate revenue gains. Middle East & Africa and South America jointly deliver 8% of 2025 sales, yet infrastructure gaps and fragmented rules keep their share below 10% through 2031.
- Altasciences Company, Inc.
- Argenta Limited
- Charles River
- Clinvet International (Pty) Ltd
- East Tennessee Clinical Research, Inc.
- Envigo RMS Holding Corp. (Inotiv)
- Eurofins
- IDEXX
- KLIFOVET GmbH
- knoell Germany GmbH
- LabCorp
- Mispro Biotech Services Corp.
- Oncovet Clinical Research
- Triveritas (knoell Animal Health Ltd)
- TriviumVet
- Veeda Clinical Research Ltd.
- Vetworks BV
- Wageningen Bioveterinary Research
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in Global Animal Health Expenditure
- 4.2.2 Favorable Regulatory Pathways for Veterinary Pharmaceuticals
- 4.2.3 Increasing Outsourcing of R&D Activities by Animal-Health Companies
- 4.2.4 Intensifying Focus on One-Health And Zoonotic Disease Preparedness
- 4.2.5 Expansion of Companion-Animal Biologics and Specialty Therapies
- 4.2.6 Digitalization and Data-Driven Approaches in Veterinary Research
- 4.3 Market Restraints
- 4.3.1 High Development Costs and Lengthy Approval Timelines
- 4.3.2 Limited Availability of Specialized Animal Research Infrastructure
- 4.3.3 Shortage of Skilled Veterinary Research Professionals
- 4.3.4 Ethical Concerns and Regulatory Scrutiny Over Animal Testing
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat Of New Entrants
- 4.7.2 Bargaining Power Of Suppliers
- 4.7.3 Bargaining Power Of Buyers
- 4.7.4 Threat Of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Service Type
- 5.1.1 Clinical Trials
- 5.1.2 Toxicology & Safety Studies
- 5.1.3 Regulatory & Consulting Services
- 5.1.4 Other Specialized Services
- 5.2 By Animal Type
- 5.2.1 Companion Animals
- 5.2.1.1 Dogs
- 5.2.1.2 Cats
- 5.2.1.3 Other Companion Species
- 5.2.2 Livestock
- 5.2.2.1 Cattle
- 5.2.2.2 Swine
- 5.2.2.3 Poultry
- 5.2.2.4 Other Livestocks
- 5.2.1 Companion Animals
- 5.3 By End User
- 5.3.1 Animal-Health Pharma & Biotech Companies
- 5.3.2 Academic & Research Institutes
- 5.3.3 Government & Non-Profit Sponsors
- 5.3.4 Other End Users
- 5.4 By Indication
- 5.4.1 Oncology
- 5.4.2 Infectious Diseases
- 5.4.3 Dermatology
- 5.4.4 Gastrointestinal Disorders
- 5.4.5 Neurology
- 5.4.6 Other Indications
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (Includes Global-Level Overview, Market-Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key Companies, Products & Services, And Recent Developments)
- 6.3.1 Altasciences Company, Inc.
- 6.3.2 Argenta Limited
- 6.3.3 Charles River Laboratories, Inc.
- 6.3.4 Clinvet International (Pty) Ltd
- 6.3.5 East Tennessee Clinical Research, Inc.
- 6.3.6 Envigo RMS Holding Corp. (Inotiv)
- 6.3.7 Eurofins Scientific SE
- 6.3.8 IDEXX Laboratories, Inc.
- 6.3.9 KLIFOVET GmbH
- 6.3.10 knoell Germany GmbH
- 6.3.11 Labcorp Drug Development
- 6.3.12 Mispro Biotech Services Corp.
- 6.3.13 Oncovet Clinical Research
- 6.3.14 Triveritas (knoell Animal Health Ltd)
- 6.3.15 TriviumVet
- 6.3.16 Veeda Clinical Research Ltd.
- 6.3.17 Vetworks BV
- 6.3.18 Wageningen Bioveterinary Research
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


