

|
시장보고서
상품코드
2124013
특발성 폐섬유증 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Idiopathic Pulmonary Fibrosis - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
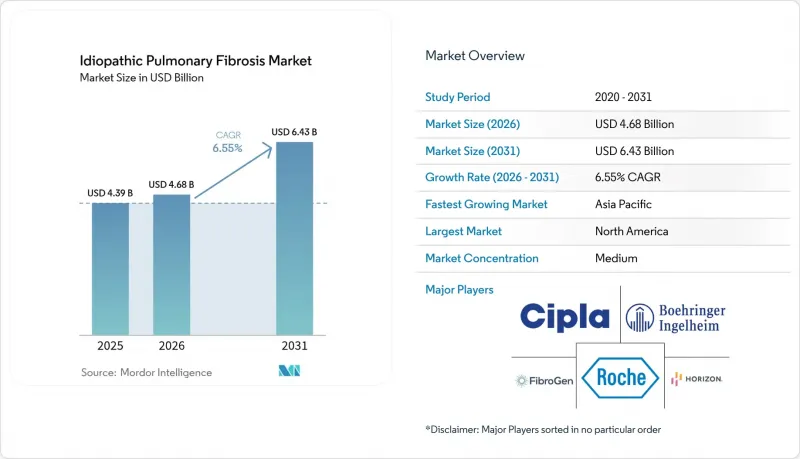
에 의하면, 특발성 폐섬유증 시장 규모는 2025년 43억 9,000만 달러에서 2026년에는 46억 8,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 6.55%로 성장을 지속하여, 2031년에는 64억 3,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 약물 유형(닌테다니브, 필페니돈, 기타 약물), 작용기전(항섬유화제, 티로신 키나제 억제제, 기타 작용기전), 투여 경로(경구, 비경구, 흡입),최종 사용자(병원 및 진료소 등), 지역(북미, 유럽, 아시아태평양 등)별로 분류되어 있습니다. 시장 전망은 금액(미화) 기준으로 제시되어 있습니다.
전 세계 특발성 폐섬유증 시장 동향 및 인사이트
IPF 유병률 증가 및 인구 고령화
세계 인구의 고령화에 따라 IPF 유병률은 계속 상승하고 있으며, 이는 의료 시스템에 지속적인 부담을 주는 동시에 신약에 대한 수요를 촉진하고 있습니다. 유럽에서는 연간 약 4만 건의 신규 사례가 진단되고 있으며, 한국의 유병률은 인구 1만 명당 4.5명을 넘어 북미의 약 2배에 달할 전망입니다. 치료비는 IPF 비환자에 비해 2.5-3.5배 더 높으며, 이는 제약 기업의 투자를 촉진하고 고령자용 제제 개발을 뒷받침하고 있습니다.
진단 능력 확대와 조기 발견 프로그램
고해상도 컴퓨터 단층촬영(CT)은 여전히 기본적인 검사법이지만, 2024년 FDA가 AI 기반 알고리즘을 승인한 것은 방사선 진단 워크플로우에 획기적인 변화를 가져왔습니다. PROLIFIC 멀티 애널라이트 패널과 같은 혈중 및 호기 바이오마커 분야의 병행된 발전은 더 조기적인 확정 진단을 가능하게 하고, 치료법 선택을 위한 환자 계층화를 보다 효과적으로 수행할 수 있도록 지원하고 있습니다. 조기 개입은 치료 효과의 지속성을 높이고, 특발성 폐섬유증의 잠재 시장을 확대합니다.
항섬유화제의 높은 비용과 접근성 제한
연간 치료비는 호흡기 치료 예산의 상당 부분을 차지하여, 저소득 지역에서의 치료 도입을 제약하고 있습니다. 적격 환자 중 치료를 시작한 비율은 고작 25%에 불과하기 때문에 제약사들은 가치 기반 가격 책정이나 본인 부담금 경감 지원 프로그램 도입을 검토하고 있습니다. 2021년부터 시판되고 있는 필페니돈의 제네릭 의약품은 단기적인 해결책이 될 수 있지만, 추가적인 특허가 만료되고 가격이 더욱 하락해야만 광범위한 상업적 영향을 기대할 수 있을 것입니다.
부문 분석
필페니돈은 처방 의사의 높은 인지도와 조기 시장 출시 덕분에 2025년 특발성 폐섬유증 시장에서 43.35%의 점유율을 차지했습니다. 닌테다니브는 진행성 섬유화성 간질성 폐질환을 포괄하는 광범위한 적응증 덕분에 연평균 성장률(CAGR) 7.52%라는 전망을 뒷받침하고 있습니다. 비교 코호트 연구에서는 생존율 향상 측면에서 유사한 효과가 보고되었으나, 이상반응(AE) 프로파일에는 차이가 있어 이는 의사의 선택에 직접적인 영향을 미치고 있습니다. PDE4B 및 LPA1 조절제와 같은 차세대 후보 약물은 장기 특이적 표적화와 투여 중단 위험 감소를 통해 시장 점유율 분포를 재편할 가능성이 있습니다.
데우필페니돈(LYT-100)의 도입으로, 기준 약물인 필페니돈에 비해 소화기계 이상반응이 50% 감소했습니다. 이는 제형 개선을 통해 제품의 수명 주기를 연장하고, 필페니돈 프랜차이즈를 유지할 수 있음을 시사합니다. 현재 검토 중인 병용 요법에서는 필페니돈이나 닌테다닙을 주축 요법으로 포함시킬 수 있어, 신약이 등장하더라도 그 상업적 의의를 확고히 할 수 있을 것입니다.
티로신 키나제 억제제는 닌테다닙의 다중 수용체 차단 작용에 힘입어 연평균 성장률(CAGR) 9.12%라는 가장 급격한 성장 궤적을 보이고 있습니다. 네란오미라스트와 같은 이중 경로 약물은 항염증 작용과 항섬유화 작용을 모두 갖추고 있으며, 병행된 경로의 조절이 폐 기능 유지에 탁월하다는 과학계의 새로운 합의를 반영하고 있습니다.
초기 단계 프로그램에서는 세노리틱, 인테그린 억제제, TGF-β 신호 전달 억제제에 대한 연구가 진행되고 있습니다. 상하이 아크 바이오파마슈티컬(Shanghai Ark BioPharmaceutical)의 AK3280은 중국 내 31곳의 임상시험 시설에서 섬유화와 관련된 여러 경로를 조절함으로써 폐 기능의 현저한 개선을 보여주었습니다. 고도의 바이오마커 패널이 엔도유형 선정을 이끌어내며, 차별화된 규제 당국 신청 및 보험사와의 협상을 뒷받침하고 있습니다.
지역별 분석
북미는 광범위한 보험 적용 범위, ILD 센터의 밀집된 네트워크, 그리고 방사선과에서의 AI 진단 도입 가속화에 힘입어 2025년 매출의 41.05%를 차지했습니다. 벤처 캐피탈은 계속해서 후기 임상시험 프로그램에 투자하고 있으며, 미국 학술 컨소시엄에서 선구적으로 도입된 적응형 임상시험 설계 덕분에 규제 승인까지의 일정이 가속화되고 있습니다. 바이오마커 검사에 대한 지불 기관의 수용에 힘입은 정밀 의학(Precision Medicine) 접근 방식 덕분에 전문의들의 도입이 확대되고 있으며, 치료에 대한 환자의 지속률이 안정적으로 유지되고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 2026년부터 2031년까지 연평균 성장률(CAGR) 8.62%로 성장을 지속하고, 있습니다. 중국과 일본은 진단된 환자 수가 많아 상업적 잠재력을 주도하고 있는 반면, 한국은 인구 1만 명당 4.5명으로 세계 최고 수준의 유병률을 기록하고 있습니다. 특발성 폐섬유증(IPF) 시장은 지역 내 임상시험 실시 거점의 밀도가 높은 데서 혜택을 보고 있으며, 현재 IPF 연구의 44%가 아시아태평양에서 수행되고 있어 의료진의 임상시험용 약물에 대한 조기 이해가 깊어지고, 시판 후 판매 확대까지의 기간이 단축되고 있습니다. 상하이 아크(Shanghai Ark)와 같은 국내 혁신 기업들이 지역 내 경쟁을 더욱 활성화시키고 있습니다.
유럽은 희귀질환 치료제에 대한 강력한 규제 인센티브로 인해 여전히 매우 중요한 시장입니다. 벨기에의 2024년 개정안이 대표하듯이, 각국의 보험 적용 범위 확대로 인해 항섬유화제에 대한 접근성이 확대되고 있으며, EU 전역을 대상으로 하는 ‘호라이즌(Horizon)’ 기금이 중개 연구 프로젝트를 지원하고 있습니다. 전문 ILD(간질성 폐질환) 센터에서의 항섬유화제 접근률은 91%인 반면, 비전문 시설에서는 60%에 그치고 있어 전문 지식이 집중되어 있는 것의 이점이 부각되고 있습니다. 통일된 임상 실무 지침을 통해 주요 경제권 전반에 걸쳐 일관된 도입이 촉진되고 있으며, 전 세계 매출에서 유럽이 차지하는 비중이 유지되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the idiopathic pulmonary fibrosis market size is expected to grow from USD 4.39 billion in 2025 to USD 4.68 billion in 2026 and is forecast to reach USD 6.43 billion by 2031 at 6.55% CAGR over 2026-2031.
This report is Segmented by Drug Type (Nintedanib, Pirfenidone, Other Drug Types), Mode of Action (Antifibrotic Agents, Tyrosine Kinase Inhibitors, Other Modes of Action), Route of Administration (Oral, Parenteral, Inhalation), End User (Hospitals and Clinics, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Idiopathic Pulmonary Fibrosis Market Trends and Insights
Increasing Prevalence of IPF Coupled with Aging Demographics
Incidence continues to rise in tandem with global population aging, placing sustained pressure on healthcare systems and pushing demand for novel medicines. Europe diagnoses about 40,000 new cases annually, and prevalence in South Korea tops 4.5 per 10,000 persons, nearly double North American rates. Care costs run 2.5-to-3.5 times higher than for non-IPF patients, incentivizing pharmaceutical investment and stimulating development of geriatric-adapted formulations.
Expansion of Diagnostic Capabilities and Early Detection Programs
High-resolution computed tomography remains foundational, yet 2024 FDA clearance of an AI-enabled algorithm signaled a step-change in radiology workflows. Parallel progress in circulating and exhaled-breath biomarkers such as the PROLIFIC multi-analyte panel supports earlier confirmatory testing and stratifies patients more effectively for therapy selection. Earlier intervention strengthens treatment response durability, expanding the addressable idiopathic pulmonary fibrosis market.
High Cost and Limited Accessibility of Antifibrotic Drugs
Annual treatment bills consume a sizable share of respiratory-care budgets, constraining uptake in lower-income regions. With only 25% of eligible patients started on therapy, manufacturers are exploring value-based pricing and co-pay assistance programs. Generic pirfenidone, available since 2021, offers near-term relief but broad commercial impact hinges on further price erosion once additional patents lapse.
Other drivers and restraints analyzed in the detailed report include:
- Advancements in Antifibrotic Therapies and Robust Pipeline Momentum
- Strategic Collaborations & Investments in Fibrosis Research
- Adverse Side-Effect Profile Leading to Treatment Discontinuation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pirfenidone captured 43.35% idiopathic pulmonary fibrosis market share in 2025 through wider prescriber familiarity and earlier commercial rollout. Nintedanib's broader label covering progressive fibrosing interstitial lung diseases underpins its 7.52% CAGR forecast. Comparative cohort studies report similar survival benefit yet divergent AE profiles that directly shape physician choice. Next-wave candidates such as PDE4B and LPA1 modulators-could recalibrate share distribution by offering organ-specific targeting and lower discontinuation risk.
The introduction of deupirfenidone (LYT-100) lowered gastrointestinal events by 50% versus reference pirfenidone, signaling that reformulations can stretch product lifecycles and sustain pirfenidone's franchise. Combination regimens under investigation could embed pirfenidone or nintedanib as backbone therapy, anchoring their commercial relevance even as new agents arrive.
Antifibrotic agents controlled 82.05% of 2025 revenue, highlighting their foundational role in dampening extracellular-matrix deposition. Tyrosine kinase inhibitors contribute the sharpest growth trajectory at 9.12% CAGR, thanks to nintedanib's multi-receptor blockade. Dual-pathway drugs such as nerandomilast combine anti-inflammatory and antifibrotic effects, mirroring evolving scientific consensus that parallel pathway modulation affords superior lung-function preservation.
Early-stage programs are exploring senolytics, integrin blockers, and TGF-B signaling disruptors. Shanghai Ark Biopharmaceutical's AK3280 illustrated significant lung-function gains by modulating multiple fibrosis-linked pathways across 31 Chinese trial sites. Sophisticated biomarker panels guide endotype selection, supporting differentiated regulatory filings and payer negotiations.
Complete Report Scope:
- By Drug Type
- Nintedanib
- Pirfenidone
- Other Drug Types
- By Mode of Action
- Antifibrotic Agents
- Tyrosine Kinase Inhibitors
- Other Modes of Action
- By Route of Administration
- Oral
- Parenteral
- Inhalation
- By End User
- Hospitals & Clinics
- Specialty Clinics
- Home-Care Settings
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 41.05% of 2025 revenue, supported by deep reimbursement coverage, a dense network of ILD centers, and rapid incorporation of AI diagnostics into radiology suites. Venture capital continues to sponsor late-stage programs, and adaptive trial designs pioneered in United States academic consortia are accelerating regulatory timetables. Precision-medicine approaches, bolstered by payer acceptance of biomarker testing, are widening specialist adoption and stabilizing patient retention on therapy.
Asia-Pacific is the fastest-expanding region, posting an 8.62% CAGR across 2026-2031. China and Japan dominate commercial potential owing to large diagnosed populations, while South Korea records the highest prevalence globally at 4.5 per 10,000 persons. The idiopathic pulmonary fibrosis market benefits from regional trial-site density 44% of current IPF studies are run in Asia-Pacific, strengthening early physician familiarity with investigational agents and shortening launch ramp-up times. Domestic innovators such as Shanghai Ark are further stimulating local competition.
Europe remains a pivotal market with strong regulatory incentives for rare-disease therapeutics. National reimbursement expansion exemplified by Belgium's 2024 update broadens antifibrotic accessibility, while pan-EU Horizon funding underwrites translational projects. Specialist ILD centers exhibit 91% antifibrotic access versus 60% in non-specialist facilities, underlining the benefits of concentrated expertise. Harmonized clinical-practice guidelines support consistent uptake across major economies, sustaining Europe's contribution to global revenue.
- Roche
- Boehringer Ingelheim
- Cipla
- Merck
- Bristol-Myers Squibb
- United Therapeutics Corp.
- FibroGen Inc.
- Horizon Therapeutics
- Avalyn Pharma Inc.
- MediciNova Inc.
- Gyre Therapeutics Inc.
- AstraZeneca
- Vicore Pharma
- Novartis
- Tvardi Therapeutics
- Pliant Therapeutics
- Galapagos NV
- Gyre Therapeutics
- AdAlta Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Prevalence of IPF Coupled with Aging Demographics
- 4.2.2 Expansion of Diagnostic Capabilities and Early Detection Programs
- 4.2.3 Advancements in Antifibrotic Therapies and Robust Pipeline Momentum
- 4.2.4 Strategic Collaborations & Investments in Fibrosis Research
- 4.2.5 Increased Use of Artificial Intelligence for Radiological Screening & Disease Progression Monitoring
- 4.2.6 Rising Patient Advocacy and Awareness Campaigns Worldwide
- 4.3 Market Restraints
- 4.3.1 High Cost and Limited Accessibility of Antifibrotic Drugs
- 4.3.2 Adverse Side-Effect Profile Leading to Treatment Discontinuation
- 4.3.3 Limited Therapeutic Options Beyond Antifibrotics
- 4.3.4 Low Diagnosis Rates in Primary Care Settings
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers/Consumers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Drug Type
- 5.1.1 Nintedanib
- 5.1.2 Pirfenidone
- 5.1.3 Other Drug Types
- 5.2 By Mode of Action
- 5.2.1 Antifibrotic Agents
- 5.2.2 Tyrosine Kinase Inhibitors
- 5.2.3 Other Modes of Action
- 5.3 By Route of Administration
- 5.3.1 Oral
- 5.3.2 Parenteral
- 5.3.3 Inhalation
- 5.4 By End User
- 5.4.1 Hospitals & Clinics
- 5.4.2 Specialty Clinics
- 5.4.3 Home-Care Settings
- 5.4.4 Other End Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 F. Hoffmann-La Roche Ltd (Genentech)
- 6.3.2 Boehringer Ingelheim International GmbH
- 6.3.3 Cipla Ltd
- 6.3.4 Merck & Co., Inc.
- 6.3.5 Bristol-Myers Squibb Company
- 6.3.6 United Therapeutics Corp.
- 6.3.7 FibroGen Inc.
- 6.3.8 Horizon Therapeutics plc
- 6.3.9 Avalyn Pharma Inc.
- 6.3.10 MediciNova Inc.
- 6.3.11 Gyre Therapeutics Inc.
- 6.3.12 AstraZeneca plc
- 6.3.13 Vicore Pharma
- 6.3.14 Novartis AG
- 6.3.15 Tvardi Therapeutics
- 6.3.16 Pliant Therapeutics
- 6.3.17 Galapagos NV
- 6.3.18 Gyre Therapeutics
- 6.3.19 AdAlta Ltd
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


