

|
시장보고서
상품코드
2124018
센서 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
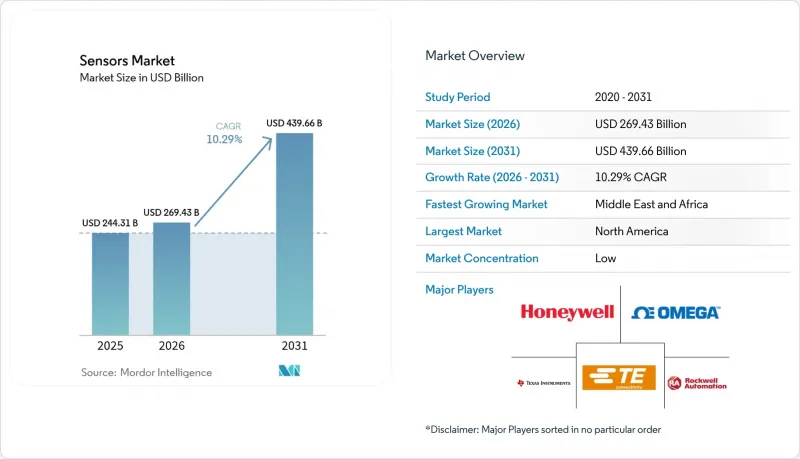
에 의하면, 센서 시장 규모는 2025년 2,443억 1,000만 달러로 평가되었고, 2026년에는 2,694억 3,000만 달러로 추정되고, 2026-2031년 CAGR 10.29%로 성장을 지속할 전망이며, 2031년에는 4,396억 6,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 측정 매개 변수별(온도, 유량 등), 작동 모드별(광학식, 피에조 저항식, 압전식 등), 기술별(MEMS, 포토닉 등), 통합 수준별(디스크리트 센서, 통합형/임베디드형 센서), 출력별(아날로그, 디지털), 최종 사용자 산업별(자동차, 산업 제조 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 센서 시장 동향 및 인사이트
자율주행 분야에서의 멀티 센서 융합 채택 확대
LiDAR, 레이더, 카메라의 데이터 스트림은 현재 통합된 지각 스택에 통합되어 있으며, 모든 신형 차량의 첨단 운전자 보조 시스템(ADAS)에 관한 EU 일반 안전 규정 2019/2144를 충족하는 중복성이 확보되어 있습니다. 테슬라의 완전 자율 주행용 컴퓨터는 이미 8대의 카메라, 12개의 초음파 센서 및 1대의 레이더에서 들어오는 입력을 144 TOPS로 처리하며 성능 벤치마크를 확립하고 있습니다. Tier 1 공급업체들은 통합 비용 절감, 부품 명세서(BOM) 축소, 그리고 시장 출시 기간 단축을 실현하는 사전 보정된 지각 제품군을 제공함으로써 이에 대응하고 있습니다.
아시아의 기존 공장에서 스마트 팩토리로의 개조가 급증하고 있습니다.
중국의 ‘제14차 5개년 계획’에서는 디지털 인프라에 1조 4,000억 달러가 배정되었으며, 그 대부분은 예측 유지보수 실현과 수명 주기 20-30% 연장을 목적으로 센서가 풍부하게 탑재된 기존 기계의 업그레이드에 사용되고 있습니다. 기존 생산 라인에 설치된 진동, 온도, 유량 측정 장치에서 클라우드 분석 시스템으로 데이터가 전송됨으로써, 공장 전체를 재구축하지 않고도 가동 중단 시간을 줄이고 설비 종합 효율(OEE)을 향상시킬 수 있습니다.
자동차 등급 MEMS 파운드리 공급 부족
AEC-Q100 인증 주기는 최장 2년에 달하며, 이 엄격한 기준을 충족하는 아시아태평양의 팹은 극소수에 불과합니다. ST마이크로일렉트로닉스는 클린룸 면적을 확대하고 있지만, 전기차의 보급으로 인해 새로운 배터리 관리 및 열 모니터링 수요가 추가되면서 압박이 더욱 가중되고 있습니다.
부문 분석
온도 센서는 2025년에 센서 시장 점유율의 22.74%를 차지했으며, 자동차 열 관리 루프 및 산업용 공정 제어에서 여전히 필수적인 요소입니다. 화학 센서는 가장 빠르게 성장하고 있으며, 배기가스 모니터링 및 작업장 안전 규제의 강화를 배경으로 2031년까지 연평균 성장률(CAGR) 14.12%로 성장할 전망입니다. 유량, 진동, 압력 각 카테고리는 예측 유지보수의 적용 범위를 확대함으로써 센서 시장을 더욱 성장시키고 있으며, 근접 센서는 기계 안전 보호 관련 규정을 준수하고 있습니다.
소형화가 진행됨에 따라 온도 센서 내부에 AI 엔진이 통합되어, 클라우드에 의한 지연 없이 로컬에서 이상을 감지할 수 있게 되었습니다. 관성, 자기, 광학, 습도 센서가 제품 라인업을 풍부하게 하고 있으며, 스마트폰의 방향 감지부터 스마트 시티의 공기질 모니터링망에 이르기까지 폭넓은 용도에 대응하고 있습니다.
2025년에는 저비용과 산업용 및 자동차용 대시보드에 대한 광범위한 채택으로 인해 전기 저항식 센서가 센서 시장의 19.18%를 차지했습니다. 자율 주행에 필수적인 LiDAR 시스템은 가격 하락과 기계 부품을 배제한 솔리드 스테이트 어레이로의 전환을 반영하여, 2031년까지 연평균 성장률(CAGR) 16.74%로 확대될 것으로 예측됩니다. 광학식, 피에조 저항식, 압전식, 정전용량식, 자기식 및 음향식 등 각 방식은 시각, 압력, 진동, 터치, 소리에 관한 요구 사항을 충족하는 다양한 분야를 구성하고 있습니다.
Velodyne사의 4D LiDAR와 같은 기술 혁신을 통해 속도 벡터가 거리 및 각도와 통합되어, 운전 지원 기능에서의 물체 분류 정확도가 향상되고 있습니다. 한편, 압전식 에너지 하베스터는 외딴 지역의 파이프라인에 설치된 배터리 없는 센서 노드에 마이크로줄 단위의 전력을 공급하고 있습니다.
지역별 분석
2025년, 아시아태평양은 전 세계 매출의 36.21%를 차지했습니다. 이는 중국의 1조 4,000억 달러 규모의 디지털 인프라 구축, 일본의 선진적인 자동차 공급망, 그리고 한국의 리소그래피 기술 리더십에 힘입은 결과입니다. 정부의 인센티브로 인해 팹 및 임베디드 센서 스타트업의 자본 장벽이 낮아졌으며, 그 결과 설계 및 생산 노하우가 집중된 지역 클러스터가 형성되고 있습니다. 공급업체들은 소비자용 전자기기 조립 라인의 대부분과 가까운 입지를 활용하여 리드타임과 물류 비용을 절감하고 있습니다.
유럽에서는 엄격한 안전 및 환경 규제를 배경으로 고부가가치 수요가 견조한 추세를 보이고 있습니다. ADAS(첨단 운전자 보조 시스템) 탑재 의무화 및 산업의 탈탄소화 목표로 인해, 더 높은 성능과 기능 안전성을 갖춘 제품에 대한 수요가 증가하고 있습니다. EU의 ‘칩법’에 따른 보조금과 NXP의 10억 유로 규모 대출 등 유럽투자은행(EIB)의 자금 지원으로 국내 자동차용 생산 능력이 새롭게 확대되고 있습니다.
중동 및 아프리카에서는 걸프협력회의(GCC) 회원국들이 스마트 그리드, 해수 담수화 모니터링 및 대규모 재생에너지 도입을 추진함에 따라 연평균 성장률(CAGR) 14.58%의 성장이 예상됩니다. 아프리카의 광업 및 수송 회랑에서는 먼지, 진동, 전력 불안정성을 견딜 수 있는 견고한 센서의 도입이 점점 더 확대되고 있습니다. 라틴아메리카는 규모는 작지만, 브라질과 멕시코 전역에서 스마트 농업 시범 사업이 전개되고 있어 수요가 서서히 증가하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the sensors market size is expected to grow from USD 244.31 billion in 2025 to USD 269.43 billion in 2026 and is forecast to reach USD 439.66 billion by 2031 at 10.29% CAGR over 2026-2031.
This report is Segmented by Parameter Measured (Temperature, Flow and More), Mode of Operation (Optical, Piezoresistive, Piezoelectric, and More), Technology (MEMS, Photonic, and More), Integration Level (Discrete Sensors, Integrated/Embedded Sensors), Output (Analog, Digital), End-User Industry (Automotive, Industrial Manufacturing, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Sensors Market Trends and Insights
Increasing adoption of multi-sensor fusion in autonomous mobility
LiDAR, radar, and camera streams are now integrated into unified perception stacks, creating redundancy that meets the EU General Safety Regulation 2019/2144 for advanced driver assistance in all new vehicles. Tesla's full self-driving computer already processes inputs from 8 cameras, 12 ultrasonic units, and a radar at 144 TOPS, setting a performance benchmark. Tier-1 suppliers are responding with pre-calibrated perception suites that lower integration cost, compress bill-of-materials, and accelerate time-to-market.
Proliferation of smart-factory retrofits in brown-field Asian plants
China's 14th Five-Year Plan earmarked USD 1.4 trillion for digital infrastructure, much of which targets sensor-rich upgrades of legacy machinery to unlock predictive maintenance and 20-30% lifecycle extensions. Vibration, temperature, and flow devices fitted to existing lines feed cloud analytics that cut downtime and lift overall equipment effectiveness without full plant reconstruction.
Supply tightness of automotive-grade MEMS foundry capacity
AEC-Q100 qualification cycles span up to two years and only a few Asia-Pacific fabs meet the stringent criteria. STMicroelectronics is expanding clean-room footprints, yet EV proliferation adds pressure by introducing fresh battery-management and thermal-monitoring loads.
Other drivers and restraints analyzed in the detailed report include:
- Shift toward condition-based asset monitoring in offshore energy
- Mandatory inclusion of ADAS sensing suites in next-gen EU vehicles
- Calibration drift challenges in long-life vibration sensors
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Temperature devices held 22.74% sensors market share in 2025 and remain indispensable for automotive thermal loops and industrial process control. Chemical variants are scaling fastest, on course for 14.12% CAGR through 2031 on rising emissions monitoring and workplace-safety mandates. Flow, vibration, and pressure categories together deepen the sensors market with predictive maintenance reach, while proximity units ensure machine-guarding compliance.
Continued miniaturization now allows integrated AI engines inside temperature elements, enabling local anomaly detection without cloud latency. Inertial, magnetic, optical, and humidity devices round out the portfolio, serving everything from smartphone orientation to smart-city air-quality grids.
Electrical-resistance designs accounted for 19.18% of the sensors market in 2025 thanks to low cost and broad design-in across industrial and vehicle dashboards. LiDAR systems, critical for autonomous navigation, are projected to rise at 16.74% CAGR through 2031, reflecting price drops and movement to solid-state arrays that shed mechanical parts. Optical, piezoresistive, piezoelectric, capacitive, magnetic, and acoustic modes complete a diverse field addressing vision, pressure, vibration, touch, and sound requirements.
Advances such as Velodyne's 4D LiDAR integrate velocity vectors with distance and angle, sharpening object classification for driver-assist functions. Meanwhile, piezoelectric harvesters supply micro-joule power budgets for battery-less sensor nodes in remote pipelines.
Complete Report Scope:
- By Parameter Measured
- Temperature
- Flow
- Chemical
- Vibration
- Pressure
- Proximity
- Inertial
- Other Parameters
- By Mode of Operation
- Optical
- Piezoresistive
- Piezoelectric
- Electrical Resistance
- Image
- LiDAR
- Other Modes
- By Technology
- MEMS
- Photonic
- CMOS
- Nano-electromechanical (NEMS)
- By Integration Level
- Discrete Sensors
- Integrated / Embedded Sensors
- By Output
- Analog
- Digital
- By End-user Industry
- Automotive
- Industrial Manufacturing
- Medical and Wellness
- Aerospace
- Consumer Electronics
- Oil and Gas
- Construction
- Defense
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific held 36.21% of global revenue in 2025, anchored by China's USD 1.4 trillion digital-infrastructure push, Japan's advanced automotive supply chains, and South Korea's lithography leadership. Government incentives lower capital hurdles for fabs and embedded-sensor startups alike, translating into a dense regional cluster of design and production know-how. Suppliers enjoy proximity to the bulk of consumer-electronics assembly lines, compressing lead times and logistics costs.
Europe delivers steady high-value demand around stringent safety and environmental regulations. Mandatory ADAS fitment and industrial decarbonization targets push purchasing toward higher-performance, functionally safe products. The EU's Chips Act grants and European Investment Bank loans such as NXP's EUR 1 billion facilities funnel fresh capacity into on-shore automotive-grade production.
Middle East & Africa is projected to expand at 14.58% CAGR as Gulf Cooperation Council states embed smart grids, desalination monitoring, and large-scale renewables. African mining and transport corridors increasingly deploy ruggedized sensors that tolerate dust, vibration, and power instability. Latin America, though smaller, sees smart-agriculture pilots across Brazil and Mexico, adding incremental volume.
- Honeywell International Inc.
- Bosch Sensortec GmbH
- Texas Instruments Inc.
- TE Connectivity Ltd
- Rockwell Automation Inc.
- OMEGA Engineering inc.
- STMicroelectronics N.V.
- Infineon Technologies AG
- NXP Semiconductors N.V.
- ams OSRAM AG
- Analog Devices Inc.
- Renesas Electronics Corp.
- Microchip Technology Inc.
- ROHM Semiconductor
- Omron Corp.
- ABB Ltd
- Sick AG
- Qualcomm Technologies Inc.
- Velodyne Lidar Inc.
- LeddarTech Inc.
- TDK Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing adoption of multi-sensor fusion in autonomous mobility
- 4.2.2 Proliferation of smart-factory retrofits in brown-field Asian plants
- 4.2.3 Shift toward condition-based asset monitoring in offshore energy
- 4.2.4 Mandatory inclusion of ADAS sensing suites in next-gen EU vehicles
- 4.2.5 Ultra-low-power environmental sensing for battery-free IoT tags
- 4.3 Market Restraints
- 4.3.1 Supply tightness of automotive-grade MEMS foundry capacity
- 4.3.2 Calibration drift challenges in long-life vibration sensors
- 4.3.3 Fragmented wireless protocol standards hindering smart-sensor interoperability
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory and Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Degree of Competition
- 4.7 Flexible and Printed Sensors Dynamics (current status, projections)
- 4.8 Macroeconomic and Pandemic Impact Assessment
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Parameter Measured
- 5.1.1 Temperature
- 5.1.2 Flow
- 5.1.3 Chemical
- 5.1.4 Vibration
- 5.1.5 Pressure
- 5.1.6 Proximity
- 5.1.7 Inertial
- 5.1.8 Other Parameters
- 5.2 By Mode of Operation
- 5.2.1 Optical
- 5.2.2 Piezoresistive
- 5.2.3 Piezoelectric
- 5.2.4 Electrical Resistance
- 5.2.5 Image
- 5.2.6 LiDAR
- 5.2.7 Other Modes
- 5.3 By Technology
- 5.3.1 MEMS
- 5.3.2 Photonic
- 5.3.3 CMOS
- 5.3.4 Nano-electromechanical (NEMS)
- 5.4 By Integration Level
- 5.4.1 Discrete Sensors
- 5.4.2 Integrated / Embedded Sensors
- 5.5 By Output
- 5.5.1 Analog
- 5.5.2 Digital
- 5.6 By End-user Industry
- 5.6.1 Automotive
- 5.6.2 Industrial Manufacturing
- 5.6.3 Medical and Wellness
- 5.6.4 Aerospace
- 5.6.5 Consumer Electronics
- 5.6.6 Oil and Gas
- 5.6.7 Construction
- 5.6.8 Defense
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 United Kingdom
- 5.7.2.2 Germany
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 South Korea
- 5.7.3.5 Rest of Asia-Pacific
- 5.7.4 Middle East
- 5.7.4.1 Israel
- 5.7.4.2 Saudi Arabia
- 5.7.4.3 United Arab Emirates
- 5.7.4.4 Turkey
- 5.7.4.5 Rest of Middle East
- 5.7.5 Africa
- 5.7.5.1 South Africa
- 5.7.5.2 Egypt
- 5.7.5.3 Rest of Africa
- 5.7.6 South America
- 5.7.6.1 Brazil
- 5.7.6.2 Argentina
- 5.7.6.3 Rest of South America
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Honeywell International Inc.
- 6.4.2 Bosch Sensortec GmbH
- 6.4.3 Texas Instruments Inc.
- 6.4.4 TE Connectivity Ltd
- 6.4.5 Rockwell Automation Inc.
- 6.4.6 OMEGA Engineering inc.
- 6.4.7 STMicroelectronics N.V.
- 6.4.8 Infineon Technologies AG
- 6.4.9 NXP Semiconductors N.V.
- 6.4.10 ams OSRAM AG
- 6.4.11 Analog Devices Inc.
- 6.4.12 Renesas Electronics Corp.
- 6.4.13 Microchip Technology Inc.
- 6.4.14 ROHM Semiconductor
- 6.4.15 Omron Corp.
- 6.4.16 ABB Ltd
- 6.4.17 Sick AG
- 6.4.18 Qualcomm Technologies Inc.
- 6.4.19 Velodyne Lidar Inc.
- 6.4.20 LeddarTech Inc.
- 6.4.21 TDK Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


