

|
시장보고서
상품코드
2124028
산업용 드럼 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Industrial Drums - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 산업용 드럼 시장 규모는 2025년 146억 2,000만 달러로 평가되었고, 2026년에는 154억 1,000만 달러로 추정되고, 2026-2031년 CAGR 5.42%로 성장을 지속할 전망이며, 2031년까지 200억 6,000만 달러에 이를 것으로 예측됩니다.
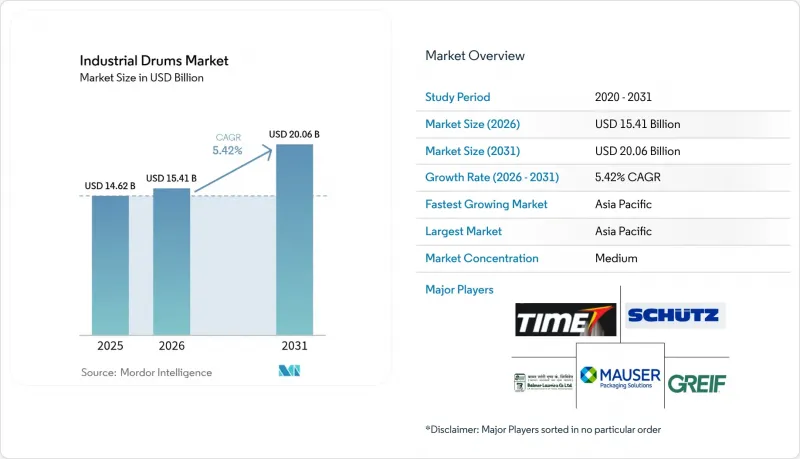
본 보고서는 소재별(스틸 드럼, 플라스틱 드럼 등), 용량별(30갤런 이하, 30-60갤런, 기타), 밀폐 유형별(타이트 헤드/클로즈드 헤드, 오픈 헤드), 최종 사용자 산업별(화학·비료, 석유·윤활유, 기타) 및 지역별(북미, 남미, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 산업용 드럼 시장 동향 및 인사이트
화학제품 및 석유화학제품 생산량 증가
중국의 특수 화학제품 생산이 견조하게 확대되고, 중동의 크래커 설비가 확장되며, 일본의 대기업 간 합병이 맞물리면서 드럼 처리량에 대한 수요가 증가하고 있습니다. 미국화학공업협회(ACC)는 물류 병목 현상이 있음에도 불구하고 미국의 화학제품 생산이 지속적인 회복력을 보이고 있다고 지적하고 있습니다. 한편, 인도는 연평균 12%의 성장률을 목표로 하고 있으며, 이에 따라 드럼 수요는 견조한 상승 추세를 유지하고 있습니다. 대규모 통합 복합 시설에서는 더 큰 배치 크기가 처리되므로, 화주들은 100갤런 이상의 용량을 가진 드럼이나 부식성이 높은 중간체를 견딜 수 있는 복합 라이닝을 채택하고 있습니다. SysKem Chemie사는 유엔 시험 기준을 충족하는 코팅 드럼만을 사용하여 클래스 8 카프릴산을 출하하고 있으며, 이는 더 높은 사양이 요구되는 추세를 여실히 보여주고 있습니다.
식품 등급 수출 물류의 확대
원자재 조달의 다양화로 인해 감미료, 식물성 단백질, 과일 농축물 공급망이 길어지고 있습니다. CDF Corporation은 2025년 2월, 미국 농무부(USDA) 기준을 준수하는 라이너를 출시하며, 오염 허용 기준의 강화에 대한 공급업체의 대응을 보여주었습니다. 코덱스 알리멘타리우스(Codex Alimentarius)에 기반한 문서 규격의 통일을 통해 여러 지역에 걸친 인증이 가능해졌으며, 이는 식품용 드럼을 대량 생산하는 제조업체의 규모의 경제를 뒷받침하고 있습니다. 고급 유기농 제품 수출업체들은 위조 방지 씰이나 QR 코드를 통해 추적성 데이터가 내장된 드럼통에 대해 추가 비용을 지불하게 되었으며, 이는 수출 대상 시장에서 원산지 표시의 신뢰성을 높이고 있습니다.
원자재 가격 변동
철강 및 수지 가격 변동으로 인해 드럼 제조업체는 고객의 가격표와 계약 내용을 일치시키는 데 어려움을 겪고 있으며, 이로 인해 이익률이 압박받고 있습니다. 라이어슨(Lyoner)사의 2025년 전망에 따르면, 아시아산 열간 압연 코일에 대해 반덤핑 관세가 부과될 가능성이 지적되고 있어 불확실성이 더욱 커지고 있습니다. 발머 로리(Balmer Rowley)사는 코일 비용 상승을 상쇄하기 위해, 기존 규격보다 4개 많은 1TEU당 80개를 적재할 수 있는 두께 0.5mm의 드럼통을 시범 도입하고 있습니다. 2024년 매출액이 233억 9,000만 루피(2억 8,080만 달러)라는 점을 고려하면, 이 비용 절감 효과는 매우 클 것으로 보입니다.
부문별 분석
정유시설 및 농약 제조업체들이 기계적 강도와 간편한 재생 주기를 선호함에 따라 철제 드럼이 46.68%로 가장 큰 점유율을 차지했습니다. 한편, 구매자들이 높은 초기 비용과 운송비 절감 효과를 저울질하는 가운데, 복합재 드럼의 점유율은 7.21% 증가세를 보이고 있습니다. 인도 항만의 최근 감사에 따르면, 수출되는 위험 화학 물질의 37%를 경량 강철 드럼이 차지하고 있어, 두께를 얇게 함으로써 비용을 절감할 수 있음이 입증되었습니다. 산업용 드럼 시장은 저합금강을 폐쇄형 자산으로 하는 전 세계 스크랩 인센티브의 혜택을 받고 있는 반면, 버진 HDPE 수지는 프로파일렌 가격 변동을 보다 직접적으로 반영하고 있습니다.
플라스틱 및 섬유 드럼은 특정 용질과의 호환성이나 중량 제한과 같은 틈새 시장 수요를 충족시키고 있습니다. 섬유 드럼은 액체에 대한 유엔(UN) 인증을 취득하지는 않았으나, 현재는 내습성 라이너가 내장되어 있어 건조 식품 분말의 유통 기한을 연장하고 있습니다. 복합 모델은 폴리머 배리어 층과 강철 리브를 결합한 것으로, 습기에 민감한 접착제 성분을 배합하는 업체를 대상으로 합니다. 이러한 모델의 부상은 산업용 드럼 시장이 단순한 소재 전환이 아닌 하이브리드화를 통해 진화하고 있음을 보여줍니다.
60-100갤런 드럼은 지게차의 통행 높이에 적합하여 35.21%의 점유율을 차지하는 주력 제품으로 자리 잡고 있습니다. 그러나 완전 자동화된 화학 플랜트에서는 처리 톤당 리프팅 횟수가 적은 110갤런 드럼이 선호됩니다. 2031년까지 100갤런을 초과하는 규격은 6.08%라는 가장 높은 성장률을 유지할 전망입니다. Camco Chemical사의 300만 달러 규모 생산 라인은 30갤런 및 110갤런 SKU를 지원하는 듀얼 충전 헤드를 갖추고 있어, 구매자들이 다양한 용량에 대한 유연성을 중요시하고 있음을 뒷받침합니다. 100갤런을 초과하는 용량의 산업용 드럼 시장 규모는 2031년까지 45억 5,000만 달러에 달할 것으로 예측되며, 이는 팔레트가 필요 없는 로봇 핸들링 셀의 보급 확대를 반영한 것입니다.
소형 드럼은 로트별 분리가 벌크 운송의 경제성을 능가하는 특수 향료, 원료의약품, 실험용 시약 등에 이용되고 있습니다. 그러나 탱크에서 충전으로 이어지는 마이크로 블렌딩 장치의 도입으로 현장의 중간 재고가 감소함에 따라 그 점유율은 축소되고 있습니다. 전반적으로 용량 선택은 인체공학적 안전성, 화물 적재 효율, 그리고 항공 운송에서 1개 포장당 허용 중량에 관한 규제적 제한 사이의 절충점을 반영합니다.
지역별 분석
아시아태평양은 중국의 크래커 프로젝트와 인도의 화학 산업 로드맵에 힘입어 2025년 매출의 39.55%를 차지했습니다. 발마 로리(Balmer Rowley)는 8개의 공장을 활용하여 농약 수출업체를 위한 국가 계약을 수주하고, 233억 9,000만 루피(2억 8,080만 달러)의 매출을 기록했습니다. 지역 정부는 정유시설 회랑에 인접한 포장 클러스터에 대해 토지세 환급 조치를 시행하고 있으며, 이로 인해 납기 기간이 단축되고 찌그러짐으로 인한 손상도 감소하고 있습니다.
북미는 셰일 유래 원료의 혜택을 받고 있으며, 엄격한 DOT(미국 교통부) 감독 체제를 유지하고 있어 고사양 스틸 드럼에 대한 수요가 증가하고 있습니다. 커민스의 리터너블 시스템은 미국의 OEM 각사가 순환형 경제의 이점을 얻기 위해 포장을 내부화하고 있는 실제 사례를 보여줍니다. 유럽에서는 ‘포장 및 포장 폐기물 규정’에 기반한 순환 경제 준수가 중시되고 있으며, 2023년 이후 주로 식품 및 퍼스널케어용 원료를 대상으로 한 시범 임대 풀이 3배로 증가했습니다. 남미, 중동 및 아프리카는 규모는 작지만 여전히 고성장 거점으로 자리 잡고 있습니다. 브라질의 바이오디젤 수출업체들은 대두유의 산화를 억제하기 위해 복합재 드럼으로의 전환을 추진하고 있는 반면, 걸프 지역의 석유화학 허브에서는 극한의 주변 온도를 견딜 수 있도록 두꺼운 강철 드럼을 조달하고 있습니다. 지역 간 화물 차익 거래 또한 귀환편을 통한 드럼 재생 네트워크를 활성화시켜, 산업용 드럼 시장에서의 세계 연계를 강화하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the industrial drums market size is expected to grow from USD 14.62 billion in 2025 to USD 15.41 billion in 2026 and is forecast to reach USD 20.06 billion by 2031 at 5.42% CAGR over 2026-2031.
This report is Segmented by Material (Steel Drum, Plastic Drum, and More), Capacity (Up To 30 Gallons, 30-60 Gallons, and More), Closure Type (Tight-Head/Closed-Head, and Open-Head), End-User Industry (Chemicals and Fertilizers, Petroleum and Lubricants, and More), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Drums Market Trends and Insights
Growth in Chemical and Petrochemical Output
Robust specialty-chemical builds in China, cracker expansions in the Middle East, and mergers among Japanese majors collectively increase drum throughput requirements. The American Chemistry Council notes sustained resilience in U.S. chemical production despite logistics bottlenecks, while India is targeting 12% compound growth, which keeps drum demand firmly on an upward path. Larger integrated complexes process greater batch sizes, pushing shippers toward 100-plus gallon formats and composite linings that withstand aggressive intermediates. SysKem Chemie ships Class 8 caprylic acid exclusively in coated drums that meet United Nations test codes, illustrating the higher specification trend.
Expansion of Food-Grade Export Logistics
Diversification of ingredient sourcing has lengthened supply chains for sweeteners, plant proteins, and fruit concentrates. CDF Corporation launched USDA-compliant liners in February 2025, showing suppliers' response to stricter contamination thresholds. Harmonized documentation under the Codex Alimentarius enables multi-regional certification, supporting scale economies for manufacturers producing food-grade drums in bulk. Premium organic exporters have begun to pay price differentials for drums embedded with tamper-evident seals and QR-code lineage data, enhancing provenance claims in destination markets.
Raw-Material Price Volatility
Steel and resin swings squeeze margins as drum makers struggle to synchronize contracts with customer price lists. Ryerson's 2025 forecast flags potential anti-dumping duties on Asian hot-rolled coil, adding another layer of unpredictability. Balmer Lawrie is piloting 0.5 mm-wall drums that allow 80 units per TEU, four more than traditional gauges, to offset rising coil costs; at INR 23.39 billion (USD 280.8 million) 2024 sales, the savings are material.
Other drivers and restraints analyzed in the detailed report include:
- Strengthening Supply-Chain Resiliency Needs
- Regulatory Phase-Out of Single-Use Bulk Bags
- Cannibalization by IBCs and Flexitanks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Steel captured the lion's share at 46.68% because refinery and agrochemical players favor its mechanical strength and straightforward reconditioning loops. At the same time, composite drums are on a 7.21% trajectory as buyers weigh freight savings against initial premiums. Recent audits at Indian ports show that lightweight steel accounted for 37% of outbound haz-chem shipments, underscoring cost reductions from thinner gauges. The industrial drums market benefits from global scrap incentives that make low-alloy steel a closed-loop asset, whereas virgin HDPE resin tracks propylene prices more closely.
Plastic and fiber variants address niche solute compatibility or weight constraints. Although fiber units lack UN credentials for liquids, they now incorporate moisture-resistant liners that extend shelf life for dry food powders. Composite models combine polymer barriers with steel ribs, targeting formulators of moisture-sensitive adhesive ingredients. Their rise illustrates how the industrial drums market evolves through hybridization rather than a binary material switch.
Sixty-to-one-hundred-gallon drums align with forklift clearance and remain the workhorse at 35.21% share. However, fully automated chemical clusters prefer 110-gallon drums that support fewer lifts per ton processed. Through 2031, above-100-gallon formats hold the fastest 6.08% expansion rate. Camco Chemical's USD 3 million line allows dual fill heads for 30 and 110 gallon SKUs, underlining buyers' preference for multi-volume flexibility. The industrial drums market size for capacities beyond 100 gallons is projected to touch USD 4.55 billion by 2031, reflecting wider adoption of palletless robotic handling cells.
Smaller drums serve specialty flavors, pharma actives, and lab reagents where lot segregation trumps bulk economics. Yet their share erodes as tank-to-fill micro-blending units shrink on-site intermediate inventories. Overall, capacity choice mirrors a trade-off between ergonomic safety, freight utilization, and regulatory caps on allowable mass per package in airborne routes.
Complete Report Scope:
- By Material
- Steel Drum
- Plastic Drum
- Fiber Drum
- Composite/Hybrid Drum
- By Capacity
- Up to 30 Gallons
- 30 - 60 Gallons
- 60 - 100 Gallons
- Above 100 Gallons
- By Closure Type
- Tight-Head / Closed-Head
- Open-Head
- By End-user Industry
- Chemicals and Fertilizers
- Petroleum and Lubricants
- Food and Beverage
- Pharmaceuticals
- Paints, Coatings and Adhesives
- Building and Construction
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific contributed 39.55% revenue in 2025, propelled by Chinese cracker projects and India's chemicals roadmap. Balmer Lawrie leveraged eight plants to secure national contracts for agrochemical exporters and logged INR 23.39 billion (USD 280.8 million) turnover. Regional governments offer land rebates for packaging clusters adjacent to refinery corridors, shortening delivery lead times and reducing dent damage.
North America benefits from shale-based feedstock and maintains stringent DOT oversight that drives demand for high-specification steel drums. Cummins' returnable system illustrates how U.S. OEMs internalize packaging for circularity gains. Europe emphasizes circular economy compliance under the Packaging and Packaging Waste Regulation and has seen pilot leasing pools triple since 2023, mostly for food and personal-care ingredients. South America and the Middle East and Africa remain smaller but high-growth nodes. Brazilian biodiesel exporters pivot to composite drums to mitigate soy-oil oxidation, whereas Gulf petrochemical hubs procure thick-gauge steel variants to withstand extreme ambient temperatures. Cross-regional freight arbitrage also stimulates backhaul drum reconditioning networks, reinforcing global linkages within the industrial drums market.
- Greif, Inc.
- Mauser Packaging Solutions Holding Company
- SCHUTZ GmbH & Co. KGaA
- Time Technoplast Ltd.
- Balmer Lawrie & Co. Ltd.
- Sicagen India Ltd.
- TPL Plastech Ltd.
- Peninsula Drums (Pty) Ltd.
- Eagle Manufacturing Company (Justrite Safety Group)
- U.S. Coexcell Inc.
- Industrial Container Services, Inc.
- Hoover Ferguson Group, Inc.
- Berry Global Group, Inc.
- Brambles Ltd.
- Myers Industries, Inc.
- Orlando Drum & Container Corp.
- Rahway Steel Drum Co., Inc.
- Re-Gen Drums Ltd.
- Palm Containers (Pty) Ltd.
- Schutz DSL (Asia) Pte Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in chemical and petrochemical output
- 4.2.2 Expansion of food-grade export logistics
- 4.2.3 Strengthening supply-chain resiliency needs
- 4.2.4 Regulatory phase-out of single-use bulk bags
- 4.2.5 Circular-economy leasing and re-conditioning models
- 4.2.6 RFID-enabled drum tracking for haz-mat compliance
- 4.3 Market Restraints
- 4.3.1 Raw-material price volatility
- 4.3.2 Environmental compliance cost for disposal
- 4.3.3 Cannibalization by IBCs and flexitanks
- 4.3.4 On-site micro-blending cutting drum demand
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Intensity of Competitive Rivalry
- 4.7.5 Threat of Substitutes
- 4.8 The Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Steel Drum
- 5.1.2 Plastic Drum
- 5.1.3 Fiber Drum
- 5.1.4 Composite/Hybrid Drum
- 5.2 By Capacity
- 5.2.1 Up to 30 Gallons
- 5.2.2 30 - 60 Gallons
- 5.2.3 60 - 100 Gallons
- 5.2.4 Above 100 Gallons
- 5.3 By Closure Type
- 5.3.1 Tight-Head / Closed-Head
- 5.3.2 Open-Head
- 5.4 By End-user Industry
- 5.4.1 Chemicals and Fertilizers
- 5.4.2 Petroleum and Lubricants
- 5.4.3 Food and Beverage
- 5.4.4 Pharmaceuticals
- 5.4.5 Paints, Coatings and Adhesives
- 5.4.6 Building and Construction
- 5.4.7 Other End-user Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Kenya
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Greif, Inc.
- 6.4.2 Mauser Packaging Solutions Holding Company
- 6.4.3 SCHUTZ GmbH & Co. KGaA
- 6.4.4 Time Technoplast Ltd.
- 6.4.5 Balmer Lawrie & Co. Ltd.
- 6.4.6 Sicagen India Ltd.
- 6.4.7 TPL Plastech Ltd.
- 6.4.8 Peninsula Drums (Pty) Ltd.
- 6.4.9 Eagle Manufacturing Company (Justrite Safety Group)
- 6.4.10 U.S. Coexcell Inc.
- 6.4.11 Industrial Container Services, Inc.
- 6.4.12 Hoover Ferguson Group, Inc.
- 6.4.13 Berry Global Group, Inc.
- 6.4.14 Brambles Ltd.
- 6.4.15 Myers Industries, Inc.
- 6.4.16 Orlando Drum & Container Corp.
- 6.4.17 Rahway Steel Drum Co., Inc.
- 6.4.18 Re-Gen Drums Ltd.
- 6.4.19 Palm Containers (Pty) Ltd.
- 6.4.20 Schutz DSL (Asia) Pte Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


