

|
시장보고서
상품코드
2124045
스마트 온실 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Smart Greenhouse - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
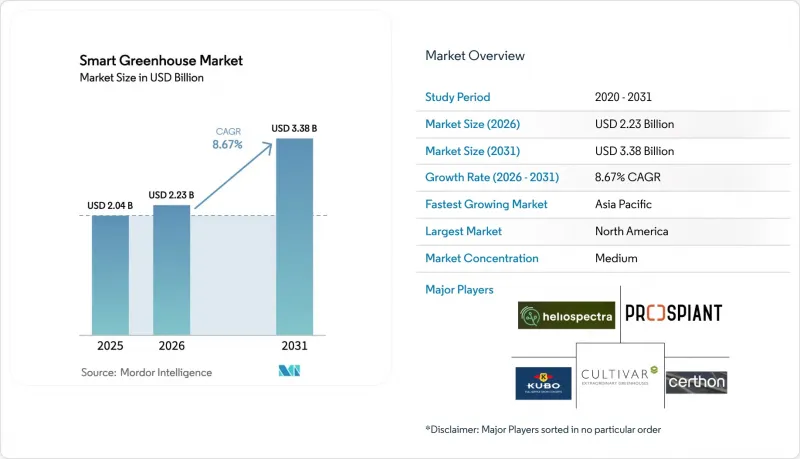
에 의하면, 스마트 온실 시장 규모는 2025년에 20억 4,000만 달러로 평가되었고, 2026년 22억 3,000만 달러에서 2031년까지 33억 8,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 8.67%를 나타낼 전망입니다.
본 보고서는 유형별(수경 재배, 비수경 재배), 기술별(LED 재배용 조명, HVAC 및 기후 제어, 자재관리 및 로봇 공학, 제어 시스템 및 분석 플랫폼, 기타), 제공 형태별(하드웨어, 소프트웨어, 서비스), 최종 사용자별(상업 재배자, 연구·학술 기관, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 스마트 온실 시장 동향 및 인사이트
제어 환경 농업에서의 IoT 및 AI의 급속한 통합
엣지 처리된 센서 데이터를 통해 1분 이내에 기후 조절이 가능해져, 작물의 스트레스 발생과 노동 투입을 대폭 줄이고 있습니다. 2025년부터 운영되고 있는 Argus Control Systems사의 Axia 플랫폼은 온프레미스 분석이 네트워크 지연 및 에너지 피크 부하를 어떻게 줄이는지 입증하고 있습니다. Priva사의 ‘Connected’ 도입 시설은 2025년 말까지 500곳 이상의 상업시설에 달하며, 기상 기반 예측과 비료·관개 알고리즘을 결합하여 물 사용량을 30% 절감하고 있습니다. 국제에너지기구(IEA)는 2025년 평가 보고서에서 AI를 활용한 최적화를 통해 온실가스 배출량을 15-25% 감축할 수 있다고 산출했습니다. 이러한 성과가 나오는 한편, 사이버 보안에 대한 인식도 높아지고 있습니다. 2025년 IEEE의 조사에 따르면, 암호화되지 않은 센서 게이트웨이가 위험 요인으로 증가하고 있는 것으로 지적되었습니다. 생산자들은 현재 운영 기술(OT) 네트워크를 세분화하고 ISO 27001에 기반한 관리 조치를 도입하고 있으며, 이를 통해 데이터 중심 플랫폼의 장기적인 매력이 강화되고 있습니다.
무농약 농산물에 대한 수요 증가
미국, 독일, 프랑스의 소매 바이어들은 잔류물 검사 대상이 확대됨에 따라 무농약 인증을 우선시하고 있습니다. 통제 환경 농업은 토양 유래 병원균을 사실상 제거할 수 있어, 2030년까지 화학 농약 사용량을 절반으로 줄이겠다는 유럽연합(EU)의 지침과 부합합니다. 유엔 식량농업기구(FAO)는 2024년 기술 노트에서 수경 재배된 상추, 토마토, 딸기의 농약 잔류량이 거의 제로임을 확인했습니다. 슈퍼마켓은 온실 채소를 프리미엄 상품으로 포지셔닝함으로써 해당 카테고리의 이익률을 개선하고 있으며, 노지 재배의 동급 제품에 비해 20-40%의 가격 인상을 실현하고 있습니다. 파머스 마켓이 적은 도시 지역에서는 이러한 추세가 더욱 가속화되고 있으며, 광범위한 인플레이션 압력에도 불구하고 프리미엄 가격의 탄력성이 유지되고 있습니다.
스마트 시설의 높은 초기 투자 비용
HVAC(공조·환기·냉난방), LED 조명, 비료 공급 및 관개, 분석 시스템을 포함하면 완전 자동화된 스마트 온실의 건설비는 1제곱미터당 최대 1,500달러에 달할 전망입니다. 회수 기간이 7년을 초과하는 신흥 시장에서는 기존 금융 기관들이 대출에 소극적입니다. 국제금융공사(IFC)는 리스 투 오너(Lease-to-Owner) 계약이나 수익 분배형 구조를 대안으로 제시했으나, 이를 뒷받침할 법적 체계는 여전히 불충분하다고 지적하고 있습니다. 에너지 집약도 역시 추가적인 불확실성을 야기하고 있는데, 온대 지역에서는 1헥타르당 연간 300 MWh의 전력을 소비하는 경우도 있어, 생산자들은 변동이 심한 요금 체계의 영향을 받기 쉽습니다.
부문 분석
2025년, 수경 재배 시스템이 스마트 온실 시장 점유율의 57.23%를 차지했습니다. 이는 사막이나 지중해성 기후에서 관개용수의 최대 90%를 재활용할 수 있는 능력을 반영한 것입니다. 중동 및 남유럽의 보조금 제도를 배경으로, 수경 재배 시스템을 활용한 스마트 온실 시장 규모는 2031년까지 연평균 성장률(CAGR) 9.79%로 확대될 것으로 예측됩니다. 네타핌(Netafim)사의 보고에 따르면, 2025년 말 기준 전 세계 수경재배 도입 면적은 12,000헥타르에 달했으며, 특히 물값이 1m³당 2달러를 초과하는 아랍에미리트(UAE)에서는 급속히 보급되고 있습니다. 한편, 유기농 인증을 받은 농장이나 토양 미생물 군집을 분석하는 연구 기관에서는 여전히 토양 재배나 하이브리드 방식이 채택되고 있지만, 이러한 방식에서는 수작업에 의한 제초 및 해충 방제에 드는 비용이 높습니다. 뿌리를 영양분 미스트 속에 띄우는 에어로포닉스는 25%의 추가적인 절수 효과가 기대되지만, 설비의 복잡성과 높은 전력 소비량으로 인해 여전히 틈새 시장 수준에 머물러 있습니다.
수경 재배의 보급은 규제 부담 경감이라는 혜택도 누리고 있습니다. 유럽연합(EU)의 ‘농약의 지속 가능한 사용에 관한 지침’에 따라, 폐쇄형 영양분 시스템은 토양 재배에 비해 보고 의무가 간소화되어 규정 준수 비용을 절감할 수 있습니다. 이와 동시에, 에어로포닉스 및 아쿠아포닉스 스타트업에 대한 벤처 캐피털 투자액은 2025년에 2억 달러를 넘어섰으며, 이는 물을 주축으로 하는 재배 방식이 고밀도 도시 생산의 다음 물결을 뒷받침할 것이라는 투자자들의 확신을 보여줍니다.
2025년에는 LED 재배용 조명이 기술 매출의 38.56%를 차지했지만, 2031년까지 가장 강력한 성장은 제어 시스템과 분석 플랫폼에서 비롯될 것으로 보이며, 연평균 성장률(CAGR)은 10.31%로 예측됩니다. 생산자들이 해충 조사, 일기 예보, 에너지 관리를 디지털화함에 따라 의사결정 지원 소프트웨어와 관련된 스마트 온실 시장 규모는 확대되고 있습니다. Priva사의 ‘Blue ID’ 컨트롤러는 기후 센서, 비료 주입 펌프, 스마트 계량기를 단일 대시보드에 통합하여, 네덜란드에서 실시된 시험에서 병해로 인한 작물 손실을 18% 감소시켰습니다. 한편, 시그니파이(Signify)의 파장 조절이 가능한 LED는 와헤닝겐 대학의 시험에서 토마토 수확량을 12% 향상시켜, 하드웨어가 지속적이고 점진적인 영향을 미치고 있음을 보여주었습니다. 모종 심기 및 수확을 위한 로봇 기술은 여전히 실증 단계에 있지만, 로봇 1대당 단가가 4만 5,000달러 미만으로 떨어지면 인력 감축이 기대됩니다.
또한 MQTT나 OPC-UA와 같은 표준화된 통신 프로토콜을 채택하는 추세가 보입니다. 이를 통해 서로 다른 유형의 센서, HVAC 드라이브, 조명 어레이를 플러그 앤 플레이 방식으로 통합할 수 있게 됩니다. 상호 운용성이 향상됨에 따라 경쟁 우위는 개별 구성 요소에서 데이터 루프 전체의 통합성으로 이동하고 있으며, 견고한 분석 제품군의 중요성이 더욱 커지고 있습니다.
지역별 분석
아시아태평양은 중국 도시 근교에 위치한 스마트 온실을 위한 100억 위안 규모의 보조금 프로그램의 뒷받침을 받아, 2031년까지 연평균 성장률(CAGR) 10.53%로 전 세계 시장 성장을 주도할 전망입니다. 일본에서는 대도시권 주변에 설치된 플랜트 팩토리를 통해 국내 상추 수요의 15%를 충당하고 있으며, 인도에서는 ‘국가 원예 미션’을 통해 폴리하우스(비닐하우스) 개조를 장려하고 있습니다.
2025년 매출의 34.79%를 차지한 것으로 평가된 북미는 대마초 합법화와 지역산 채소를 선호하는 소비자 경향의 혜택을 받고 있습니다. 미국 농무부는 2022-2025년 제어 환경 하에서의 재배 면적이 18% 증가했다고 보고했습니다. 캐나다의 5,000만 캐나다 달러(3,700만 달러) 규모의 ‘온실 혁신 기금’은 2030년까지 천연가스 사용량을 25% 감축하는 것을 목표로 하는 열회수 시스템 개조를 지원하고 있습니다.
유럽의 성숙한 공급망은 네덜란드를 중심으로 전개되고 있으며, 이 나라는 2024년에 92억 유로(101억 달러) 상당의 온실 재배 농산물을 수출했습니다. 2025년 이후의 에너지 가격 변동으로 인해 지열 우물 및 축열 대수층의 도입이 가속화되었습니다. 남미의 성장은 완만하지만, 불안정한 강우에 직면한 브라질과 아르헨티나의 사업자들이 주도적인 역할을 하고 있습니다. 중동 및 아프리카는 여전히 규모는 작지만 전략적으로 매우 중요합니다. 사우디아라비아 국립농업기술센터는 농산물 1kg당 물 사용량을 5리터 미만으로 줄이기 위해, 태양광 발전 기반의 해수 담수화 시스템을 도입한 온실의 시범 운영을 진행하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the smart greenhouse market size was valued at USD 2.04 billion in 2025 and is estimated to grow from USD 2.23 billion in 2026 to reach USD 3.38 billion by 2031, at a CAGR of 8.67% during the forecast period (2026-2031).
This report is Segmented by Type (Hydroponic, and Non-Hydroponic), Technology (LED Grow Lights, HVAC and Climate Control, Material Handling and Robotics, Control Systems and Analytics Platforms, and Others), Offering (Hardware, Software, and Services), End-User (Commercial Growers, Research and Academic Institutes, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Smart Greenhouse Market Trends and Insights
Rapid IoT and AI Integration in Controlled-Environment Agriculture
Edge-processed sensor data now enables sub-minute climate adjustments, materially lowering crop-stress episodes and labour inputs. Argus Control Systems' Axia platform, operational since 2025, demonstrates how on-premises analytics reduce network latency and energy peaks. Priva's Connected installations surpassed 500 commercial sites by late 2025, combining weather-based forecasting with fertigation algorithms that cut water use by 30%. The International Energy Agency quantified a 15-25% greenhouse gas energy saving from AI-driven optimization in its 2025 assessment. These gains arrive alongside rising cybersecurity awareness; an IEEE study in 2025 highlighted unencrypted sensor gateways as a growing risk vector. Growers now segment operational-technology networks and adopt ISO 27001 controls, strengthening the long-term attractiveness of data-centric platforms.
Escalating Demand for Pesticide-Free Produce
Retail buyers in the United States, Germany, and France are prioritizing pesticide-free certification as residue-testing coverage widens. Controlled-environment agriculture can virtually eliminate soil-borne pathogens, aligning with the European Union mandate to halve chemical pesticide application by 2030. The Food and Agriculture Organization confirmed near-zero pesticide profiles for hydroponic lettuce, tomato, and strawberry crops in its 2024 technical note. Supermarkets refine category margins by positioning greenhouse vegetables as premium, gaining 20-40% price uplift versus field-grown equivalents. Urban centers where farmers' markets are scarce further accelerate this trend, sustaining premium elasticity despite broader inflationary pressure.
High Upfront Capital Expenditure for Smart Facilities
Fully automated smart greenhouses cost as much as USD 1,500 per square meter once HVAC, LEDs, fertigation, and analytics are included. Traditional lenders hesitate in emerging markets where payback periods stretch beyond seven years. The International Finance Corporation highlighted lease-to-own contracts and revenue-sharing structures as alternate pathways but noted that supportive legal frameworks remain patchy. Energy intensity adds further uncertainty; a temperate-zone hectare may draw 300 MWh annually, exposing growers to volatile tariff regimes.
Other drivers and restraints analyzed in the detailed report include:
- Population-Driven Food-Supply Gap
- Urban-Centric Vertical-Farming Investments
- Scarcity Of Greenhouse-Automation Talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hydroponic configurations accounted for 57.23% of the smart greenhouse market share in 2025, reflecting their ability to recycle up to 90% of irrigation water in desert and Mediterranean climates. The smart greenhouse market size for hydroponic systems is projected to widen at a 9.79% CAGR through 2031 on the back of subsidies in the Middle East and Southern Europe. Netafim reported 12,000 hectares of hydroponic deployments worldwide by the end of 2025, with particularly swift uptake in the United Arab Emirates where water costs exceed USD 2 per m3. Soil-based and hybrid models persist in organic-certified farms and research institutes analyzing soil microbiomes, yet they incur higher hand-weeding and pest-management bills. Aeroponics, which suspends roots in nutrient mist, promises an incremental 25% water saving but remains niche due to equipment complexity and elevated power draw.
Hydroponic adoption also benefits from reduced regulatory burden. Under the European Union Sustainable Use of Pesticides Directive, closed-loop nutrient systems enjoy simplified reporting obligations compared with soil cultivation, trimming compliance costs. In parallel, venture capital directed toward aeroponic and aquaponic start-ups exceeded USD 200 million in 2025, signalling investor confidence that water-centric formats will underpin the next wave of high-density urban production.
LED grow lights captured 38.56% of technology revenue in 2025, yet the strongest growth to 2031 will stem from control systems and analytics platforms, projected at 10.31% CAGR. The smart greenhouse market size attached to decision-support software has expanded as growers digitize pest-scouting, weather forecasting, and energy management. Priva's Blue ID controller links climate sensors, fertigation pumps, and smart meters under a single dashboard and trimmed disease-related crop loss by 18% in Dutch trials. Meanwhile, Signify's tuneable-spectrum LEDs lifted tomato yields by 12% in Wageningen University tests, illustrating hardware's continual but incremental impact. Robotics for transplanting and harvesting remain at pilot stage yet promise labour savings once unit costs fall below USD 45,000 per robot.
A convergent trend sees growers embracing standardized communication protocols such as MQTT and OPC-UA, which allow plug-and-play integration of disparate sensors, HVAC drives, and lighting arrays. As interoperability grows, the competitive edge shifts from individual components to the cohesiveness of the full data loop, reinforcing the premium placed on robust analytics suites.
Complete Report Scope:
- By Type
- Hydroponic
- Non-Hydroponic (Soil-Based and Others)
- By Technology
- LED Grow Lights
- HVAC and Climate Control
- Material Handling and Robotics
- Control Systems and Analytics Platforms
- Other Technologies
- By Offering
- Hardware
- Software
- Services (Integration, Maintenance, Training)
- By End-User
- Commercial Growers
- Research and Academic Institutes
- Retail/Community Gardens
- Urban/Vertical Farms
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia Pacific will pace global expansion with a 10.53% CAGR to 2031, propelled by China's CNY 10 billion subsidy program for peri-urban smart greenhouses. Japan supplies 15% of domestic lettuce demand via plant factories situated within metropolitan rings, while India incentivizes polyhouse upgrades through the National Horticulture Mission.
North America, holding 34.79% revenue in 2025, benefits from cannabis legalization and consumer preference for locally grown vegetables. The United States Department of Agriculture documented an 18% uptick in controlled-environment acreage from 2022-2025. Canada's CAD 50 million (USD 37 million) Greenhouse Innovation Fund supports heat-recovery retrofits aimed at cutting natural-gas use by 25% by 2030.
Europe's mature supply chains center on the Netherlands, which exported EUR 9.2 billion (USD 10.1 billion) in greenhouse produce during 2024. Energy-price volatility after 2025 accelerated the adoption of geothermal wells and heat-storage aquifers. South America's growth is moderate, led by Brazilian and Argentine operators battling erratic rainfall. The Middle East and Africa remain smaller yet strategically vital: Saudi Arabia's National Center for Agriculture Technologies is piloting solar-desalination greenhouses to cut water usage below 5 L kg-1 of produce.
- Heliospectra AB
- Prospiant Inc.
- Cultivar Greenhouse Ltd
- Kubo Greenhouse Projects BV
- Certhon Group
- Argus Control Systems Ltd
- Netafim Ltd
- Sensaphone Inc.
- Luiten Greenhouses
- Agra Tech Inc.
- Greenhouse Megastore (BFG Supply)
- Logiqs B.V.
- Priva Holding BV
- Nexus Corporation
- Greentech Agro LLC
- Ridder Group
- Motorleaf
- Autogrow Systems Ltd
- Signify N.V.
- LumiGrow Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid IoT and AI Integration in Controlled-Environment Agriculture
- 4.2.2 Escalating Demand for Pesticide-Free Produce
- 4.2.3 Population-Driven Food-Supply Gap
- 4.2.4 Urban-Centric Vertical-Farming Investments
- 4.2.5 Solar-Powered Greenhouse Micro-Grids Slash Operating Costs
- 4.2.6 Carbon-Credit Programmes Rewarding CEA Efficiency
- 4.3 Market Restraints
- 4.3.1 High Upfront Capital Expenditure for Smart Facilities
- 4.3.2 Scarcity of Greenhouse-Automation Talent
- 4.3.3 Battery-Supply Volatility for Off-Grid Systems
- 4.3.4 Edge-Device Cybersecurity Vulnerabilities
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Hydroponic
- 5.1.2 Non-Hydroponic (Soil-Based and Others)
- 5.2 By Technology
- 5.2.1 LED Grow Lights
- 5.2.2 HVAC and Climate Control
- 5.2.3 Material Handling and Robotics
- 5.2.4 Control Systems and Analytics Platforms
- 5.2.5 Other Technologies
- 5.3 By Offering
- 5.3.1 Hardware
- 5.3.2 Software
- 5.3.3 Services (Integration, Maintenance, Training)
- 5.4 By End-User
- 5.4.1 Commercial Growers
- 5.4.2 Research and Academic Institutes
- 5.4.3 Retail/Community Gardens
- 5.4.4 Urban/Vertical Farms
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Nigeria
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Heliospectra AB
- 6.4.2 Prospiant Inc.
- 6.4.3 Cultivar Greenhouse Ltd
- 6.4.4 Kubo Greenhouse Projects BV
- 6.4.5 Certhon Group
- 6.4.6 Argus Control Systems Ltd
- 6.4.7 Netafim Ltd
- 6.4.8 Sensaphone Inc.
- 6.4.9 Luiten Greenhouses
- 6.4.10 Agra Tech Inc.
- 6.4.11 Greenhouse Megastore (BFG Supply)
- 6.4.12 Logiqs B.V.
- 6.4.13 Priva Holding BV
- 6.4.14 Nexus Corporation
- 6.4.15 Greentech Agro LLC
- 6.4.16 Ridder Group
- 6.4.17 Motorleaf
- 6.4.18 Autogrow Systems Ltd
- 6.4.19 Signify N.V.
- 6.4.20 LumiGrow Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


