

|
시장보고서
상품코드
2124061
푸마르산 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Fumaric Acid - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
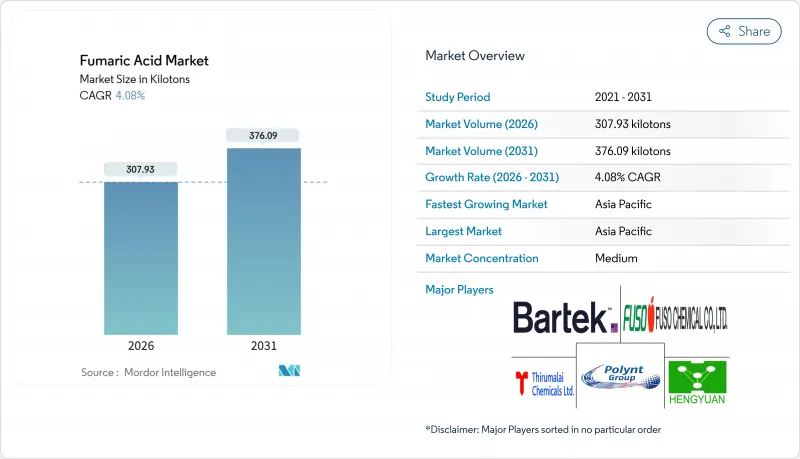
에 의하면, 푸마르산 시장 규모는 2026년에 307.93 킬로톤으로 추정되고 있어 예측 기간(2026-2031년)에서 CAGR 4.08%로 성장을 지속하여, 2031년까지 376.09 킬로톤에 이를 전망입니다.
본 보고서는 등급(식품 등급 및 기술 등급), 용도(식품 및 음료 가공, 불포화 폴리에스터 수지 등), 최종 사용자 산업(화학, 식품 및 음료 등), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 수량(톤) 단위로 제시되어 있습니다.
세계 푸마르산 시장 동향 및 인사이트
아시아 편의식품 시장에서 바이오 발효 푸마르산에 대한 ‘클린 라벨’ 수요
원재료 표시에 대한 소비자의 엄격한 시선이 일본, 한국, 중국에서 산미료의 조달 형태를 변화시키고 있습니다. 2024년 4월에 시행된 일본의 ‘식품위생법’ 개정에 따라 합성 첨가물의 명시적 표기가 의무화되어, 편의점 체인들 사이에서 배합 변경의 물결이 일고 있습니다. 또한, 2024년 11월에 발표된 한국의 가이드라인에서는 생산자에게 제조 경로의 공개를 권장하고 있으며, 이로 인해 발효 유래 원료에 대한 수요가 더욱 촉진되고 있습니다. 옌타이 헝위안(煙台恒源)이나 창마오 생화(長茂生化)와 같은 중국 기업들은 2024년부터 2025년까지 추정 1만 5,000톤의 바이오 생산 능력을 확충하여, 식품 등급 바이오 원료에 기존에 적용되던 25%의 가격 프리미엄을 2025년까지 약 12% 수준으로 축소시켰습니다. 아세안(ASEAN) 국가들의 중산층 소득 증가도 유사한 추세를 보일 것으로 예상되어, 해당 지역에서의 채택이 확대될 전망입니다.
경량화를 추구하는 전기차(EV) 및 풍력 발전용 블레이드의 복합재료에서 불포화 폴리에스테르 수지로의 전환
현재 전기차(EV) 플랫폼에는 약 450파운드의 플라스틱 및 복합재료가 사용되고 있는데, 이는 내연기관(ICE) 차량의 310파운드에 비해 증가한 수치이며, 이 차이는 주로 중량 증가를 상쇄하기 위한 배터리 질량에 기인합니다. 2025년 모든 차종의 CO2 배출량 목표 달성을 목표로 하는 유럽 자동차 제조업체들은 푸마르산계 공중합체를 8%-12% 함유한 유리섬유 강화 UPR(불포화 폴리에스테르 수지) 부재를 지정하고 있습니다. 마찬가지로, 해상 풍력 발전 프로젝트에서도 길이가 80미터를 초과하는 블레이드의 경우 피로 저항성 향상이 필수적이기 때문에 푸마르산 개질 UPR이 선호되고 있습니다. 한편, 고급차 부문에서는 탄소섬유 프리프레그나 바이오 에폭시계 소재로의 전환이 진행되고 있지만, 대중 시장용 전기차(EV) 수요가 전체 시장을 견인하고 있어 생산량이 지속적으로 증가할 것으로 전망됩니다.
말레산 무수물 원료 및 벤젠 현물 가격 변동
2024년부터 2025년까지 중국의 말레산 무수물 현물 가격은 벤젠 가격의 변동을 반영하여 톤당 1,050달러에서 1,400달러 사이에서 급등락했습니다. 2024년 1분기, 벤젠 가격이 톤당 7,200위안을 일시적으로 상회했을 때, 중국의 몇몇 소규모 푸마르산 생산 업체들은 생산 설비를 가동 중단했습니다. 유럽의 사업자들은 벤젠 가격 변동 외에도 2024년에 1MWh당 평균 35-45유로에 달한 천연가스 가격 급등이라는 이중고에 직면했습니다. 장기 말레산 계약을 체결하지 않은 생산 업체들은 안정적인 이익률을 확보하는 데 어려움을 겪고 있으며, 이는 수직 통합 및 포트폴리오 다각화를 촉진하고 있습니다.
부문 분석
2025년, 푸마르산 시장 중 식품용 등급이 66.28%를 차지하며, 2031년까지 연평균 성장률(CAGR) 4.51%로 성장할 전망입니다. 발텍(Bartech)사의 신규 생산 라인은 식품용 등급 생산에 전적으로 특화되어 있어, 수익성이 높고 규제가 엄격한 분야에 전략적으로 중점을 두고 있음을 알 수 있습니다. UPR 및 알키드 수지와 밀접하게 관련된 테크니컬 등급 수요는 CBAM(탄소 국경 조정 조치) 비용과 말레산 원료 가격 변동으로 인해 성장세가 주춤하고 있지만, 건설용 및 자동차용 도료 시장에서는 여전히 필수적인 존재입니다.
바이오 발효 기술의 발전으로 인해, 기존 20-25%였던 가격 프리미엄은 2025년까지 12-15%로 축소될 전망이며, 가격에 민감한 신흥 시장의 잠재 수요가 확대되고 있습니다. BASF는 자사의 CO2 네거티브 공정이 2027년까지 상용화될 준비가 될 것으로 전망하고 있으며, 이로 인해 식품 첨가물의 탄소 공개 체계가 재정의될 가능성이 있습니다. 이중 사양의 공장을 보유한 생산자는 각 부문의 가격 변동을 완화하기 위해 등급을 전환할 수 있으며, 이러한 헤지 기법은 통합형 화학 제조업체들 사이에서 점점 더 선호되고 있습니다.
지역별 분석
아시아태평양은 2025년에 전 세계 생산량의 60.21%를 차지할 것으로 보이며, 2031년까지 연평균 성장률(CAGR) 4.88%를 기록할 전망입니다. 중국 한 나라만으로도 전 세계 생산 능력의 대부분을 차지하고 있으며, 산동성, 허베이성, 장쑤성에 생산 거점이 집중되어 있을 뿐만 아니라, 바이오 발효 플랜트의 점유율도 확대되고 있습니다. 인도는 의약품 및 식품 등급 수요에 부응하기 위해 생산량을 확대하고 있는 반면, 일본과 한국은 엄격한 순도 기준을 준수하는 수입에 의존하고 있습니다. 아세안(ASEAN) 국가들, 특히 베트남과 태국은 도시 지역의 소득 증가가 편의식 확산을 뒷받침하는 가운데 새로운 수요 거점으로 부상하고 있습니다.
북미에서는 바르텍(Bartec)사의 생산 능력이 두 배로 증가한 혜택을 누리고 있으며, 이 지역은 바이오 등급 소재의 순수출 지역으로서의 위상을 확립하고 있습니다. 유럽에서는 CBAM(탄소 국경 조정 조치)에 대응하여 공급망 재구성이 진행되고 있습니다. 독일, 프랑스, 이탈리아가 주요 소비 거점으로 자리 잡고 있으며, 지역 수지 제조업체들은 저탄소 원료 인증 획득을 추진하고 있습니다. EFSA(유럽식품안전청)의 사료 첨가물에 대한 긍정적인 평가로 인해 유럽의 잠재 시장 규모는 더욱 확대되고 있습니다.
남미, 중동 및 아프리카를 합쳐도 세계 수요에서 차지하는 비중은 낮은 임베디드니다. 브라질은 식품 부문을 견인하며 남미를 주도하고 있으며, 아르헨티나에서는 가축 사료에 푸마르산을 도입하는 시험적 시도가 진행되고 있습니다. 걸프협력회의(GCC) 회원국들은 건설용 수지의 업스트림 통합을 모색하고 있으며, 남아프리카에서는 의약품 및 식품 가공 분야 수요가 서서히 증가하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the fumaric acid market size is estimated at 307.93 kilotons in 2026, and is expected to reach 376.09 kilotons by 2031, at a CAGR of 4.08% during the forecast period (2026-2031).
This report is Segmented by Grade (Food Grade and Technical Grade), Application (Food and Beverage Processing, Unsaturated Polyester Resin, and More), End-User Industry (Chemical, Food and Beverage, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Fumaric Acid Market Trends and Insights
Clean-Label Demand for Bio-Fermented Fumaric Acid in Asian Convenience Foods
Spiking consumer scrutiny over ingredient declarations is reshaping acidulant sourcing in Japan, South Korea, and China. Japan's April 2024 Food Sanitation Act amendments require explicit labeling of synthetic additives, spurring a reformulation wave among convenience-store chains. South Korea's November 2024 guidance encourages producers to disclose production routes, further nudging demand toward fermentation-derived material. Chinese firms such as Yantai Hengyuan and Changmao Biochemical added an estimated 15,000 tons of bio-capacity across 2024-2025, narrowing the historical 25% price premium for food-grade bio-material to roughly 12% by 2025. Rising middle-class incomes in ASEAN are expected to mirror this trend, expanding regional uptake.
Shift to Unsaturated Polyester Resins for Lightweight EV and Wind-Blade Composites
Electric-vehicle platforms now incorporate about 450 pounds of plastics and composites compared with 310 pounds in ICE vehicles, a delta largely driven by weight-offsetting battery mass. European automakers seeking to meet 2025 fleet-wide CO2 targets are specifying glass-fiber UPR parts that contain 8%-12% fumaric-based co-monomers. Offshore wind projects similarly favor fumaric-modified UPR for blades over 80 meters long, where enhanced fatigue resistance is critical. Counterbalancing forces include premium-segment moves to carbon-fiber prepregs and bio-epoxy systems, but the overall pull from mass-market EVs supports continued volume growth.
Volatility in Maleic-Anhydride Feedstock and Benzene Spot Prices
Spot maleic-anhydride quotations see-sawed between USD 1,050 and USD 1,400 per ton in China during 2024-2025, mirroring benzene price swings. Several small Chinese fumaric acid producers idled units in Q1 2024 when benzene briefly spiked past CNY 7,200 per ton. European operators faced a double hit from volatile benzene and natural-gas prices that averaged EUR 35-45 per MWh in 2024. Lacking long-term maleic contracts, producers struggle to lock in stable margins, prompting vertical integration and portfolio diversification.
Other drivers and restraints analyzed in the detailed report include:
- Europe and North America Antibiotic-Free Feed Laws Boosting Fumaric-Acid Acidulants
- Growth of Specialty Water-Treatment Polymers in Semiconductor Fabs
- EU CO2-Footprint Taxation on Petro-Route Acids (CBAM)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Food-grade accounted for 66.28% of the Fumaric Acid market in 2025, expanding at a 4.51% CAGR to 2031. Bartek's new line is devoted wholly to food-grade output, illustrating strategic emphasis on higher-margin, regulation-intensive channels. Technical-grade demand, tied closely to UPR and alkyd resins, lags amid CBAM costs and volatile maleic feedstocks, yet remains vital for construction and automotive coatings.
Bio-fermentation has compressed the historic 20-25% price premium down to 12-15% by 2025, increasing addressable demand in price-sensitive developing markets. BASF expects its CO2-negative process to reach commercial readiness by 2027, potentially redefining the carbon disclosure landscape for food additives. Producers with dual-spec plants can toggle between grades to cushion swings in either segment, a hedge increasingly favored by integrated chemical houses.
Complete Report Scope:
- By Grade
- Food Grade
- Technical Grade
- By Application
- Food and Beverage Processing
- Unsaturated Polyester Resin (UPR)
- Alkyd Resin
- Rosin Paper Sizing
- Personal Care and Cosmetics
- Other Applications
- By End-user Industry
- Chemical
- Food and Beverage
- Cosmetics
- Pharmaceutical
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific controlled 60.21% of global volume in 2025 and is set for a 4.88% CAGR through 2031. China alone contributes major world capacity, with clusters in Shandong, Hebei, and Jiangsu and a growing share of bio-fermentation units. India is scaling output to meet pharmaceutical and food-grade demand, while Japan and South Korea rely on imports aligned with stringent purity laws. ASEAN nations, especially Vietnam and Thailand, are emerging demand bases as rising urban incomes fuel convenience-food uptake.
North America benefits from Bartek's capacity doubling, positioning the region as a net exporter of bio-grade material. Europe is reshaping supply chains in response to CBAM. Germany, France, and Italy are key consumption nodes, with regional resin producers qualifying low-carbon feedstock. EFSA's favorable feed-additive ruling further enlarges the European addressable pool.
South America and the Middle East and Africa together account for lower global demand. Brazil leads South America via its food sector, while Argentina trials fumaric acid in livestock rations. Gulf Cooperation Council nations are exploring backward integration for construction-grade resins, and South Africa provides incremental pharmaceutical and food-processing demand.
- Anhui Sealong Biotechnology Co., Ltd.,
- Anmol Chemicals Private Limited
- Bartek Ingredients Inc.
- Changmao Biochemical Engineering Co., Ltd.
- ESIM Chemicals GmbH
- FUSO CHEMICAL CO., LTD.
- Henan Shuguang Chemical
- Huntsman International LLC
- Isegen South Africa (Pty) Ltd
- Merck KGaA
- Ningbo Jujia Biotech
- Polynt S.p.A.
- Tate & Lyle
- Thirumalai Chemicals
- UPC Group of Companies
- XST Biological Co. Ltd
- Yantai Hengyuan Biotechnology Co., Ltd.
- Yongsan Chemicals Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Clean-Label Demand for Bio-Fermented Fumaric Acid in Asian Convenience Foods
- 4.2.2 Shift to Unsaturated Polyester Resins for Lightweight EV and Wind-Blade Composites
- 4.2.3 Europe and North America Antibiotic-Free Feed Laws Boosting Fumaric Acid Acidulants
- 4.2.4 Growth of Specialty Water-Treatment Polymers in Semiconductor Fabs
- 4.2.5 Cradle-To-Gate Carbon-Negative Fermentation Technologies Attracting Green-Finance
- 4.3 Market Restraints
- 4.3.1 Volatility In Maleic-Anhydride Feedstock and Benzene Spot Prices
- 4.3.2 EU CO2-Footprint Taxation on Petro-Route Acids (CBAM)
- 4.3.3 Competitive Threat from Succinic and Malic Acid in Shelf-Stable Foods
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Grade
- 5.1.1 Food Grade
- 5.1.2 Technical Grade
- 5.2 By Application
- 5.2.1 Food and Beverage Processing
- 5.2.2 Unsaturated Polyester Resin (UPR)
- 5.2.3 Alkyd Resin
- 5.2.4 Rosin Paper Sizing
- 5.2.5 Personal Care and Cosmetics
- 5.2.6 Other Applications
- 5.3 By End-user Industry
- 5.3.1 Chemical
- 5.3.2 Food and Beverage
- 5.3.3 Cosmetics
- 5.3.4 Pharmaceutical
- 5.3.5 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Anhui Sealong Biotechnology Co., Ltd.,
- 6.4.2 Anmol Chemicals Private Limited
- 6.4.3 Bartek Ingredients Inc.
- 6.4.4 Changmao Biochemical Engineering Co., Ltd.
- 6.4.5 ESIM Chemicals GmbH
- 6.4.6 FUSO CHEMICAL CO., LTD.
- 6.4.7 Henan Shuguang Chemical
- 6.4.8 Huntsman International LLC
- 6.4.9 Isegen South Africa (Pty) Ltd
- 6.4.10 Merck KGaA
- 6.4.11 Ningbo Jujia Biotech
- 6.4.12 Polynt S.p.A.
- 6.4.13 Tate & Lyle
- 6.4.14 Thirumalai Chemicals
- 6.4.15 UPC Group of Companies
- 6.4.16 XST Biological Co. Ltd
- 6.4.17 Yantai Hengyuan Biotechnology Co., Ltd.
- 6.4.18 Yongsan Chemicals Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Emergence of New Potential Application Areas


