|
시장보고서
상품코드
2124066
대리석 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Marble - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
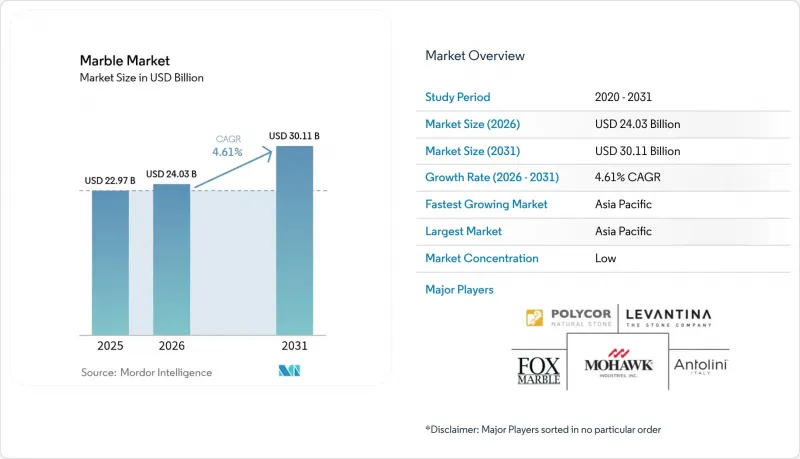
에 의하면, 대리석 시장 규모는 2025년에 229억 7,000만 달러로 평가되었고 2026년 240억 3,000만 달러에서 2031년까지 301억 1,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.61%를 나타낼 전망입니다.
본 보고서에서는 업계를 제품 유형(천연 대리석 및 합성/인공 대리석), 색상(흰색, 검은색, 노란색, 빨간색, 기타 색상), 용도(건축·장식, 조각상·기념비 등), 최종 사용자 분야(주택 건축 등), 지역(아시아태평양, 북미, 유럽 등)별로 분류하고 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 대리석 시장 동향 및 인사이트
건설 업계의 급속한 성장
건설 투자의 확대에 따라 고급 주택이나 복합 용도 타워의 바닥, 벽, 조리대에 고급 석재를 지정하는 개발업자가 증가하고 있으며, 이는 대리석 수요 증가로 이어지고 있습니다. 아시아태평양의 각국 정부는 대형 석재 클래딩을 채택한 교통 허브 및 공공 건축물에 대한 예산 투자를 지속하고 있으며, 이는 구조용 및 장식용 석재의 사용을 뒷받침하고 있습니다. 엄격한 공차 기준에 따라 공장에서 절단된 조립식 대리석 패널은 시공 시간 단축과 현장 파손 감소를 실현하여, 시공사가 공사 기간을 확실하게 준수할 수 있도록 지원합니다. 두께 3-5mm의 얇은 베니어재를 통해 고층 빌딩 외관의 하중이 경감되고, 무게 및 내재 탄소량 측면에서 우위를 점하고 있어, 그린 빌딩 인증을 목표로 하는 프로젝트에서 대리석·콘크리트 복합재가 채택되고 있으며, 이러한 요인들이 대리석 시장의 성장을 뒷받침하고 있습니다.
고급 부동산 및 인프라 프로젝트 증가
고급 호텔 그룹과 프리미엄 오피스 개발업체들은 인상적인 입구, 웰니스 공간, 다이닝 공간을 조성하기 위해 개성 있는 석재를 채택하고 있습니다. 두바이, 싱가포르, 뉴욕의 5성급 호텔을 담당하는 디자이너들은 극적인 무늬를 지닌 인상적인 슬래브를 지정하고 있습니다. 이는 자연이 만들어낸 개체별 차이가 투숙객에게 ‘특별함’을 전달하기 때문입니다. 부티크 브랜드들도 이러한 철학을 소규모 시설로 확대하고 있으며, 인공적으로 제작된 유사 제품과는 차별화되는 희귀한 색조에 대한 수요를 높여 대리석 시장의 성장을 반영하고 있습니다.
대리석 분진과 관련된 건강 피해
절단 및 연마 과정에서 발생하는 흡입성 결정질 실리카는 2024년 4월까지 캘리포니아주에서 127건의 규폐증 사례와 13명의 사망자가 보고됨에 따라 엄격한 감시 대상이 되고 있습니다. 이에 따라 새로운 노출 한도치가 설정되었으며, 습식 절단 방식의 사용이 의무화되었습니다. 천연 대리석에 포함된 실리카의 비율은 10% 미만이지만, 규제 당국은 모든 석재 가공 사업에 대해 유사한 규제를 적용하고 있습니다. 규정 준수에 드는 비용에는 밀폐형 작업대, 고진공 흡입 장치, 개인용 모니터링 시스템 등이 포함되어 있어, 대리석 시장에서 설비 갱신을 위한 자금이 부족한 소규모 가공업체들에게 부담을 주고 있습니다.
부문 분석
2025년에는 산업용 수지 시스템이 고급 카라라 및 카라카타의 외관을 재현하면서도 경도와 오염 저항성을 겸비하게 됨에 따라, 합성 대리석이 시장 점유율의 80.65%를 차지했습니다. 이 부문은 홈센터 유통 채널과 가공의 가속화에 힘입어 연평균 성장률(CAGR) 4.72%로 주도적인 위치를 계속 확대할 것으로 예측됩니다. 천연 대리석은 실제와 같은 느낌과 오랜 기간 유지되는 질감이 유지 관리에 대한 우려를 상쇄하는 프로젝트에서 여전히 중요한 역할을 하고 있습니다. 플래그십 호텔이나 맞춤형 주택의 디자이너들은 여전히 리셉션 데스크, 계단, 조각품 등에 대형 블록을 지정하고 있습니다. 브라질 등 일부 국가에서는 와이어 톱이나 드론 매핑을 통해 채석장의 수익성이 향상되었으며, 새로운 유형의 흰색 대리석이 전 세계 쇼룸에 등장하고 있습니다.
흰색 계열 석재는 2025년에 수요의 36.02%를 차지하며, 2031년까지 연평균 성장률(CAGR) 5.60%를 기록할 전망인데, 이는 대리석 시장 전체를 크게 웃도는 속도입니다. 디자이너들은 특히 웰니스·스파나 미니멀리즘을 추구하는 기업의 로비에서 중립성, 빛 반사율, 그리고 고전 건축과의 연관성을 이 석재가 선호되는 주된 이유로 꼽고 있습니다. 중국과 걸프 지역 국가에서는 더운 기후에 대응하기 위해 밝은 색상의 인테리어가 선호됨에 따라 흰색 계열 대리석 시장 규모가 확대되고 있습니다.
네로 마르키나를 필두로 한 검은색 대리석은 소매점의 플래그십 스토어나 펜트하우스 주방에서 대비를 돋보이게 하는 악센트로 주문이 늘고 있습니다. 노란색, 빨간색, 녹색 대리석은 중동 및 아시아 일부 지역의 지역적 취향을 반영하며, 많은 경우 현지 문화적 상징과 연결되어 있습니다. 다색 및 브레시아 대리석은 인상적인 벽면을 추구하는 전위적인 건축가들의 관심을 끌고 있습니다. 색상 선택은 설계 단계에서 슬래브 전체를 미리 볼 수 있는 디지털 트윈 라이브러리를 통해 이루어지는 경우가 늘어나고 있으며, 이는 불확실성을 줄이고 폐기물을 감소시키는 데 기여하고 있습니다.
지역별 분석
아시아태평양은 2025년에 대리석 시장의 33.62%를 차지하며, 6.10%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다. 인도의 스마트 시티 구축과 인도네시아의 신수도 개발로 인해 바닥재 및 외장용 석재에 대한 새로운 수요가 발생하고 있습니다. 베트남과 파키스탄의 생산자들은 지역 사양에 맞추기 위해 채석장의 생산량을 확대되고 있습니다.
유럽 시장은 이탈리아와 튀르키예가 중심을 이루고 있습니다. 카라라산 대리석은 대리석의 상징이라 할 수 있는 흰색을 제공하지만, 폐기물이 여전히 과제로 남아 있어 채굴된 석재의 최대 70%가 슬러지로 폐기되고 있습니다. 규제 및 사회적 압력으로 인해 물 재활용,건식 성형, 그리고 대리석을 원료로 한 3D 프린팅용 필라멘트 등 ‘폐기물에서 제품으로’ 전환을 위한 노력에 대한 투자가 촉진되고 있습니다. 독일과 스페인의 가공업체들은 친환경 인증 획득을 목표로 하는 건축가들을 대상으로 저배출 인증을 받은 석재를 판매하고 있습니다.
북미에서는 고가 가격 책정이 유지되고 있으며, 특색 있는 품종공급이 부족합니다. 수요는 고급 주거 타워, 부티크 호텔, 고급 소매점을 중심으로 집중되고 있습니다.
남미는 공급 거점으로 부상하고 있으며, 브라질의 흰색 규암과 대리석이 미국 및 유럽의 프로젝트에 채택되고 있습니다. 중동 및 아프리카에서는 사우디아라비아, 아랍에미리트, 남아프리카공화국의 메가 프로젝트와 연계하여 견조한 수요가 나타나고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the marble market size was valued at USD 22.97 billion in 2025 and estimated to grow from USD 24.03 billion in 2026 to reach USD 30.11 billion by 2031, at a CAGR of 4.61% during the forecast period (2026-2031).
This report Segments the Industry by Product Type (Natural Marble and Synthetic/Artificial Marble), Color (White, Black, Yellow, Red, and Other Colors), Application (Building and Decoration, Statues and Monuments, and More), End-User Sector (Residential Buildings, and More), and Geography (Asia-Pacific, North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Marble Market Trends and Insights
Rapid Growth in the Construction Industry
Construction spending is cascading into higher marble demand as developers specify premium stone for floors, walls, and countertops in luxury homes and mixed-use towers. Governments across Asia-Pacific continue to funnel budget into transport hubs and civic buildings that feature large-format stone cladding, lifting structural as well as decorative usage. Prefabricated marble panels, factory-cut to tight tolerances, are saving installation time and reducing on-site breakage, helping contractors meet schedule guarantees. Thin 3-5 mm veneers are opening high-rise facades to lighter loads, and marble-concrete composites are appearing in projects seeking green-building certifications due to weight and embodied-carbon advantages, supporting the growth in the marble market.
Increase in Luxury Real Estate and Infrastructure Projects
Luxury hospitality groups and premium office developers are turning to distinctive stone to craft memorable entrances, wellness areas, and dining venues. Designers working on five-star hotels in Dubai, Singapore, and New York specify statement slabs with dramatic veining because natural variance signals exclusivity to guests. Boutique brands extend the same ethos to small properties, boosting demand for rare colors that differentiate from engineered look-alikes, reflecting growth in the marble market.
Health Hazard Related to Marble Dust
Respirable crystalline silica generated during cutting and polishing is under heightened scrutiny after California recorded 127 silicosis cases and 13 fatalities by April 2024, prompting new exposure limits and mandated wet-cutting protocols. Although natural marble contains less than 10% silica, regulators are applying similar controls across all stone operations. Compliance costs include enclosed workstations, high-vacuum extraction, and personal monitoring systems, pressuring small fabricators that lack the capital to upgrade in the marble market.
Other drivers and restraints analyzed in the detailed report include:
- Rising Adoption of Marble Powder as Supplementary Cementitious Material
- Technological Advancements in Extraction and Processing
- Competition from Synthetic Alternatives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Synthetic grades dominated 80.65% of the marble market in 2025 as industrial resin systems reproduced the look of premium Carrara and Calacatta while providing hardness and stain resistance. The segment is projected to extend leadership at a 4.72% CAGR, supported by home-center channels and accelerated fabrication. Natural marble stays relevant in projects where authenticity and long-term patina outweigh maintenance concerns. Designers of flagship hotels and bespoke residences still specify large blocks for reception desks, staircases, and sculpture. Countries such as Brazil have improved quarry yield through wire saws and drone mapping, bringing new white marble varieties to global showrooms.
White stones captured 36.02% of demand in 2025 and are on track for a 5.60% CAGR through 2031, significantly above the marble market. Designers cite neutrality, light reflectance and association with classical architecture as key reasons for preference, particularly in wellness spas and minimalist corporate lobbies. The marble market size for white varieties is expanding in China and the Gulf, where bright interiors counter hot climates.
Black marbles, led by Nero Marquina, secure orders for contrast features in retail flagships and penthouse kitchens. Yellow, red, and green types cater to regional tastes in the Middle East and parts of Asia, often tied to local cultural symbolism. Multicolored and brecciated stones attract avant-garde architects seeking statement walls. Color choice is increasingly curated through digital twin libraries that allow clients to preview entire slabs at the design stage, reducing uncertainty and waste.
Complete Report Scope:
- By Product Type
- Natural Marble
- Synthetic/Artificial Marble
- By Color
- White
- Black
- Yellow
- Red
- Other Colors
- By Application
- Building and Construction
- Statues and Monuments
- Furniture
- Other Applications (Decorative Infrastructure)
- By End-user Sector
- Residential Buildings
- Commercial and Hospitality
- Industrial and Institutional
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Turkey
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 33.62% of the marble market in 2025 and is forecast to post the highest 6.10% CAGR. India's smart-city roll-out and Indonesia's new capital development add fresh demand for flooring and facade stone. Producers in Vietnam and Pakistan are expanding quarry output to meet regional specifications.
Europe is anchored by Italy and Turkey. Carrara delivers iconic whites, yet waste remains a pain point, with up to 70% of extracted mass discarded as sludge. Regulation and social pressure are catalyzing investment in water recycling, dry shaping, and waste-to-product initiatives such as marble-based 3D printing filament. German and Spanish processors market verified low-emission stone to architects pursuing green certifications.
North America maintains premium pricing and a tight supply of distinctive varieties. Demand centers on luxury residential towers, boutique hotels, and upmarket retail.
South America is emerging as a supply hub, with Brazil's white quartzites and marble winning specifications in US and European projects. The Middle East and Africa show robust demand linked to mega-projects in Saudi Arabia, the United Arab Emirates and South Africa.
- Antolini Luigi & C. S.p.a.
- BC Marble Products Ltd
- Best Cheer Stone Group
- China Kingstone Mining Holdings Limited
- Dimpomar
- Eco Buildings Group Plc
- F.H.L.
- Fox Marble
- HELLENIC GRANITE Co
- Hilltop Stones Pvt. Ltd.
- Kangli stone group
- Levantina y Asociados de Minerales, S.A.
- Mohawk Industries, Inc.
- Mumal Marbles Pvt. Ltd.
- NQ Acrylic and Stone
- Polycor Inc.
- Santucci Group Srl
- TEKMAR MERKEZ OFFICES
- Temmer Marble
- Topalidis S.A.
- UMGG
- XISHI GROUP LTD.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Growth in the Construction Industry
- 4.2.2 Increase in Luxury Real Estate and Infrastructure Projects
- 4.2.3 Rising Adoption of Marble powder as Supplementary Cementitious Material for Low-carbon Concrete
- 4.2.4 Growing Inclination on Marble as a Natural and Sustainable Material
- 4.2.5 Technological Advancements in Extraction and Processing Driving Growth in the Marble Industry
- 4.3 Market Restraints
- 4.3.1 Health Hazard Related to Marble Dust
- 4.3.2 Competition from Synthetic Alternatives
- 4.3.3 Waste Generation and Recycling Challenges
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
- 4.6 Trade Analysis
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Natural Marble
- 5.1.2 Synthetic/Artificial Marble
- 5.2 By Color
- 5.2.1 White
- 5.2.2 Black
- 5.2.3 Yellow
- 5.2.4 Red
- 5.2.5 Other Colors
- 5.3 By Application
- 5.3.1 Building and Construction
- 5.3.2 Statues and Monuments
- 5.3.3 Furniture
- 5.3.4 Other Applications (Decorative Infrastructure)
- 5.4 By End-user Sector
- 5.4.1 Residential Buildings
- 5.4.2 Commercial and Hospitality
- 5.4.3 Industrial and Institutional
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Turkey
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (Mergers and Acquisitions, Partnerships, Quarry Integration)
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Antolini Luigi & C. S.p.a.
- 6.4.2 BC Marble Products Ltd
- 6.4.3 Best Cheer Stone Group
- 6.4.4 China Kingstone Mining Holdings Limited
- 6.4.5 Dimpomar
- 6.4.6 Eco Buildings Group Plc
- 6.4.7 F.H.L.
- 6.4.8 Fox Marble
- 6.4.9 HELLENIC GRANITE Co
- 6.4.10 Hilltop Stones Pvt. Ltd.
- 6.4.11 Kangli stone group
- 6.4.12 Levantina y Asociados de Minerales, S.A.
- 6.4.13 Mohawk Industries, Inc.
- 6.4.14 Mumal Marbles Pvt. Ltd.
- 6.4.15 NQ Acrylic and Stone
- 6.4.16 Polycor Inc.
- 6.4.17 Santucci Group Srl
- 6.4.18 TEKMAR MERKEZ OFFICES
- 6.4.19 Temmer Marble
- 6.4.20 Topalidis S.A.
- 6.4.21 UMGG
- 6.4.22 XISHI GROUP LTD.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Growing Use of Marble Slabs and Powder