

|
시장보고서
상품코드
2124069
벽돌 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Brick - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
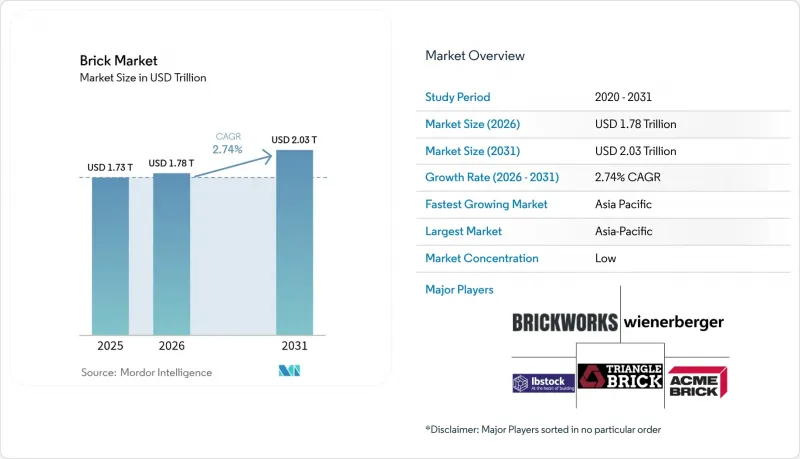
에 의하면, 2026년 벽돌 시장 규모는 1조 7,800억 달러로 추정되고, 2025년 1조 7,300억 달러에서 확대해, 2031년에는 2조 300억 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 2.74%로 성장할 것으로 전망됩니다.
본 보고서는 벽돌 유형별(점토, 모래석회, 플라이애시 점토 등), 용도별(건물, 보도, 화단 등), 최종 이용 산업별(주택 건축 및 비주택 건축), 유통 채널별(직접 판매, 딜러 및 소매 네트워크), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 벽돌 시장 동향 및 인사이트
포스트 코로나 시대의 재도시화 호재
아시아 주요 도시로의 급속한 귀환으로 인해 중층 주택 프로젝트 파이프라인이 다시 풍부해지면서, 벽돌 시장 수요가 견조하게 유지되고 있습니다. 유엔 아시아태평양경제사회위원회(UN ESCAP)는 이 지역의 도시 인구가 2030년까지 32억 명에 달하고, 22개의 메가시티가 탄생할 것으로 예측했습니다. 중층 주택에서는 비용 효율이 뛰어난 내력벽으로서, 또한 현지 노동자들이 익숙해져 있기 때문에 조적 공법이 채택되고 있습니다. 각국 정부는 주택 부족 문제를 해결하기 위해 사회주택 예산을 증액하고 있습니다. 인도에서만 2024년에 1,870만 호의 부족이 기록되었고, 인도네시아에서도 1,250만 호의 부족이 확인되어, 이 모두 벽돌에 대한 기초적인 수요를 더욱 확대시키고 있습니다. 각 공급업체는 운송 비용을 최소화하기 위해 1차 성장 회랑에 인접한 곳에 공급 거점을 배치하고 있습니다. 연료 소비량을 늘리지 않으면서 가마의 생산 능력을 높이는 설비 업그레이드를 통해, 건설 수요가 주기적으로 급증하는 시기에도 시공사는 기한 내에 자재를 납품받을 수 있게 되었습니다.
‘친환경’ 건축 기준
2040년까지 배출량을 90% 감축하겠다는 유럽의 목표는 벽돌 시장을 변화시키고 있으며, 탄소 발자국이 작은 플라이애시 벽돌과 규산칼슘 벽돌의 채택을 가속화하고 있습니다. 규산칼슘 벽돌의 1차 에너지 소비량은 241 kWh/t인 반면, 기존 점토 벽돌은 그보다 높은 수치를 보여, 영국의 ‘넷 제로 카본 빌딩 스탠다드(Net Zero Carbon Building Standard)’에 기반한 인증을 추구하는 설계자들에게 매력적인 선택지가 되고 있습니다. 소성 공정을 생략한 콘크리트 벽돌은 주택 1채당 2.4톤의 CO2를 감축할 수 있으며, 전체 수명 주기 동안 순 CO2 흡수원이 됩니다. 현재 공공 부문 프로젝트에는 재활용 재료 사용에 관한 최소 기준이 포함되어 있어, 공장은 유리 파편이나 소각된 고형 폐기물을 혼합물에 포함시켜야 합니다. 제조부터 현장까지의 수명 주기 데이터를 검증한 제조업체는 리모델링 공사나 공공 조달 입찰에서 사양상의 우위를 확보할 수 있습니다.
조립식 건축자재
인력 부족이 심화되는 가운데, 북미와 유럽의 건설업체들은 벽돌 외관을 뒤로하고 체적형 모듈로 무게중심을 옮기고 있습니다. 조립식 솔루션은 현장 작업 시간을 30-50% 단축하고 인건비를 50-80% 절감합니다. 2025년까지 미국에서 50만 1,000명의 숙련된 노동자가 추가로 필요할 것으로 예상되는 가운데, 건설업체들은 표준 패널을 리스크 헤지 수단으로 간주하고 있습니다. 얇은 벽돌 슬립과 기계 고정식 마감 벽돌 덕분에 석공 자재 공급업체들은 시장에서 입지를 유지하고 있지만, 풀베드 벽돌이 대체되는 분야에서는 전체 유닛에 대한 수요가 감소하고 있습니다. 제조업체들은 하이브리드 벽 패널에 대응하기 위해 로봇 적층 라인에 투자하고 있지만, 축소되는 기존 판매량을 기준으로 설비 투자를 상각해야 하기 때문에 이익률이 압박받고 있습니다.
부문 분석
2025년에는 점토 벽돌이 매출의 64.35%를 차지하며 벽돌 시장을 독점했으나, 플라이애시 벽돌은 2031년까지 연평균 성장률(CAGR) 3.12%를 기록하며 탄소 규제가 강화되고 있는 지역에서 입지를 확대되고 있습니다. 이러한 변화는 산업 폐기물의 활용에 힘입은 것으로, 공장은 소성 온도를 20% 낮춤으로써 순환 경제 요건을 충족할 수 있게 되었습니다. 플라이애시 계열 벽돌 시장 규모는 재활용 소재 사용을 중시하는 공공 조달 기준에 힘입어 다른 어떤 유형보다 빠르게 확대될 것으로 예측됩니다. 규산칼슘 벽돌은 유럽의 추운 기후에서 열용량의 이점을 추구하는 건축가들에게 지지를 받고 있습니다. 한편, 가마 소성이 필요 없는 콘크리트 블록은 전력 공급이 확보되어 있고 연료의 안정적 공급이 불확실한 지역에서 수요가 증가하고 있습니다.
기술적 진보로는 수분 흡수율이 4-7%인 숯계 얇은 벽돌을 꼽을 수 있습니다. 이 제품은 시중의 동종 제품을 능가하는 성능을 갖추고 있으며, 1제곱미터당 25.83달러로 기존 제품의 일반적인 가격의 절반 이하입니다. 또한 각 제조업체는 제조 과정에서의 CO₂ 배출량을 줄이고 물류 부담을 경감하는 중공 구조 제품도 추진하고 있습니다. 이러한 혁신들은 전반적으로 구조적 신뢰성을 훼손하지 않으면서 탈탄소화를 실현하려는 벽돌 시장의 목표를 뒷받침하고 있습니다. 특허를 보유한 곳은 극소수의 초기 도입 기업뿐이며, 이는 가까운 미래에 라이선싱 수익의 새로운 흐름이 생겨나 벽돌 업계 내의 이익 구조를 일변시킬 가능성을 시사합니다.
2025년 벽돌 시장 점유율 중 건축 용도가 59.10%를 차지했으며, 이는 구조벽 및 파사드에서 석조 공법이 역사적으로 수행해 온 역할을 반영합니다. 기밀성이 높은 외피와 내화성을 강화하는 건축 기준 개정이 이러한 핵심 수요를 뒷받침하고 있습니다. 한편, 보도 및 포장 솔루션용 벽돌 시장 규모는 연평균 성장률(CAGR) 3.02%로 확대되고 있는데, 이는 일반 가정이 야외 환경 개선에 투자하고 있으며, 지자체가 증가하는 보행자 통행량을 감당할 수 있도록 보도를 정비하고 있기 때문입니다.
벽돌 업계의 각 제조업체는 색이 잘 바래지 않는 점토와 마찰 계수가 높은 질감을 활용하여, 유지 관리의 번거로움을 줄이고 다양한 디자인을 원하는 조경 고객의 요구에 부응하고 있습니다. 모서리가 서로 맞물리는 구조의 벽돌은 시공을 신속하게 하여 시공사의 비용을 절감하는 동시에, 단기간 내의 보수 일정에도 대응하고 있습니다. 고급 주택가에서는 미적 차별화를 통해 높은 이익률을 추구하기 때문에 파르테르나 장식적인 정원 양식이 다시 주목받고 있습니다. 산업 분야 고객들은 용광로 내벽이나 화학 처리 피트에 내산성 벽돌을 선호하여 채택하고 있으며, 이를 통해 용도의 다양성이 더욱 강화되어 생산자는 단일 부문의 부진으로부터 보호받고 있습니다.
지역별 분석
아시아태평양은 2025년 전 세계 매출의 47.30%를 차지했으며, 기록적인 도시 인구 유입과 교통 인프라 메가 프로젝트에 힘입어 2031년까지 연평균 3.30%의 성장이 예상됩니다. 중국과 인도는 공공 부문의 주택 건설 추진이 지하철, 공항, 산업단지 건설과 맞물려 벽돌 소비를 견인하고 있습니다. 생산자들은 각 성의 배출 상한선을 충족하고 석탄 의존도를 낮추기 위해 폐열 회수 기능을 갖춘 터널 가마를 도입하고 있으며, 수요가 급증할 때에도 공급 회복력을 확보하고 있습니다.
북미에서는 금리 인하 전망에 따라 정체되었던 프로젝트가 재개되면서 시장 가치가 확대되고 있습니다. AIA 컨센서스 건설 전망에 따르면, 2023-2024년 견조한 성장세를 보인 후, 비주거 부문 지출은 2025년에 2.2%, 2026년에 2.6% 증가할 것으로 예측됩니다. LEED 점수 획득을 목표로 하는 설계자들 사이에서 플라이애시 벽돌이 주목을 받는 한편, 얇은 벽돌 패널은 도시 지역의 공동주택 건설을 가속화하고 있습니다. 캐나다의 추운 기후로 인해 난방 부하를 줄이기 위한 주택 개보수에서 열용량이 높은 점토 건축자재에 대한 수요가 지속되고 있습니다.
유럽은 성장률 면에서는 뒤처지고 있지만, CBAM(탄소국경조정메커니즘)이 탄소 집약형 수입품을 드러내고 현지 저탄소화의 선구자를 우대하는 가운데, 혁신 측면에서는 주도적인 역할을 하고 있습니다. 이 대륙에서는 2022년에 5억 개 이상의 벽돌이 수입되어 28만 8,190톤의 CO2를 배출했습니다. 이에 따라 보다 친환경적인 생산 능력을 국내로 회귀시켜야 한다는 목소리가 높아지고 있습니다. 스칸디나비아 국가들의 공공 조달 정책에서는 내재된 탄소의 상한선이 규정되어 있어, 칼슘규산염 벽돌이나 미소성 콘크리트 벽돌에 대한 발주가 촉진되고 있습니다. 동유럽에서는 자재 부족에 직면한 국내 및 독일 시장에 대응하기 위해 생산 능력 확충이 진행되고 있습니다.
남미의 벽돌 시장은 전자상거래에 힘입어 확대된 창고 및 물류 시설 구축을 중심으로 전개되고 있습니다. 브라질에서는 새로운 고속도로를 따라 산업단지 조성이 가속화되면서, 시공 시간을 단축할 수 있는 대형 블록에 대한 수요가 증가하고 있습니다. 자재 공급업체들은 환율 변동과 수입 관세를 피하기 위해 현지 공장에 투자하고 있습니다. 중동 및 아프리카는 현재 규모는 작지만, 2040년까지 필요한 건물의 70%가 아직 건설되지 않았기 때문에 가장 높은 성장 잠재력을 지니고 있습니다. 케냐, 나이지리아, 이집트에서는 합리적인 가격의 주택을 공급하기 위해 민관 협력(PPP)을 추진하고 있으며, 국내 생산을 촉진하기 위해 입찰 서류에 벽돌 조달 목표를 포함시키고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, brick market size in 2026 is estimated at USD 1.78 trillion, growing from 2025 value of USD 1.73 trillion with 2031 projections showing USD 2.03 trillion, growing at 2.74% CAGR over 2026-2031.
This report is Segmented by Brick Type (Clay, Sand Lime, Fly-Ash Clay, and More), Application (Buildings, Path, Parterre, and More), End-Use Industry (Residential Buildings and Non-Residential Buildings), Distribution Channel (Direct and Dealer and Retail Network), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Brick Market Trends and Insights
Post-COVID Re-urbanisation Boost
Rapid migration back to major Asian cities is refilling pipelines for mid-rise housing projects, sustaining steady brick market demand. UN ESCAP projects the region's urban population will touch 3.2 billion by 2030, spawning 22 megacities. Mid-rise formats rely on masonry for cost-effective load-bearing walls and local labor familiarity. Governments are increasing social-housing budgets to narrow deficits-India alone recorded an 18.7-million-unit gap in 2024, while Indonesia tallied 12.5 million units, each amplifying baseline need for bricks. Vendors position supply hubs close to Tier-1 growth corridors to minimize freight costs. Equipment upgrades that raise kiln capacity without higher fuel burn ensure contractors receive on-time deliveries during cyclical building surges.
'Green' Building Codes
Europe's 90% emissions-cut target for 2040 is reshaping the brick market, accelerating the adoption of fly-ash and calcium-silicate bricks with smaller carbon footprints. Calcium-silicate units consume 241 kWh/t of primary energy versus higher values for traditional clay, appealing to designers seeking certification under the UK Net Zero Carbon Buildings Standard. Concrete bricks that bypass firing processes can save 2.4 tonnes of CO2 per house and become net absorbers over their lifecycle. Public-sector projects now embed minimum recycled-material thresholds, pushing plants to integrate glass cullet and combusted solid waste into mixes. Manufacturers that verify cradle-to-site life-cycle data lock in specification advantage for renovation and public procurement tenders.
Prefabricated Construction Components
As labor shortages intensify, builders in North America and Europe pivot toward volumetric modules that sideline brick facades. Prefab solutions remove 30-50% of on-site time and lower labor costs by 50-80%. With the United States needing another 501,000 skilled workers in 2025, contractors view standard panels as risk hedges. Thin-brick slips and mechanically fixed veneers let masonry suppliers stay relevant, yet overall unit demand dips where full-bed bricks are displaced. Manufacturers invest in robotic laying lines to service hybrid wall panels but must amortize capital across a shrinking traditional volume base, squeezing margins.
Other drivers and restraints analyzed in the detailed report include:
- Modular Construction
- Government-Subsidised Housing
- Carbon-Tax Exposure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Clay bricks dominated the brick market with 64.35% of revenue in 2025, yet fly-ash bricks record a 3.12% CAGR through 2031, widening their presence in regions tightening carbon rules. This shift is anchored in industrial-waste utilization, enabling plants to cut firing temperatures by 20% and align with circular-economy mandates. The brick market size for fly-ash variants is forecast to expand faster than any other type, helped by public procurement criteria that reward recycled content. Calcium-silicate units attract architects pursuing thermal-mass advantages in Europe's cool climates, while concrete blocks that skip kiln firing appeal where electricity is available and fuel security is uncertain.
Technological advances include char-based thin bricks exhibiting 4-7% water absorption, outperforming commercial peers and costing USD 25.83 per sq m, less than half the prevailing price for traditional options. Makers also promote hollow configurations that cut embodied CO2 and lighten logistics loads. Collectively, these innovations reinforce the brick market goal of decarbonization without sacrificing structural reliability. Only a handful of early adopters own patents, hinting at near-term licensing revenue streams that could reshape profit pools within the brick industry.
Building applications accounted for 59.10% of brick market share in 2025, reflecting masonry's historic role in structural walls and facades. Code updates promoting airtight envelopes and fire resistance sustain this core demand. The brick market size for path and paving solutions, however, is expanding at a 3.02% CAGR as households invest in outdoor upgrades and municipalities retrofit sidewalks to endure heavier pedestrian flows.
Manufacturers in the brick industry exploit colorfast clays and high-friction textures to serve landscaping customers seeking design variety with low maintenance. Bricks configured with interlocking edges accelerate installation, lowering contractor costs and aligning with quick-turn renovation schedules. Parterre and decorative garden formats resurface in premium estates where aesthetic differentiation commands higher margins. Industrial customers favor acid-resistant bricks for furnace linings and chemical-processing pits, reinforcing a diverse end-use spread that shelters producers from single-sector downturns.
Complete Report Scope:
- By Brick Type
- Clay
- Sand Lime
- Fly-Ash Clay
- Other Brick Types
- By Application
- Building
- Path
- Parterre
- Other Applications
- By End-Use Industry
- Residential Buildings
- Non-Residential Buildings
- By Distribution Channel
- Direct (Project-Based)
- Dealer and Retail Network
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific generated 47.30% of 2025 global sales and is projected to grow 3.30% annually to 2031, buoyed by record urban migration and transport megaprojects. China and India spearhead masonry consumption as public-sector housing pushes converge with subway, airport, and industrial-park builds. Producers deploy tunnel kilns with waste-heat recovery to meet provincial emission caps and reduce coal dependence, safeguarding supply resiliency during demand spikes.
North America is experiencing growth in market value, driven by pending interest-rate cuts that are unlocking stalled projects. The AIA Consensus Construction Forecast sees non-residential spending rising 2.2% in 2025 and 2.6% in 2026 after a strong 2023-2024 run. Fly-ash bricks gain traction among designers chasing LEED points, while thin-brick panels speed up urban multifamily builds. Canada's colder climate sustains demand for high-thermal-mass clay units in residential retrofits to cut heating loads.
Europe trails in growth but leads innovation as the CBAM exposes carbon-intensive imports and rewards local low-carbon pioneers. The continent imported over 500 million bricks in 2022, generating 288,190 tonnes of CO2, prompting calls for onshoring greener capacity. Scandinavia's public-procurement policies stipulate embodied-carbon ceilings, channeling orders toward calcium-silicate or unfired concrete bricks. Eastern Europe builds capacity to serve domestic and German markets facing material tightness.
South America's brick market pivots on warehouse and logistics developments catalyzed by e-commerce. Brazil accelerates industrial parks along new highways, increasing demand for large-format blocks that reduce lay-rate time. Material suppliers invest in local plants to sidestep currency volatility and import duties. Middle East and Africa, although smaller today, hold the loftiest upside as 70% of buildings required by 2040 are yet to be built. Kenya, Nigeria and Egypt roll out public-private partnerships to deliver affordable homes, embedding brick procurement targets into tender documents to stimulate domestic manufacturing.
- Acme Brick Company
- BigBloc Construction Ltd.
- Bowerston Shale
- Brampton Brick
- Brickworks
- Brickworks
- Cemex SAB de CV
- Columbia Brick Inc.
- Forterra Building Products Ltd
- General Shale Inc.
- Glen-Gery Corporation
- HEBRON BRICK
- Ibstock Plc.
- LEE Building Products
- Lignacite Ltd
- Oldcastle APG
- Palmetto Brick Company
- Supreme Concrete
- Triangle Brick Co.
- Wienerberger AG
- Xella International
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Post-COVID Re-urbanisation Boosting Mid-Rise Housing Demand in Asia
- 4.2.2 Green' Building Codes Driving Fly-Ash and Calcium-Silicate Brick Uptake in Europe
- 4.2.3 Modular Construction Increases Demand for High-Strength Hollow Bricks
- 4.2.4 Government-Subsidised Low-Cost Housing in Sub-Saharan Africa
- 4.2.5 Expansion of E-Commerce Warehousing in South America
- 4.3 Market Restraints
- 4.3.1 Increasing Trends of Prefabricated Construction Components
- 4.3.2 Volatility in Clay Feedstock Prices in Asia
- 4.3.3 Carbon-Tax Exposure for Energy-Intensive Kilns in Europe
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Brick Type
- 5.1.1 Clay
- 5.1.2 Sand Lime
- 5.1.3 Fly-Ash Clay
- 5.1.4 Other Brick Types
- 5.2 By Application
- 5.2.1 Building
- 5.2.2 Path
- 5.2.3 Parterre
- 5.2.4 Other Applications
- 5.3 By End-Use Industry
- 5.3.1 Residential Buildings
- 5.3.2 Non-Residential Buildings
- 5.4 By Distribution Channel
- 5.4.1 Direct (Project-Based)
- 5.4.2 Dealer and Retail Network
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Acme Brick Company
- 6.4.2 BigBloc Construction Ltd.
- 6.4.3 Bowerston Shale
- 6.4.4 Brampton Brick
- 6.4.5 Brickworks
- 6.4.6 Brickworks
- 6.4.7 Cemex SAB de CV
- 6.4.8 Columbia Brick Inc.
- 6.4.9 Forterra Building Products Ltd
- 6.4.10 General Shale Inc.
- 6.4.11 Glen-Gery Corporation
- 6.4.12 HEBRON BRICK
- 6.4.13 Ibstock Plc.
- 6.4.14 LEE Building Products
- 6.4.15 Lignacite Ltd
- 6.4.16 Oldcastle APG
- 6.4.17 Palmetto Brick Company
- 6.4.18 Supreme Concrete
- 6.4.19 Triangle Brick Co.
- 6.4.20 Wienerberger AG
- 6.4.21 Xella International
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Increasing Carbon-Neutral Kiln Technologies


