

|
시장보고서
상품코드
2124078
요오드 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Iodine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
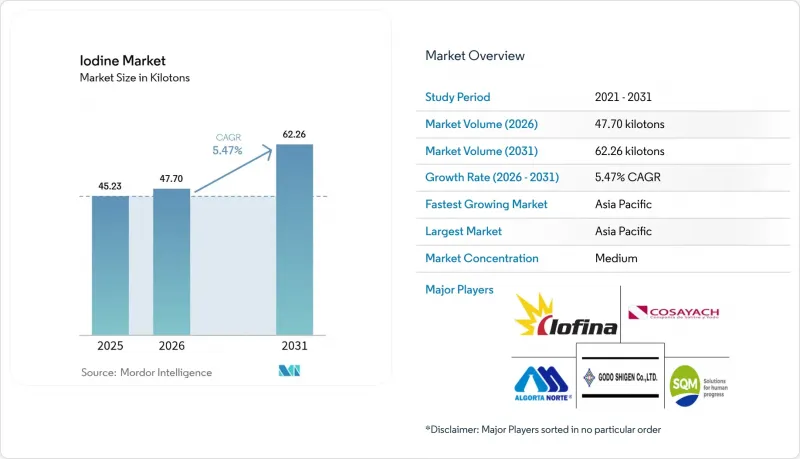
에 의하면, 요오드 시장 규모는 2025년 45.23 킬로톤으로 평가되었고, 2026년 47.70 킬로톤으로 추정되고, 2031년까지 62.26 킬로톤으로 확대될 것으로 예측되며, 2026-2031년 연평균 복합 성장률(CAGR)은 5.47%를 나타낼 전망입니다.

본 보고서는 원료별(칼리체 광석, 지하 염수, 해조류, 재활용), 형태별(유기 화합물, 원소 및 동위원소, 무기염 및 착물), 최종 사용자 산업별(의료, 동물사료, 살생물제, 불소화학물제품, 나일론 등), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 수량(톤) 기준으로 제시되어 있습니다.
세계의 요오드 시장 동향 및 인사이트
X선/CT 조영제 수요 증가
연간 약 7,500만 건의 진단 검사에서 요오드계 조영제가 사용되고 있으며, 미국의 CT 스캔 중 약 48%에서 조영제를 통한 영상 강화가 필요합니다. GE 헬스케어는 전 세계 조영제 수요가 10년 이내에 2배로 증가할 것으로 예상에 따라, 공급을 확보하기 위해 2024년에 아일랜드 코크 공장에 3,000만 달러를 투자했습니다. 광자 계수형 CT 기술로 인해 5 keV 에너지 구간당 환자 1인당 요오드 사용량은 약 10% 감소하지만, 선별 검사 프로그램의 확대에 따라 절대량은 계속 증가하고 있습니다. SQM사는 의약품 중간체 제조업체와 다년간의 원료 공급 계약을 체결하고, 의료용 등급의 제품을 고가로 확보함으로써 원자재 가격 변동으로부터 수익을 보호하고 있습니다. WHO는 요오드 조영제를 필수 의약품 목록에 등재하여 저소득 국가의 의료 제도에서도 최소한의 조달을 보장하고 있습니다.
정부의 식염 요오드 첨가 프로그램
2024년에는 가구의 약 88%가 요오드 첨가 소금을 사용하고 있어 2020년의 86%에서 증가했으나, 여전히 20억 명 이상이 요오드 결핍 위험에 노출되어 있습니다. 인도가 2024년에 도입한 요오드와 철분 이중 강화 의무화로 인해 1kg당 요오드 첨가량이 증가했으며, 농촌 지역의 소매 채널 전반에 걸쳐 요오드 시장이 확대되고 있습니다. 동남아시아 및 사하라 이남 아프리카의 규제 당국은 규정 준수 감사를 강화하고 있으며, 공급업체에 대한 기술적 요건을 높이고 ISO 9001에 기반한 추적성 문서화를 의무화하고 있습니다. 영양 강화용으로 전용되는 저순도 등급은 고규격 부문에서 경기 침체가 닥쳤을 때 생산자의 현금 흐름을 안정시키는 가격 하한선을 형성하고 있습니다. 유니세프의 대량 조달에서는 실적이 입증된 물류 체계를 갖춘 공급업체가 우선시되므로, 지역의 소규모 신규 진입업체에게는 진입 장벽이 높아지고 있습니다.
칠레 칼리체 생산량 변동에 따른 가격 급등락
칠레는 전 세계 요오드 공급량의 약 60%를 차지하고 있지만, 2024년 아타카마 사막에서 발생한 강우로 인해 광석 처리가 제한되면서 현물 가격은 전년도의 톤당 2만 7,000달러에서 3만 8,000달러로 상승했습니다. 아시아태평양의 구매자들은 8-12주의 운송 기간에 직면해 있으며, 전략적 비축량이 60일분을 초과하는 경우는 드물기 때문에 가격 변동이 더욱 확대되고 있습니다. 지하 염수의 생산량은 연평균 성장률(CAGR) 5.56%로 증가하고 있지만, 칼리체에 비해 한 자릿수 규모로 작아 단기적인 공급원 다각화에는 한계가 있습니다. 장기 공급 계약을 체결한 생산자는 영향을 덜 받지만, 조영제 및 촉매 제조업체들은 현물 가격이 톤당 5,000달러를 초과하면 이익률이 압박을 받는다고 보고하고 있습니다. 따라서 기상 리스크와 질산염 광산의 채굴 주기는 요오드 시장공급 측면에서 계속해서 주요 제약 요인으로 작용하고 있습니다.
부문 분석
2025년에도, SQM사의 1만 6,200톤 생산량을 중심으로 칼리체 광석은 여전히 요오드 시장 점유율의 50.88%를 차지했지만, 최종 사용자 공급 다각화 추구를 반영하여 지하 염수의 생산량은 연평균 성장률(CAGR) 5.56%로 더 빠른 속도로 증가하고 있습니다. Iofina 등 사업자들이 미국 퍼미안 분지에서 새로운 유정을 가동함에 따라, 염수 기반 요오드 시장 규모는 확대될 것으로 예측됩니다.
염수를 이용한 생산은 질산염 광석의 채굴 주기를 생략하고, 본래라면 재주입되어야 할 유동수를 활용하기 때문에 요오드 등급이 0.1 g L-1 미만임에도 불구하고 한계 추출 비용을 절감할 수 있습니다. 해수 농도의 약 1,000배 농도로 염수를 추출하고 있는 일본 기업은 세계 생산량의 30%를 공급하며, 그 상업적 실현 가능성을 입증하고 있습니다. GE 헬스케어의 회수 네트워크가 주도하는 재활용을 통해 2025년에는 조영제에 사용된 요오드의 18%가 회수될 것으로 예상되며, 이는 폐쇄형 성장의 여지가 있음을 보여줍니다. 해조류는 노동 집약적이고 수확량도 낮아 현재 공급량이 부족한 상황입니다.
지역별 분석
아시아태평양은 2025년에 세계 수요의 34.31%를 차지하며 요오드 시장을 주도했으며, 2031년까지 연평균 성장률(CAGR) 6.89%로 성장할 전망입니다. 중국의 LCD 편광 필름 생산과 인도의 이중 강화염 프로그램이 이 지역 공급량 증가를 뒷받침하고 있습니다. 0.1 g L-1 농도의 염수를 조달하고 있는 일본은 이 지역 전체의 하류 가공업체들에게 여전히 매우 중요한 공급원입니다.
북미는 염수 생산량 증가의 혜택을 받고 있으며, 특히 Iofina사가 2026년 하반기에 가동을 시작할 예정인, 연간 170-220톤의 생산 능력을 갖춘 퍼미안 분지의 신규 공장이 주목받고 있습니다. 유럽은 여전히 조영제 중심 시장이며, GE 헬스케어의 코크 공장 확장으로 공급 안정성이 강화되고 있지만, 유제품 잔류 기준의 엄격화라는 역풍에도 직면해 있습니다.
남미는 칠레의 칼리체를 통해 전 세계 요오드의 대부분을 공급하고 있으나, 기상 이변이나 물 부족이 공급 변동의 요인으로 작용하고 있습니다. 유니세프가 주도하는 요오드 첨가 캠페인을 통해 사하라 이남 아프리카 전역에서 수요가 점차 증가하고 있으나, 물류상의 장벽은 여전히 남아 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the iodine market size is projected to expand from 45.23 kilotons in 2025 and 47.70 kilotons in 2026 to 62.26 kilotons by 2031, registering a CAGR of 5.47% between 2026 to 2031.
This report is Segmented by Source (Caliche Ore, Underground Brine, Seaweed, and Recycling), Form (Organic Compounds, Elementals and Isotopes, and Inorganic Salts and Complexes), End-User Industry (Medical, Animal Feed, Biocides, Fluorochemicals, Nylon, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Iodine Market Trends and Insights
Rising Demand for X-Ray/CT Contrast Media
Roughly 75 million diagnostic exams per year use iodinated contrast agents, and about 48% of U.S. CT scans require contrast enhancement. GE Healthcare invested USD 30 million in its Cork, Ireland plant during 2024 to secure additional supply as global contrast demand is expected to double within a decade. Photon-counting CT technology lowers per-patient iodine usage by around 10% per 5 keV energy bin, yet absolute volumes keep rising as screening programs expand. SQM signed multi-year feedstock contracts with pharmaceutical intermediaries to lock in medical-grade output at premium pricing, insulating revenue from commodity swings. The WHO lists iodinated contrast agents on its essential medicines inventory, guaranteeing baseline procurement even in low-income health systems.
Government-Mandated Salt Iodization Programs
Roughly 88% of households used iodized salt in 2024, up from 86% in 2020, yet more than 2 billion people remain at risk of deficiency. India's 2024 mandate for double fortification with iodine and iron has lifted per-kilogram iodine loading, expanding the iodine market across rural retail channels. Southeast Asian and Sub-Saharan regulators are tightening compliance audits, raising the technical threshold for suppliers that must now document ISO 9001 traceability. Low-purity grades funneled into fortification create a price floor that stabilizes producer cash flows during cyclical downturns in higher-spec segments. UNICEF's bulk procurement favors vendors with proven logistics, elevating barriers for small regional entrants.
Volatile Pricing Linked to Chilean Caliche Output Swings
Chile supplies roughly 60% of world iodine, and 2024 precipitation events in the Atacama Desert curtailed ore processing, pushing spot prices to USD 38,000 t-1 from USD 27,000 t-1 the prior year. Asia-Pacific buyers face 8-12-week transit windows, and strategic stockpiles seldom exceed 60 days, magnifying volatility. Underground brine output is scaling at a 5.56% CAGR but remains an order of magnitude smaller than caliche, limiting near-term diversification. Producers with long-term offtake contracts are better cushioned, yet converters in contrast media and catalysts report margin compression when spot jumps exceed USD 5,000 t-1. Weather risk and nitrate-mining cycles therefore remain the leading supply-side drag on the iodine market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of LCD/OLED Polarizer Film Manufacturing
- Regulatory Push for Low-Carbon Fluorochemical Routes
- Toxicity and Specialized Handling Costs for Bulk Iodine
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Caliche ore still held 50.88% of the iodine market share in 2025, anchored by SQM's 16,200 t output, yet underground brine is growing faster at a 5.56% CAGR, reflecting end-users' pursuit of supply diversity. The iodine market size attributable to brine is projected to rise as operators such as Iofina commission new wells in the U.S. Permian Basin.
Brine production bypasses nitrate-mining cycles and exploits flowback water that would otherwise be reinjected, lowering marginal extraction costs despite iodine grades below 0.1 g L-1. Japanese firms extracting brine at roughly 1,000-fold seawater concentration supply 30% of global volume, proving commercial viability. Recycling-led by GE Healthcare's take-back network-recovered 18% of iodine used in contrast agents during 2025, signaling white-space for closed-loop growth. Seaweed now accounts for low supply because of labor intensity and low yields.
Complete Report Scope:
- By Source
- Caliche Ore
- Underground Brine
- Seaweed
- Recycling
- By Form
- Organic Compounds
- Elementals and Isotopes
- Inorganic Salts and Complexes
- By End-user Industry
- Medical (X-ray contrast media, pharmaceuticals, iodophors and povidone-iodine)
- Animal Feed
- Biocides
- Optical Polarizing Films
- Fluorochemicals
- Nylon
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific led the iodine market with 34.31% of world demand in 2025 and is expanding at a 6.89% CAGR through 2031. China's LCD polarizer film production and India's double-fortified salt program underpin the region's volume gains. Japan, sourcing brine at 0.1 g L-1, remains a pivotal supplier to downstream processors across the bloc.
North America benefits from rising brine output, notably Iofina's additional 170-220 t yr-1 Permian plant slated for H2 2026. Europe remains contrast-media-centric; GE Healthcare's Cork expansion reinforces supply security yet faces headwinds from stricter dairy residue caps.
South America supplies majority of global iodine via Chilean caliche, but weather disruptions and water scarcity inject volatility. UNICEF-led iodization drives incremental demand across Sub-Saharan Africa, though logistics barriers persist.
- Algorta Norte S.A.
- Calibre Chemicals Pvt. Ltd.
- Cosayach
- Deep Water Chemicals
- Eskay Iodine
- Glide Chem Private Limited
- GODO SHIGEN Co., Ltd.
- Infinium Pharmachem Limited
- Iochem Corporation
- Iofina plc
- ISE CHEMICALS CORPORATION
- K&O Energy Group Inc.
- Nippoh Chemicals Co. Ltd
- Parad Corporation Pvt Ltd
- Proto Chemical Industries
- Salvi Chemical Industries Ltd
- Samrat Pharmachem Limited
- SQM
- TOHO EARTHTECH,INC
- Woodward Iodine LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for X-Ray/CT Contrast Media
- 4.2.2 Government-Mandated Salt Iodization Programs
- 4.2.3 Expansion of LCD/OLED Polarizer Film Manufacturing
- 4.2.4 Rapid Adoption of Iodine-Based Electrolytes in Next-Gen Aqueous Batteries
- 4.2.5 Regulatory Push for Low-Carbon Fluorochemical Routes That Require Iodine Catalysts
- 4.3 Market Restraints
- 4.3.1 Volatile Pricing Linked to Chilean Caliche Output Swings
- 4.3.2 Toxicity and Specialised Handling Costs for Bulk Iodine
- 4.3.3 Tightening EU Limits on Residual Iodine in Dairy Products
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Source
- 5.1.1 Caliche Ore
- 5.1.2 Underground Brine
- 5.1.3 Seaweed
- 5.1.4 Recycling
- 5.2 By Form
- 5.2.1 Organic Compounds
- 5.2.2 Elementals and Isotopes
- 5.2.3 Inorganic Salts and Complexes
- 5.3 By End-user Industry
- 5.3.1 Medical (X-ray contrast media, pharmaceuticals, iodophors and povidone-iodine)
- 5.3.2 Animal Feed
- 5.3.3 Biocides
- 5.3.4 Optical Polarizing Films
- 5.3.5 Fluorochemicals
- 5.3.6 Nylon
- 5.3.7 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Algorta Norte S.A.
- 6.4.2 Calibre Chemicals Pvt. Ltd.
- 6.4.3 Cosayach
- 6.4.4 Deep Water Chemicals
- 6.4.5 Eskay Iodine
- 6.4.6 Glide Chem Private Limited
- 6.4.7 GODO SHIGEN Co., Ltd.
- 6.4.8 Infinium Pharmachem Limited
- 6.4.9 Iochem Corporation
- 6.4.10 Iofina plc
- 6.4.11 ISE CHEMICALS CORPORATION
- 6.4.12 K&O Energy Group Inc.
- 6.4.13 Nippoh Chemicals Co. Ltd
- 6.4.14 Parad Corporation Pvt Ltd
- 6.4.15 Proto Chemical Industries
- 6.4.16 Salvi Chemical Industries Ltd
- 6.4.17 Samrat Pharmachem Limited
- 6.4.18 SQM
- 6.4.19 TOHO EARTHTECH,INC
- 6.4.20 Woodward Iodine LLC
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


