|
시장보고서
상품코드
2124079
충격 보강제 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Impact Modifier - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
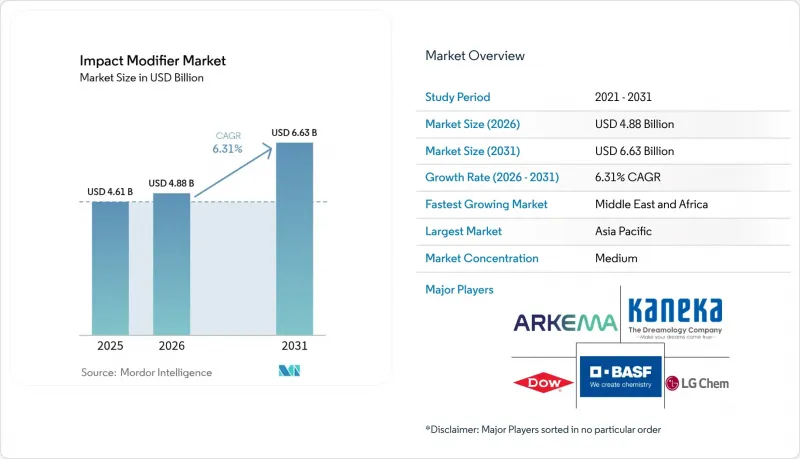
에 의하면, 충격 보강제 시장 규모는 2025년 46억 1,000만 달러로 평가되었고, 2026년 48억 8,000만 달러에서 2031년까지 66억 3,000만 달러로 확대될 것으로 예측되며, 2026-2031년 연평균 복합 성장률(CAGR)은 6.31%를 나타낼 전망입니다.
본 보고서는 유형별(아크릴로니트릴·부타디엔·스티렌, 아크릴계 충격 보강제, 아크릴로니트릴·스티렌·아크릴레이트 등), 용도별(폴리염화비닐, 나일론 등), 최종 사용자 산업별(포장, 건설, 자동차 등), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 충격 보강제 시장 동향 및 인사이트
포장 수요 증가
세계 전자상거래 업계에서는 배송 시 포장 내구성 기준이 엄격해지고 있으며, 이에 따라 2025년에는 경질 클램쉘 및 용기용 내충격성 수지 수요가 전년 대비 7.2% 증가할 것으로 전망됩니다. 아크릴 계열 등급 덕분에 투명한 PET 트레이는 반복적인 동결·해동 사이클 후에도 투명성을 유지할 수 있습니다. 이러한 성능은 2025년에 22% 성장한 북미의 밀키트 서비스에 필수적입니다. 89개국에서 시행되고 있는 재사용 가능한 용기에 관한 법규로 인해, 75°C에서 500회의 식기세척기 세척 주기를 견딜 수 있는 에틸렌·프로파일렌·디엔·모노머(EPDM) 계열 개질제에 대한 수요가 증가하고 있습니다. 2025년 미국 FDA가 발표한 식품 접촉 규정에 따라 잔류 아크릴레이트 단량체의 상한선이 100억분의 50으로 설정됨에 따라, 생산자들은 초임계 CO2 추출법을 채택할 수밖에 없게 되었고, 이로 인해 제조 비용이 1kg당 0.18달러 상승했습니다. 그 결과, 자체 추출 시스템을 보유한 대형 생산자들은 이 추가 비용을 감당할 수 없는 위탁 블렌딩 업체들로부터 시장 점유율을 빼앗고 있습니다.
PVC 파이프·프로파일 붐
인도, 인도네시아, 베트남 각지의 지자체 프로그램에 따라 아연 도금 철관에서 PVC로의 전환이 가속화되었습니다. 그 이유로 PVC의 설치 비용이 1미터당 42달러인 반면, 연성 주철은 68달러이며, 50년의 내구 수명이 보장된다는 점이 꼽히고 있습니다. 염소화 폴리에틸렌(CPE) 개질제는 2025년에 압력관 부문의 62%를 차지했습니다. 이는 용접선의 강도가 베이스 수지의 값의 85% 이상을 유지하고, 접합부가 2.5 MPa에서 ISO 13953 수압 시험을 통과할 수 있기 때문입니다. 중국의 ‘제14차 5개년 계획’에서는 도시 상수도망에 4조 8,000억 위안(6,700억 달러)이 배정되었으며, 2025년에는 78만 메트르톤의 내충격성 PVC가 소비될 전망입니다. 유럽에서는 패시브 하우스 기준(0.8 W/m²K)을 충족하는 삼중 유리 사양의 PVC 창호용 프로파일 제조에 2025년에 29만 메트르톤의 아크릴로니트릴-스티렌-아크릴레이트(ASA)가 소비되었습니다. 2024년 EU 건설 제품 규정에 따른 인증으로 인해 제3자 시험 비용이 Kg당 0.09유로 증가했으나, 이 추가 비용을 상쇄할 수 있는 수직 통합형 컴파운더에게는 유리하게 작용했습니다.
원자재 가격 변동
스티렌의 현물 가격은 2025년 1월 톤당 950달러에서 9월 1,280달러까지 변동했으며, 아시아 크래커의 가동 중단 및 파생 제품 수요 감소를 계기로 연간 35%의 가격 차이가 발생했습니다. 부타디엔은 2025년 4분기에 1메트릭톤당 1,520달러에 달했습니다. 이는 미국 멕시코만 연안의 크래커가 에틸렌 1톤당 부타디엔 수율이 40% 낮은 에탄을 원료로 우선적으로 사용했기 때문입니다. 장기 모노머 계약을 체결하지 않은 비통합형 컴파운드 제조업체는 Kg당 0.41달러의 원가 상승분을 흡수했으나, 인도의 공공 입찰에서는 연간 가격 상승폭이 인플레이션율에 1포인트를 더한 수준으로 제한되어 있기 때문에하류 PVC 파이프 압출 제조업체는 가격 전가율을 3% 미만으로 억제했습니다. 세계 생산 능력의 38%를 차지하는 수직 통합형 제조업체는 원료 가격 변동을 내부적으로 흡수함으로써 이익률을 유지하고, 경쟁사와의 격차를 벌렸습니다.
부문별 분석
ABS는 가전제품 외장재 및 자동차 내장재 분야에서 비용 효율이 뛰어난 인성을 발휘한 것을 바탕으로, 2025년 충격 보강제 시장에서 33.48%의 점유율을 차지했습니다. 이 부문에서 ABS는 충격 보강제 시장 규모에 15억 4,000만 달러를 기여하고 있으며, 불투명한 마감과 15 kJ/m²의 노치 이조트 충격 강도가 충분한 용도에서 널리 수용되고 있음을 반영합니다. 아크릴계 등급은 규모는 작지만, 투명한 PVC 창틀이나 PET 클램쉘 용기의 경우 500시간의 QUV 노출 후에도 내후성을 유지하는 투명성이 요구되기 때문에 연평균 성장률(CAGR) 6.42%로 성장하고 있습니다. MBS는 2025년에 경질 PVC 파이프 소비량의 22%를 차지했으나, 중국 수출업체들이 유럽의 동종 제품보다 14% 저렴한 가격으로 공급하고 있어 가격 압박에 직면해 있습니다.
아크릴로니트릴·스티렌·아크릴레이트(ASA)는 -30°C에서의 충격 유지력과 UV 내구성이 결정적인 요소가 되는 실외용 사이딩 및 자동차 외장 패널용으로 확대되고 있습니다. CPE는 식수용 파이프에서 2.5 MPa의 정수압 하에서도 연성을 유지할 수 있어 시장 점유율을 확보했습니다. EPDM은 여전히 틈새 시장으로 남아 있지만, 식기세척기에서의 내구성이 재사용 가능한 용기에 대한 규제 요건을 충족하고 있습니다. 2025년에 출시된 말레산 무수물 그래프트화 아크릴계 변종은 PCR PVC에서 버진 소재의 인성 92%를 회복하고 있으며, 표준 등급에 비해 Kg당 0.90달러의 프리미엄 가격이 책정되어 있습니다.
지역별 분석
아시아태평양은 2025년에 충격 보강제 시장의 47.26%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 6.35%로 성장할 전망입니다. 중국에서만 ‘일대일로’ 프로젝트를 위해 680만 미터톤 PVC 파이프를 생산한 반면, 인도의 저소득층 주택 계획에서는 충격 보강제 PVC 도관이 47만 미터톤 소비되었습니다. 아세안(ASEAN) 국가들에서는 2025년에 12,400킬로미터의 농촌 용수 파이프라인이 부설되었으며, 베트남과 태국이 설치를 주도했습니다. 일본과 한국은 2027년 이후 양산형 BEV(배터리 전기자동차)용 배터리 케이스를 대상으로 한 탄소섬유 대응 개질제에 관한 47건의 특허를 출원했습니다. GB 18581에 따른 규제 강화로 인해 중국 개질제 공장의 3분의 1 이상이 VOC 산화 설비 설치를 강요받게 되었으며, 통합형 대기업에 의한 생산 능력 집약이 진행되었습니다.
북미 시장 점유율은 미국 환경보호청(EPA)의 연비 규제로 인해 강재에서 폴리머로의 대체가 가속화되면서 확대되었습니다. 캐나다에서는 음용수 시스템이 갱신된 반면, 멕시코에서는 180억 달러 규모의 자동차 산업 니어쇼어링 붐으로 인해 엔지니어링 플라스틱 수요가 확대되었습니다. 캘리포니아주의 ‘더 안전한 소비자 제품(Safer Consumer Products)’ 프레임워크에 따라 스티렌계 첨가물에 대한 추가 시험 요건이 도입되어 경질 포장재의 출시가 일시적으로 지연되었습니다.
유럽에서는 ECHA(유럽화학물질청)의 2025년 프탈레이트 규제와 ‘포장 및 포장 폐기물 규정’에 따른 30% PCR(재활용 플라스틱) 사용 의무로 인해 이익률에 압박이 가해지고 있습니다. 독일, 프랑스, 이탈리아 3개국이 이 지역 수요 대부분을 공동으로 흡수하고 있으며, 그 대부분은 ‘패시브 하우스’의 0.8 W/m²K 기준을 충족해야 하는 창문용 프로파일 압출 성형 제품입니다.
남미는 수요가 가장 낮았으나, 브라질에서는 780만 호의 주택 부족이 PVC 수요를 뒷받침하고 있으며, 아르헨티나의 리튬 사업에서는 증발지용 내충격성 라이너가 지정되었습니다. 중동 및 아프리카은 사우디아라비아의 3조 2,000억 달러 규모의 ‘비전 2030’ 계획에서 150만 호의 주택 및 8,500km의 도로를 위해 내충격성 개질 폴리머가 지정됨에 따라 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다. 표준의 차이는 여전히 존재합니다. SASO(사우디아라비아 표준화 기구)는 잔류 스티렌을 120 mg/kg까지 허용하는 반면, EU의 상한선은 100 mg/kg이므로, 걸프 지역 생산자들은 비식품 용도에서 유럽 수출업체보다 최대 12% 저렴한 가격을 책정할 수 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측(금액 기준)
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the impact modifier market size is projected to expand from USD 4.61 billion in 2025 and USD 4.88 billion in 2026 to USD 6.63 billion by 2031, registering a CAGR of 6.31% between 2026 to 2031.
This report is Segmented by Type (Acrylonitrile Butadiene Styrene, Acrylic Impact Modifiers, Acrylonitrile Styrene Acrylate, and More), Application (Polyvinyl Chloride, Nylon, and More), End-User Industry (Packaging, Construction, Automotive, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Impact Modifier Market Trends and Insights
Growing Packaging Demand
Global e-commerce has tightened package-drop durability standards, lifting impact-modified resin offtake for rigid clamshells and tubs by 7.2% year over year in 2025. Acrylic grades permit clear PET trays to retain transparency after repeated freeze-thaw cycles, a performance essential for North American meal-kit services that expanded 22% in 2025. Reusable-container legislation in 89 countries channels demand toward ethylene-propylene-diene-monomer (EPDM) modifiers that withstand 500 dish-washer cycles at 75°C. Food-contact rules published by the U.S. FDA in 2025 cap residual acrylate monomers at 50 parts per billion, prompting producers to adopt super-critical CO2 extraction that raises manufacturing cost by USD 0.18 per kilogram. Larger producers with in-house extraction systems are therefore capturing share from contract blenders unable to absorb the added expense.
PVC Pipe & Profile Boom
Municipal programs across India, Indonesia and Vietnam accelerated the switch from galvanized iron to PVC, citing installed costs of USD 42 per meter for PVC versus USD 68 for ductile iron and a 50-year service-life guarantee. Chlorinated polyethylene (CPE) modifiers captured 62% of the pressure-pipe segment in 2025 because they retain weld-line strength above 85% of base-resin values, enabling joints to pass ISO 13953 hydrostatic tests at 2.5 MPa. China's 14th Five-Year Plan earmarked CNY 4.8 trillion (USD 670 billion) for urban water networks, absorbing 780,000 metric tons of impact-modified PVC in 2025. In Europe, triple-glazed PVC window profiles satisfying the Passive House 0.8 W/m2K standard consumed 290,000 metric tons of acrylonitrile-styrene-acrylate (ASA) in 2025. Certification under the EU Construction Products Regulation 2024 lifted third-party testing expenditure by EUR 0.09 per kilogram, favoring vertically integrated compounders able to amortize the added cost.
Raw-Material Price Volatility
Styrene spot prices swung between USD 950 per metric ton in January 2025 and USD 1,280 in September, a 35% intra-year spread triggered by Asian cracker outages and derivative-demand dips. Butadiene touched USD 1,520 per metric ton in Q4 2025 as U.S. Gulf Coast crackers favored ethane feedstocks that yield 40% less butadiene per ton of ethylene. Non-integrated compounders lacking long-term monomer contracts absorbed USD 0.41 per kilogram cost upticks, yet downstream PVC-pipe extruders kept pass-through below 3% because public tenders in India cap annual escalation at inflation plus one point. Vertically integrated producers representing 38% of global capacity preserved margins by internalizing feedstock swings, widening the competitive gap.
Other drivers and restraints analyzed in the detailed report include:
- Construction-Led Resin Uptake in APAC
- Automotive Lightweighting & Safety Focus
- Tightening VOC & PVC Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
ABS commanded 33.48% of the impact modifiers market in 2025 on the back of cost-effective toughness for appliance housings and automotive interiors. Within this segment, ABS contributed USD 1.54 billion to the impact modifiers market size, reflecting broad acceptance where opaque finishes and 15 kJ/m2 notched Izod impact strength are sufficient. Acrylic grades, though smaller, are growing at 6.42% CAGR because transparent PVC window profiles and PET clamshells demand weather-stable clarity after 500-hour QUV exposure. MBS occupied 22% of rigid-PVC pipe consumption in 2025 but faces price pressure as Chinese exporters undercut European equivalents by 14%.
Acrylonitrile-styrene-acrylate (ASA) expands for outdoor siding and automotive exterior panels where -30°C impact retention and UV durability are decisive. CPE secured a share owing to its ability to maintain ductility at 2.5 MPa hydrostatic stress for potable-water pipes. EPDM remains niche, yet its dishwasher-cycle endurance aligns with reusable-container mandates. Maleic-anhydride-grafted acrylic variants launched in 2025 now reclaim 92% of virgin toughness in PCR PVC, attracting a USD 0.90 per kilogram premium over standard grades.
Complete Report Scope:
- By Type
- Acrylonitrile Butadiene Styrene (ABS)
- Acrylic Impact Modifiers (AIM)
- Acrylonitrile Styrene Acrylate (ASA)
- Methacrylate-Butadiene- Styrene (MBS)
- Ethylene Propylene Diene Monomer (EPDM)
- Chlorinated Polyethylene (CPE)
- Other Types
- By Application
- Polyvinyl Chloride (PVC)
- Nylon
- Polybutylene Terephthalate (PBT)
- Engineering Plastics
- Other Applications
- By End-user Industry
- Packaging
- Construction
- Automotive
- Consumer Goods
- Electrical and Electronics
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific controlled 47.26% of the impact modifiers market in 2025 and will compound at 6.35% through 2031. China alone produced 6.8 million metric tons of PVC pipes for Belt-and-Road projects, while India's affordable-housing scheme consumed 470,000 metric tons of impact-modified PVC conduit. ASEAN nations placed 12,400 kilometers of rural water pipelines in 2025, with Vietnam and Thailand leading installations. Japan and South Korea filed 47 patents for carbon-fiber-compatible modifiers targeting mass-production BEV battery enclosures from 2027. Regulatory tightening under GB 18581 forced over one-third of Chinese modifier plants to install VOC oxidizers, consolidating capacity among integrated majors.
North America's share expanded as the US EPA fuel-economy rule accelerated steel-to-polymer substitution. Canada upgraded potable-water systems, while Mexico's USD 18 billion automotive near-shoring boom widened engineering-plastic demand. California's Safer Consumer Products framework introduced additional testing layers for styrene-based additives, momentarily delaying rigid-packaging launches.
Europe faces margin pressure from ECHA's 2025 phthalate restrictions and the 30% PCR requirement under the Packaging and Packaging Waste Regulation. Germany, France and Italy jointly absorbed the majority of regional volumes, predominantly window-profile extrusion that must meet the Passive House 0.8 W/m2 K threshold.
South America represented the lowest demand, with Brazil's 7.8 million-unit housing shortfall fueling PVC uptake, and Argentina's lithium operations specifying impact-modified liners for evaporation ponds. The Middle East and Africa are forecast to post the quickest CAGR as Saudi Arabia's USD 3.2 trillion Vision 2030 pipeline specifies impact-modified polymers for 1.5 million homes and 8,500 kilometers of roads. Differential standards persist: SASO allows 120 mg/kg residual styrene versus the EU cap of 100 mg/kg, enabling Gulf producers to underprice European exporters by up to 12% for non-food applications.
- Arkema
- BASF
- SI Group, Inc.
- Akdeniz Kimya
- CLARIANT
- Dow
- Evonik Industries
- Formosa Plastics Corporation
- INEOS Styrolution Group GmbH
- Kaneka Corporation
- LANXESS
- LG Chem
- Mitsubishi Chemical Corporation
- Shandong Novista Chemicals Co.,Ltd.
- Plastics Color Corporation
- Shandong Ruifeng Chemical Cp.Ltd
- SONGWON
- Sundow Polymers Co., Ltd.
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing packaging demand
- 4.2.2 PVC pipe & profile boom
- 4.2.3 Construction-led resin uptake in APAC
- 4.2.4 Automotive lightweighting & safety focus
- 4.2.5 Recycled-content plastics need compatibilizer-IM hybrids
- 4.3 Market Restraints
- 4.3.1 Raw-material price volatility (styrene, acrylates)
- 4.3.2 Tightening VOC & PVC regulations
- 4.3.3 Processing issues with high-recycle resin streams
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value )
- 5.1 By Type
- 5.1.1 Acrylonitrile Butadiene Styrene (ABS)
- 5.1.2 Acrylic Impact Modifiers (AIM)
- 5.1.3 Acrylonitrile Styrene Acrylate (ASA)
- 5.1.4 Methacrylate-Butadiene- Styrene (MBS)
- 5.1.5 Ethylene Propylene Diene Monomer (EPDM)
- 5.1.6 Chlorinated Polyethylene (CPE)
- 5.1.7 Other Types
- 5.2 By Application
- 5.2.1 Polyvinyl Chloride (PVC)
- 5.2.2 Nylon
- 5.2.3 Polybutylene Terephthalate (PBT)
- 5.2.4 Engineering Plastics
- 5.2.5 Other Applications
- 5.3 By End-user Industry
- 5.3.1 Packaging
- 5.3.2 Construction
- 5.3.3 Automotive
- 5.3.4 Consumer Goods
- 5.3.5 Electrical and Electronics
- 5.3.6 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Spain
- 5.4.3.5 Italy
- 5.4.3.6 Russia
- 5.4.3.7 NORDIC Countries
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information,Products & Services, and Recent Developments)
- 6.4.1 Arkema
- 6.4.2 BASF
- 6.4.3 SI Group, Inc.
- 6.4.4 Akdeniz Kimya
- 6.4.5 CLARIANT
- 6.4.6 Dow
- 6.4.7 Evonik Industries
- 6.4.8 Formosa Plastics Corporation
- 6.4.9 INEOS Styrolution Group GmbH
- 6.4.10 Kaneka Corporation
- 6.4.11 LANXESS
- 6.4.12 LG Chem
- 6.4.13 Mitsubishi Chemical Corporation
- 6.4.14 Shandong Novista Chemicals Co.,Ltd.
- 6.4.15 Plastics Color Corporation
- 6.4.16 Shandong Ruifeng Chemical Cp.Ltd
- 6.4.17 SONGWON
- 6.4.18 Sundow Polymers Co., Ltd.
- 6.4.19 Wacker Chemie AG
7 Market Opportunities & Future Outlook
- 7.1 White-space and Unmet-Need Assessment