|
시장보고서
상품코드
2124090
모터 모니터링 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Motor Monitoring - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
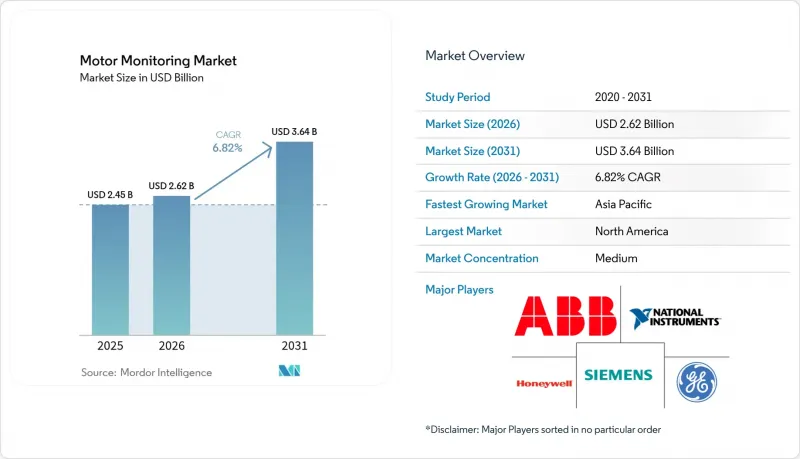
에 의하면, 모터 모니터링 시장 규모는 2025년 24억 5,000만 달러에서 2026년에는 26억 2,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 6.82%로 성장을 지속하여, 2031년까지 36억 4,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제공 분야(하드웨어, 소프트웨어 등), 배포, 모니터링 기법(진동 분석, 모터 전류 시그니처 등), 최종 사용자 산업(석유 및 가스, 에너지 및 전력 등), 모터 유형(AC 모터, DC 모터 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 모터 모니터링 시장 동향 및 인사이트
예지보전 플랫폼 도입 확대
현재 예측 유지보수 플랫폼은 진동, 전류, 음향, 열 데이터를 머신러닝 모델과 결합하여 91%의 이상 감지 정확도를 실현하고, 고장을 30-50% 줄이고 있습니다. 철강 제조업체에서는 40시간 전 고장 예측을 실현하고 있으며, 광업 사업자로부터 예기치 못한 가동 중단을 피함으로써 9배의 투자 수익률을 달성했다는 보고가 있습니다. 클라우드 분석을 통해 원시 센서 데이터가 예방적 작업 지시서로 변환되고, 예비 부품 재고 및 초과 근무를 줄일 수 있게 됨에 따라 그 경제적 이점은 더욱 명확해지고 있습니다.
무선·무배터리 센서 네트워크로의 급속한 전환
모터의 자기장에서 마이크로와트 단위의 전력을 얻는 에너지 수확 설계를 통해 배터리 교체나 배선이 불필요해져 수명 주기 비용이 대폭 절감됩니다. TDK의 i3와 같은 상용 모듈은 온보드 엣지 AI를 통합하여 가동 수명을 50% 연장하는 동시에, 산업 시설 전체에 자가 복구형 메쉬 네트워크를 구축합니다. 이러한 배선이 필요 없는 노드를 통해, 접근에 막대한 비용과 위험이 따르는 선박의 기관실이나 해양 시추 시설에서도 모니터링이 가능해집니다.
높은 초기 투자 비용(CAPEX)과 ROI의 불확실성
본격적인 도입을 위해서는 센서, 게이트웨이, 통합에 10만 달러 이상이 소요되는 경우가 많으며, 유지보수 비용을 10-40% 절감할 가능성이 있음에도 불구하고 이러한 부담이 중규모 공장의 도입을 저해하는 요인이 될 수 있습니다. 사례 연구에 따르면, 초기 모델에서는 설비가 변경될 때 데이터에 오차가 발생할 수 있으며, 알고리즘 재학습에 추가 비용이 필요하기 때문에 투자 회수 기간이 길어질 수 있습니다. 각 벤더사는 비용을 중시하는 구매자의 재무적 위험을 완화하기 위해 구독형 서비스나 단계적인 시범 도입과 같은 대응책을 마련하고 있습니다.
부문 분석
기업들이 통합, 분석, 라이프사이클 최적화를 위해 외부 전문가에게 의뢰하는 경우가 늘어나면서, 서비스 부문은 연평균 성장률(CAGR) 9.34%를 나타낼 것으로 전망됩니다. 하드웨어는 2025년 매출의 68.45%를 계속 차지할 것으로 보이지만, 복잡한 멀티벤더 환경에서는 현재 센서 조달보다 데이터 분석이 우선시되고 있습니다. 에머슨이 NI를 82억 달러에 인수한 것은 지속적인 모니터링을 보다 광범위한 자동화 계약에 통합함으로써, 수익성이 높은 서비스 수익원으로의 전환을 강조하는 것입니다.
각 하드웨어 제조업체들은 게이트웨이, 클라우드 커넥터, 관리형 대시보드를 번들로 제공함으로써 솔루션 제공업체로서의 재포지셔닝을 추진하고 있습니다. 리갈 렉스노드(Legal Rexnode)의 ‘Perceptiv’ 플랫폼은 현장 센서와 분석 기능을 통합하여, 예상 고장을 55% 줄이고 기계 수명을 40% 연장하는 것으로 보고되고 있습니다. 가치가 구성 요소에서 인사이트로 이동함에 따라, 장비, 소프트웨어, 지원을 포괄하는 하이브리드 비즈니스 모델이 모터 모니터링 시장 전체에서 표준이 되어 가고 있습니다.
2025년에도 On-Premise형 아키텍처는 매출 점유율의 73.10%를 유지했습니다. 이는 중요한 플랜트의 경우, 지연이나 데이터 주권 측면에서 여전히 로컬 제어가 선호되기 때문입니다. 그러나 사이버 보안 기준이 성숙해지고 5G 네트워크를 통해 백홀 비용이 감소함에 따라, 클라우드 도입은 연평균 성장률(CAGR) 11.75%라는 가장 높은 성장률을 보이고 있습니다. 하네웰과 버라이즌의 제휴를 통해 계량기에 셀룰러 인텔리전스가 통합되어 사용량 데이터가 분석 허브로 안전하게 스트리밍됨에 따라, 탄력을 받고 있는 하이브리드 엣지·클라우드 접근 방식이 드러나고 있습니다.
학술 연구에서는 클라우드와 SCADA 연동 시 발생하는 4가지 일반적인 취약점-공유 리소스, 내부자 위협, 보안 수준이 낮은 프로토콜, 연결성 격차-이 지적되고 있지만, 제로 트러스트 아키텍처와 네트워크 기반 침입 감지 시스템의 도입으로 위험이 점차 완화되고 있습니다. 각 제조업체들은 보안상 중요한 데이터 처리는 로컬에서 수행하는 한편, 딥러닝 워크로드나 차량 군(fleet) 벤치마킹을 클라우드로 오프로드하는 경향이 강해지고 있으며, 이러한 패턴을 통해 모터 모니터링 시장 전체에서 가동 시간을 저해하지 않으면서 확장성이 향상되고 있습니다.
지역별 분석
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 9.98%로 가장 강력한 성장 전망을 보이고 있습니다. 중국의 ‘스마트 제조 2025’ 계획 등 정부 정책이 센서 업그레이드를 뒷받침하고 있으며, 국내 벤더들은 현지 수요를 확보하기 위해 비용 경쟁력 있는 플랫폼을 잇달아 출시하고 있습니다. 지멘스의 ‘China Acceleration 2.0’과 미쓰비시 전기의 ‘Lingling’ 브랜드를 통한 신제품 라인은 이 시장을 겨냥한 특화 전략의 좋은 사례이며, 모터 모니터링 시장의 성장세를 더욱 강화하고 있습니다. 북미는 엄격한 에너지 효율 규제와 전력망 및 데이터센터의 복원력(내결함성)에 대한 투자로 인해 2025년에도 34.70%의 점유율을 차지하며 매출 1위를 유지하고 있습니다. 슈나이더 일렉트릭이 미국 내 5개 공장에 7억 달러를 투자해 진행하는 확장 계획은 에너지, 상수도, 제조업 각 부문에서 상태 기반 유지보수를 우선시하는 연방 정부의 인프라 프로그램을 지원하기 위해 공급업체들이 생산 현지화를 추진하고 있는 실제 사례를 보여줍니다. 유럽에서는 지속가능성에 관한 규제와 순환 경제 목표를 원동력으로 꾸준한 수요가 나타나고 있습니다. SKF의 ‘Infinium’ 베어링(레이저 금속 적층 공법을 통해 무기한 재사용이 가능)은 유럽공급업체들이 모니터링 솔루션을 자원 효율성과 어떻게 연계하고 있는지를 보여줍니다. 남미와 중동 및 아프리카의 신흥 지역에서는 가혹한 운영 환경 하에서 가동 시간을 향상시키기 위해 광업 및 유틸리티 프로젝트에 모니터링 기술이 도입되고 있으며, 이는 전 세계 모터 모니터링 시장의 성장을 뒷받침하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the motor monitoring market size is expected to grow from USD 2.45 billion in 2025 to USD 2.62 billion in 2026 and is forecast to reach USD 3.64 billion by 2031 at 6.82% CAGR over 2026-2031.
This report is Segmented by Offering (Hardware, Software, and More), Deployment, Monitoring Technique (Vibration Analysis, Motor Current Signature, and More), End-User Industry (Oil and Gas, Energy and Power, and More), Motor Type (AC Motors, DC Motors, and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Motor Monitoring Market Trends and Insights
Rising Adoption of Predictive Maintenance Platforms
Predictive maintenance platforms now combine vibration, current, acoustic and thermal data with machine-learning models that deliver 91% anomaly detection accuracy and cut breakdowns by 30-50%. Steel makers have demonstrated 40-hour failure forecasts, and mining operators report nine-fold returns from averting unplanned stoppages. The economic case continues to sharpen as cloud analytics turn raw sensor feeds into prescriptive work orders that reduce spare-parts inventories and overtime labour.
Rapid Shift Toward Wireless, Battery-less Sensor Networks
Energy-harvesting designs that draw micro-watts from motor magnetic fields eliminate battery swaps and wiring, slashing lifetime ownership costs. Commercial modules such as TDK's i3 integrate on-board edge-AI to extend operating life by 50% while forming self-healing mesh networks over industrial campuses. These untethered nodes unlock monitoring in ship engine rooms and offshore rigs where access is costly and hazardous.
High Upfront CAPEX and ROI Uncertainty
Full-scale deployments often require USD 100,000 or more for sensors, gateways and integration, a burden that can deter mid-sized plants despite potential 10-40% maintenance savings. Case studies show early models may drift when equipment is modified, necessitating extra spend on algorithm retraining, which prolongs payback horizons. Vendors are responding with subscription-based offerings and staged pilots to mitigate financial risk for cost-sensitive buyers.
Other drivers and restraints analyzed in the detailed report include:
- Integration of IIoT and Digital Twin Architectures
- Stricter Global Motor-Efficiency Regulations
- Shortage of Domain-Skilled Reliability Engineers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services generated a 9.34% CAGR outlook as companies turn to external specialists for integration, analytics and lifecycle optimization. While hardware retained 68.45% of 2025 revenue, complex multivendor environments now prioritize data interpretation over sensor procurement. Emerson's USD 8.2 billion purchase of NI underscores the pivot toward higher-margin service revenue streams that embed continuous monitoring into broader automation contracts.
Hardware makers are repositioning as solution providers by bundling gateways, cloud connectors and managed dashboards. Regal Rexnord's Perceptiv platform integrates field sensors with analytics that reportedly cut expected failures by 55% and stretch machine life 40%. As value migrates to insights rather than components, hybrid commercial models encompassing equipment, software and support are becoming the norm across the motor monitoring market.
On-premises architectures kept 73.10% revenue share in 2025 because critical plants still favour local control for latency and data-sovereignty reasons. Nevertheless, cloud deployments hold the fastest 11.75% CAGR as cybersecurity standards mature and 5G networks lower backhaul costs. Honeywell's collaboration with Verizon embeds cellular intelligence in meters to stream usage data securely to analytics hubs, showcasing the hybrid edge-cloud approach gaining traction.
Academic research flags four common vulnerabilities in cloud-SCADA links-shared resources, insider threats, insecure protocols and connectivity gaps-yet the adoption of zero-trust architectures and network-based intrusion detection is mitigating risk. Manufacturers increasingly process safety-critical data locally while offloading deep-learning workloads and fleet benchmarking to the cloud, a pattern that boosts scalability without compromising uptime across the motor monitoring market.
Complete Report Scope:
- By Offering
- Hardware
- Software
- Services
- By Deployment
- On-Premise
- Cloud
- By Monitoring Technique
- Vibration Analysis
- Motor Current Signature
- Thermography
- Oil Analysis
- Ultrasound and Acoustic
- By Motor Type
- AC Motors
- DC Motors
- Servo and Stepper Motors
- By End-User Industry
- Oil and Gas
- Energy and Power
- Automotive
- Mining and Metals
- Food and Beverage
- Chemicals
- Aerospace and Defense
- Other Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific holds the strongest growth outlook at a 9.98% CAGR through 2031. Government policies such as China's Smart Manufacturing 2025 blueprint are incentivizing sensor retrofits, and domestic vendors are releasing cost-competitive platforms to capture local demand. New product lines under Siemens' "China Acceleration 2.0" and Mitsubishi Electric's "Lingling" brand exemplify tailored strategies for this market, reinforcing momentum within the motor monitoring market. North America remains the revenue leader with 34.70% share in 2025 due to strict energy-efficiency rules and investments in grid and data-center resiliency. Schneider Electric's USD 700 million expansion across five U.S. plants illustrates how suppliers are localizing production to support federal infrastructure programs that prioritize condition-based maintenance in energy, water and manufacturing sectors. Europe shows steady demand fuelled by sustainability mandates and circular-economy goals. SKF's Infinium bearings-capable of indefinite reuse through laser metal deposition-demonstrate how European suppliers align monitoring solutions with resource efficiency. Emerging regions in South America and Middle East and Africa are adopting monitoring technologies in mining and utility projects to enhance uptime amid harsh operating conditions, extending the global reach of the motor monitoring market.
- ABB Ltd.
- Siemens AG
- General Electric Co.
- Emerson Electric Co.
- Honeywell International Inc.
- Schneider Electric SE
- Rockwell Automation Inc.
- Mitsubishi Electric Corp.
- National Instruments Corp.
- Banner Engineering Corp.
- SKF Group (Baker Instrument Co.)
- Fluke Corp.
- Iris Power LP
- Dynapar Corp.
- Koncar Electrical Engineering Institute Inc.にし
- Baker Hughes Co.
- Artesis A.S.
- Analog Devices Inc.
- Teledyne FLIR LLC
- WEG S.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising adoption of predictive maintenance platforms
- 4.2.2 Rapid shift toward wireless, battery-less sensor networks
- 4.2.3 Integration of IIoT and digital twin architectures
- 4.2.4 Stricter global motor-efficiency regulations
- 4.2.5 Edge-AI embedded diagnostic chips in sensors
- 4.2.6 Offshore wind turbines demand for continuous drivetrain surveillance
- 4.3 Market Restraints
- 4.3.1 High upfront CAPEX and ROI uncertainty
- 4.3.2 Shortage of domain-skilled reliability engineers
- 4.3.3 Cyber-security risk in cloud-based monitoring
- 4.3.4 Data-ownership / interoperability disputes across multi-vendor plants
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Offering
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Deployment
- 5.2.1 On-Premise
- 5.2.2 Cloud
- 5.3 By Monitoring Technique
- 5.3.1 Vibration Analysis
- 5.3.2 Motor Current Signature
- 5.3.3 Thermography
- 5.3.4 Oil Analysis
- 5.3.5 Ultrasound and Acoustic
- 5.4 By Motor Type
- 5.4.1 AC Motors
- 5.4.2 DC Motors
- 5.4.3 Servo and Stepper Motors
- 5.5 By End-User Industry
- 5.5.1 Oil and Gas
- 5.5.2 Energy and Power
- 5.5.3 Automotive
- 5.5.4 Mining and Metals
- 5.5.5 Food and Beverage
- 5.5.6 Chemicals
- 5.5.7 Aerospace and Defense
- 5.5.8 Other Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 GCC
- 5.6.5.2 Turkey
- 5.6.5.3 South Africa
- 5.6.5.4 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Siemens AG
- 6.4.3 General Electric Co.
- 6.4.4 Emerson Electric Co.
- 6.4.5 Honeywell International Inc.
- 6.4.6 Schneider Electric SE
- 6.4.7 Rockwell Automation Inc.
- 6.4.8 Mitsubishi Electric Corp.
- 6.4.9 National Instruments Corp.
- 6.4.10 Banner Engineering Corp.
- 6.4.11 SKF Group (Baker Instrument Co.)
- 6.4.12 Fluke Corp.
- 6.4.13 Iris Power LP
- 6.4.14 Dynapar Corp.
- 6.4.15 Koncar Electrical Engineering Institute Inc.にし
- 6.4.16 Baker Hughes Co.
- 6.4.17 Artesis A.S.
- 6.4.18 Analog Devices Inc.
- 6.4.19 Teledyne FLIR LLC
- 6.4.20 WEG S.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment