

|
시장보고서
상품코드
2124100
폴리염화비닐리덴(PVDC) 코팅 필름 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Polyvinylidene Chloride (PVDC) Coated Films - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 폴리염화비닐리덴(PVDC) 코팅 필름 시장 규모는 2025년에 15억 4,000만 달러로 평가되었고, 2026년 15억 8,000만 달러에서 2031년까지 18억 4,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 3.04%를 나타낼 전망입니다.
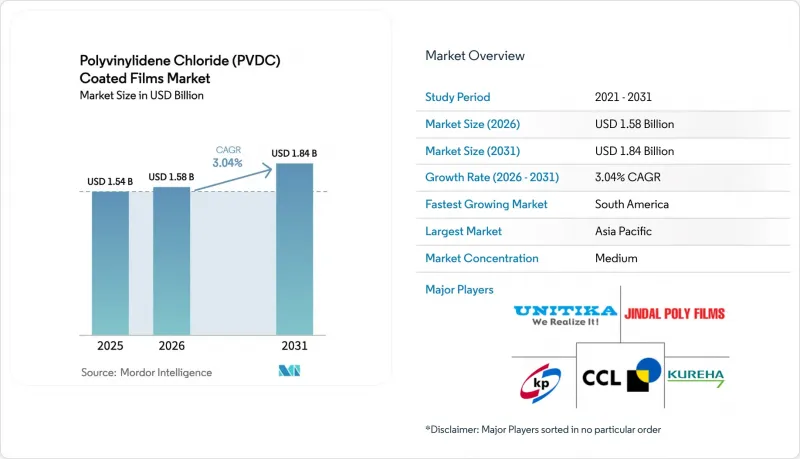
본 보고서는 필름 기판 유형별(BOPP, PET/BOPET, PVC, 기타), 용도별(식품 포장 및 의약품 블리스터 포장), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 폴리염화비닐리덴(PVDC) 코팅 필름 시장 동향 및 인사이트
가공식품 및 즉석식품의 붐
도시 지역의 소득이 증가하고 생활 방식이 점점 더 바빠짐에 따라, 분량이 조절된 상온 보관 가능한 식사에 대한 수요가 높아지고 있습니다. 이러한 식사는 냉장 유통 과정에서 장기간 신선도를 유지해야 합니다. PVDC 코팅이 적용된 BOPP 및 PET 필름은 가스 치환 포장을 가능하게 하여 지질의 산화 및 미생물에 의한 부패를 효과적으로 억제합니다. 인도와 중동의 레디밀 브랜드로부터의 주문 급증에 대응하기 위해 UFlex사는 카르나타카주에서 배리어 필름 생산을 확대되고 있습니다. 각 브랜드 소유사들은 현재 기존 설계보다 얇은 코팅을 채택하여 유통 기한을 유지하면서 비용을 절감하고 있습니다. FDA 21 CFR 177.1980 및 EU 10/2011 규정을 준수하는 것은 필수적이지만, 컨버터는 고온 살균 내구성을 인증함으로써 경쟁 우위를 확보할 수 있습니다.
의약품 블리스터 팩 채택 급증
인도 및 동유럽의 제네릭 의약품 제조업체들은 스트립 팩에서 열성형 PVC/PVDC 블리스터 팩으로 전환하고 있습니다. 이러한 움직임은 아스피린이나 항생제 등의 원료의약품(API)에 대한 ICH Q1A의 수분 차단 기준을 충족하기 위한 것입니다. PVDC가 라미네이트된 PVC는 구역 IVb의 기후 조건에서도 더 긴 보관 기간을 보장합니다. 제11장에 따른 사업 재편을 거쳤음에도 불구하고, 크록너 펜타플라스트(Klockner Pentaplast)사는 의약품 등급 PVC/PVDC에 대한 투자를 더욱 강화하고 있습니다. 이 회사는 바이오의약품에 필수적인 초고차단 등급 제품에서 발생하는 높은 이익률을 명확히 인식하고 있습니다. 유럽의약품청(EMA)이 발표한 포장 무결성 시험에 관한 지침은 업계에서 PVDC의 중요성을 확고히 했습니다. 특히, 대체재인 세라믹 산화물 코팅의 경우 그 유효성을 뒷받침할 만한 견고한 장기 현장 데이터가 없습니다는 점을 고려할 때, 이러한 경향은 더욱 두드러집니다.
EVOH 및 금속 코팅 배리어 소재와의 경쟁
영국의 Coveris사가 위탁 생산하고 있는 9층 블로우 성형 EVOH 필름은 건조 조건에서 1 cm3/m2/일 미만의 OTR을 실현하며, 폴리에틸렌 폐기물 흐름 내에서 재활용이 가능합니다. EVOH 수지 가격의 하락과 VDC 비용의 상승으로 인해, 특히 절대 습도가 낮은 건조 식품 포장 분야에서 PVDC가 기존에 가지고 있던 비용 면에서의 우위가 점차 줄어들고 있습니다. 또한, 금속 증착 PET 및 AlOx 코팅 필름은 차광성을 요구하는 스낵 식품 브랜드에게는 매력적이지만, 불투명성으로 인해 생고기 포장에는 사용이 제한되고 있습니다.
부문 분석
2025년, BOPP는 PVDC 코팅 필름 시장에서 44%의 점유율을 차지했습니다. 이는 수지 비용이 낮고 그라비아 코팅기에서 주행 속도가 빠르다는 점을 반영한 것입니다. 많은 컨버터들은 20µm의 BOPP 기재를 고속으로 능숙하게 가공하여, 뼈가 있는 육류 포장에 필수적인 인장 강도를 실현하고 있습니다. BOPET은 온화한 저온 살균 처리가 이루어지는 프리미엄 트레이용으로 공급되며, 상당한 가격 프리미엄이 붙습니다. PVC는 판매량 점유율은 미미하지만, 블리스터 포장 수요로 인해 3.67%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 폴리염화비닐(PVC) 관련 PVDC 코팅 필름 시장 규모는 향후 몇 년간 확대될 전망입니다. 또한, 폴리아미드 소시지 케이싱이나 PLA 스탠드업 파우치와 같은 특수한 틈새 시장도 ‘기타’ 카테고리에 기여하고 있습니다.
BOPP의 우위는 PVDC 없이도 낮은 OTR을 실현하는 재활용 가능한 모노 PP 리드로부터 도전을 받고 있습니다. 향후 진행될 스케일업 시험이 성공한다면, 두께가 얇아진 모노 PP는 향후 10년 말까지 PVDC 코팅 필름 시장에서 BOPP의 점유율을 위협할 가능성이 있습니다. 다만, 이러한 전환이 실현될지는 컨버터가 고습도 조건 하에서 배리어 안정성을 확인할 수 있는지에 달려 있으며, 이 점에 관해서는 현재 PVDC 구조가 우위를 점하고 있는 상황입니다.
지역별 분석
아시아태평양은 인도와 중국의 통합 필름 생산 능력 및 소매업의 급속한 현대화를 배경으로, 2025년 PVDC 코팅 필름 시장 매출의 41.38%를 차지했습니다. Jindal Poly Films와 Cosmo Films는 사내에서 PVDC 코팅을 수행하고 있어, 지역의 습도 및 유통 조건에 맞추어 배리어 특성을 미세 조정할 수 있습니다. 규제 시장으로의 인도산 블리스터 포장 수출 증가도 수요를 더욱 뒷받침하고 있습니다.
브라질과 아르헨티나를 필두로 한 남미는 2031년까지 지역별 가장 높은 연평균 성장률(CAGR) 3.57%로 성장을 지속하고, 있습니다. 슈퍼마켓의 보급이 확대됨에 따라 각 컨버터 기업들은 왁스 처리된 랩에서 냉장 보관 기간을 연장하는 PVDC 고차단 필름으로 전환을 추진하고 있습니다. 국내 규제가 재활용 가능성에 대해 비교적 완화된 편이기 때문에 유럽의 브랜드 소유주들이 사양을 엄격화하고 있는 상황에서도 PVDC에는 호재가 찾아오고 있습니다.
북미에서는 블리스터 팩의 견조한 성장과, 재활용이 불가능한 포장 형태에 벌칙을 부과하는 캘리포니아주 및 메인주에서의 조기 확대 생산자 책임(EPR) 움직임 간에 균형이 잡혀 있습니다. Syensqo사의 재활용 기술에 있어 획기적인 진전이 이루어져 선별 시스템이 PE/PVDC 다층 필름을 수용하게 된다면, 이러한 수수료를 경감할 가능성이 있습니다. 유럽은 가장 어려운 과제를 안고 있습니다. ‘포장 및 포장 폐기물 규정’에 따르면 2030년까지 대규모 재활용이 요구되며, 재활용이 불가능한 제품에는 플라스틱 세금이 부과됩니다. 일부 지자체에서는 Syensqo 프로토콜의 시범 도입이 시작되었으나, 그 수용 상황은 결코 일관되지 않습니다. 중동 및 아프리카 시장은 여전히 소규모이긴 하지만 성장을 지속하고 있으며, 사우디아라비아의 고급 유제품 부문과 남아프리카공화국의 의약품 수입이 틈새 수요를 견인하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the polyvinylidene chloride coated films market size was valued at USD 1.54 billion in 2025 and is estimated to grow from USD 1.58 billion in 2026 to reach USD 1.84 billion by 2031, at a CAGR of 3.04% during the forecast period (2026-2031).
This report is Segmented by Film Substrate Type (BOPP, PET/BOPET, PVC, and Others), Application (Food Packaging and Pharmaceutical Blister Packaging), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). Market Forecasts are Provided in Terms of Value (USD).
Global Polyvinylidene Chloride (PVDC) Coated Films Market Trends and Insights
Processed and Ready-to-Eat Food Boom
As urban incomes rise and lifestyles grow busier, there's a heightened demand for portion-controlled, shelf-stable meals. These meals need to remain fresh for an extended period during chilled distribution. PVDC-coated BOPP and PET films facilitate modified-atmosphere packaging, effectively curbing lipid oxidation and microbial spoilage. In response to surging orders from ready-meal brands in India and the Middle East, UFlex is ramping up production of barrier film in Karnataka. Brand owners are now opting for thinner coatings over traditional designs, achieving cost reductions while maintaining shelf life. While compliance with FDA 21 CFR 177.1980 and EU 10/2011 is essential, converters can gain a competitive advantage by certifying pasteurization durability at high temperatures.
Pharmaceutical Blister-Pack Adoption Surge
Producers of generic drugs in India and Eastern Europe are shifting from strip packs to thermoformed PVC/PVDC blisters. This move is to meet the ICH Q1A moisture-barrier criteria for active pharmaceutical ingredients (APIs) like aspirin and antibiotics. PVC laminated with PVDC ensures a longer shelf life even in Zone IVb climates. Despite undergoing a Chapter 11 restructuring, Klockner Pentaplast is doubling down on investments in pharmaceutical-grade PVC/PVDC. The company is keenly aware of the premium margins associated with ultra-high-barrier grades, which are essential for biologics. The European Medicines Agency's guidance on package-integrity testing has solidified PVDC's significance in the industry. This is especially true given that alternative ceramic-oxide coatings don't have robust long-term field data backing their efficacy.
Competition from EVOH and Metallized Barriers
Nine-layer blown EVOH films commissioned by Coveris in the United Kingdom provide sub-1 cm3/m2/day OTR in dry conditions and can be recycled within polyethylene waste streams. Falling EVOH resin prices and rising VDC costs are shrinking PVDC's historical cost edge, particularly in dry-goods packaging where absolute humidity is low. Metallized PET and AlOx-coated films additionally appeal to snack-food brands that demand a light barrier, although opacity restricts their use for fresh meat.
Other drivers and restraints analyzed in the detailed report include:
- Superior Gas and Moisture Barrier Performance
- Shift to Ultra-Thin (less than 15 µm) PVDC Coatings
- End-of-Life / Chlorine-Based Recycling Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
BOPP claimed a 44% share of the PVDC-coated films market in 2025, reflecting its low resin cost and high run speeds on rotogravure coaters. Many converters adeptly process 20 µm BOPP bases at high speeds, achieving the tensile strength essential for bone-in meat packaging. BOPET, catering to premium trays subjected to mild pasteurization, commands a notable price premium. While PVC holds only a modest volume share, it will log the fastest 3.67% CAGR because of blister demand. The market size for PVDC-coated films linked to polyvinyl chloride is set to rise in the coming years. Additionally, specialty niches like polyamide sausage casings and PLA stand-up pouches contribute to the "others" category.
BOPP's lead faces challenges from recyclable mono-PP lidding, achieving low OTR without the need for PVDC. Should upcoming scale-up trials prove successful, downgauged mono-PP might threaten BOPP's market share in PVDC-coated films by decade's end. However, any transition depends on converters confirming barrier stability at high relative humidity, a benchmark currently favoring PVDC structures.
Complete Report Scope:
- By Film Substrate Type
- Bi-axially Oriented Polypropylene (BOPP)
- Polyethylene Terephthalate (PET/BOPET)
- Polyvinyl Chloride (PVC)
- Others (Polyethylene, polyamide,PLA, Cellulosics etc.)
- By Application
- Food Packaging
- Pharmaceutical Blister Packaging
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 41.38% of the PVDC-coated films market revenue in 2025 on the back of India's and China's integrated film capacity and strong retail modernization. Jindal Poly Films and Cosmo Films run in-house PVDC coating that lets them tweak barrier properties to local humidity and distribution conditions. Rising blister exports from India to regulated markets further underpin demand.
South America, led by Brazil and Argentina, posts the fastest 3.57% regional CAGR to 2031. As supermarket penetration rises, converters upgrade from waxed wraps to PVDC high-barrier films that extend refrigerated shelf life. Domestic regulations are less stringent on recyclability, giving PVDC a window of opportunity even as European brand owners tighten specifications.
North America balances strong blister-pack growth with early extended-producer-responsibility (EPR) moves in California and Maine that penalize non-recyclable formats. Syensqo's recycling breakthrough could mitigate these fees if sortation systems accept PE/PVDC multilayers. Europe presents the stiffest challenge: the Packaging and Packaging Waste Regulation demands recyclability at scale by 2030 and levies plastic taxes on non-recyclables. Some municipal systems have begun to trial the Syensqo protocol, but acceptance is far from uniform. The Middle East and Africa remain small yet rising, with Saudi Arabia's premium dairy segment and South Africa's pharmaceutical imports driving niche demand.
- ACG
- Asahi Kasei Corporation
- Bilcare Limited
- Caprihans India Limited
- CCL Industries
- Cosmo Films
- Glenroy Inc.
- Huawei Pharma Foil Packaging
- Jindal Poly Films Limited
- Kaveri Metallising & Coating Ind. Private Limited
- Klockner Pentaplast
- KUREHA CORPORATION
- Liveo Research
- Perlen Packaging
- POLINAS
- Polyplex
- Qingdao Kingchuan Packaging
- RMCL
- Solvay
- Tekni-Plex Inc.
- Tipack Group
- Transparent Paper Ltd.
- UNITIKA LTD
- Valtec Italia SRL
- Vibac Group S.p.a.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Processed and Ready-to-Eat Food Boom
- 4.2.2 Pharmaceutical Blister-Pack Adoption Surge
- 4.2.3 Superior Gas- and Moisture-Barrier Performance
- 4.2.4 Shift to Ultra-Thin (less than 15 µm) PVDC Coatings
- 4.2.5 Emergence of PFAS-Free Fluorine-Free PVDC Grades
- 4.3 Market Restraints
- 4.3.1 Competition from EVOH and Metallized Barriers
- 4.3.2 End-of-Life/Chlorine-based Recycling Concerns
- 4.3.3 VDC-Monomer Supply Volatility Amid Chlor-Alkali Decarbonisation
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Film Substrate Type
- 5.1.1 Bi-axially Oriented Polypropylene (BOPP)
- 5.1.2 Polyethylene Terephthalate (PET/BOPET)
- 5.1.3 Polyvinyl Chloride (PVC)
- 5.1.4 Others (Polyethylene, polyamide,PLA, Cellulosics etc.)
- 5.2 By Application
- 5.2.1 Food Packaging
- 5.2.2 Pharmaceutical Blister Packaging
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ACG
- 6.4.2 Asahi Kasei Corporation
- 6.4.3 Bilcare Limited
- 6.4.4 Caprihans India Limited
- 6.4.5 CCL Industries
- 6.4.6 Cosmo Films
- 6.4.7 Glenroy Inc.
- 6.4.8 Huawei Pharma Foil Packaging
- 6.4.9 Jindal Poly Films Limited
- 6.4.10 Kaveri Metallising & Coating Ind. Private Limited
- 6.4.11 Klockner Pentaplast
- 6.4.12 KUREHA CORPORATION
- 6.4.13 Liveo Research
- 6.4.14 Perlen Packaging
- 6.4.15 POLINAS
- 6.4.16 Polyplex
- 6.4.17 Qingdao Kingchuan Packaging
- 6.4.18 RMCL
- 6.4.19 Solvay
- 6.4.20 Tekni-Plex Inc.
- 6.4.21 Tipack Group
- 6.4.22 Transparent Paper Ltd.
- 6.4.23 UNITIKA LTD
- 6.4.24 Valtec Italia SRL
- 6.4.25 Vibac Group S.p.a.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


