|
시장보고서
상품코드
2124115
신호 발생기 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Signal Generator - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
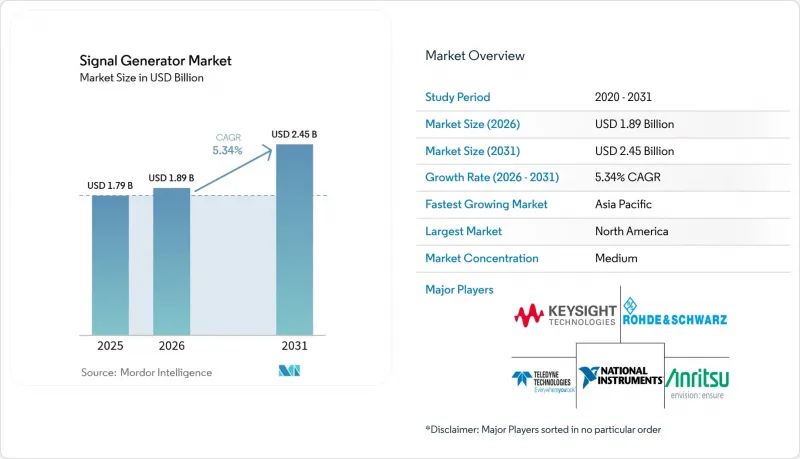
에 의하면, 2026년 신호 발생기 시장 규모는 18억 9,000만 달러로 추정되고 있어 2025년 17억 9,000만 달러에서 확대해, 2031년에는 24억 5,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 5.34%로 성장할 것으로 전망됩니다.
본 보고서는 제품별(범용 신호 발생기 등), 주파수 대역별(3GHz 미만, 3-6GHz, 6-12GHz, 12GHz 이상), 폼 팩터별(벤치탑형 등), 기술별(2G, 3G, 4G, 5G NR),용도(설계, 테스트 등), 최종 사용자 산업(통신, 자동차 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 신호 발생기 시장 동향 및 인사이트
아시아에서 5G 기지국 구축이 가속화됨에 따라 고주파 벡터 신호 발생기에 대한 수요가 증가하고 있습니다.
중국에서는 2024년 419만 기에서 2025년에는 450만 기 이상의 5G 기지국이 가동될 것으로 예상되며,통신 사업자들은 서브 6GHz 및 밀리파(mmWave) 파형을 엄격한 위상 코히어런스로 검증할 수 있는 멀티채널 벡터 신호 발생기를 구매할 수밖에 없는 상황입니다. 각 사이트에서는 RF 적합성 테스트를 위해 여러 대의 신호 발생기가 필요하며, 이러한 파급 효과는 현재 오픈 RAN 테스트를 급속도로 진행 중인 인도와 동남아시아로도 확산되고 있습니다. MIMO 및 빔포밍 검증에는 더 넓은 변조 대역폭이 필요하며, 이는 3.5-28GHz를 커버하는 하이엔드 모델에 대한 수요를 뒷받침하고 있습니다. 셀 사이트의 60%에서 채택되고 있는 마이크로파 백홀 역시 고주파 신호원의 추가 조달을 촉진하고 있습니다. 그 결과, 아시아태평양은 중기적으로 신호 발생기 시장 수요 곡선을 형성하고 있습니다.
북미 항공·방위(A&D) 분야의 레이더 현대화 프로그램: 18GHz 이상의 신호 발생기 수요를 견인
미국 국방부는 GaN 기반 AESA(능동 전자 스캐닝 안테나) 개조에 자금을 지원하고 있으며, 이로 인해 계약업체들은 8-54GHz의 위협 시나리오를 시뮬레이션할 수 있는 신호 발생기를 확보해야 하는 상황에 놓여 있습니다. 최대 54GHz까지의 코히런트 다중 채널 파형을 스트리밍하는 키사이트의 VXG 시리즈는 이러한 새로운 기준을 대표하는 제품입니다. 전자전 분야의 레드팀 훈련 및 국내 조달 의무화 조치와 맞물려, 초저위상 노이즈 발생기에 대한 수요는 향후 10년 동안 지속될 것이며, 신호 발생기 시장의 성장을 점진적으로 견인할 것입니다.
중남미 시장에서 가격을 낮추고 있는 중국산 엔트리 레벨 탁상형 장비
중국 공급업체들은 COVID-19 사태 이후 공급 정상화를 활용하여, 특히 가격에 민감한 남미 시장에서 서유럽 브랜드보다 30-40% 저렴한 가격으로 6GHz 신호 발생기를 출하하고 있습니다. 부품 공급 안정화로 인해 비용 절감 여지가 생기면서, 기존 공급업체들은 이익률 유지나 상위 시장으로의 전환을 강요받고 있습니다. 그 결과 발생하는 가격 인하 경쟁으로 인해 평균 판매 가격이 하락하고 있으며, 신호 발생기 시장의 단기적인 매출 성장이 둔화되고 있습니다.
부문 분석
범용 장비는 2025년 매출의 46.10%를 차지하며, RF 교육, 문제 해결, 레거시 무선 프로토콜 등 폭넓은 용도에서 뛰어난 범용성을 자랑합니다. 그러나 5G NR의 복잡한 수치 사양을 배경으로, 벡터 및 임의 파형 발생기는 연평균 성장률(CAGR) 6.85%를 기록하며 그 격차를 꾸준히 좁혀갈 전망입니다. 2박스 구성에서 통합형 I/Q 변조기로의 전환에 따라, 벡터 제품 신호 발생기 시장 규모는 기존 장비를 능가할 전망입니다. 현재 이 부문의 주요 제조업체들은 디지털 업컨버전 및 광대역 RF 체인을 통합하여 서브GHz에서 40GHz까지 커버함으로써, 단일 섀시로 여러 레거시 모델을 대체할 수 있게 하고 있습니다.
Rohde & Schwarz사의 SMW200A와 같이, 플러그인 헤드를 통해 밀리파 증폭기를 추가하는 소프트웨어 정의 방식의 접근을 통해, 장비를 전면적으로 교체하지 않고도 테라헤르츠 대역으로의 업그레이드가 가능해집니다. 함수 발생기는 학술 분야에서 틈새 시장 지위를 유지하고 있지만, 가격 격차가 좁혀짐에 따라 연구실에서는 대신 엔트리 레벨 AWG를 구매하는 경향이 강해지고 있습니다. OEM 연구 개발 분야 전반에 걸쳐 ‘시장 출시 기간 단축’과 ‘랙 점유 면적 감소’라는 두 가지 요인이 하이브리드형 생성·분석 벤치에 대한 수요를 뒷받침하고 있으며, 신호 발생기 시장에서 정확도와 스펙트럼 순도에 대한 프리미엄이 재확인되고 있습니다.
3-6GHz 대역은 서브 6GHz 5G, Wi-Fi 6E 및 산업용 IoT의 이용 사례를 통해 2025년 매출의 33.70%를 차지했습니다. 그러나 자동차용 레이더, 5G mm파 백홀,위성 업링크 덕분에 12GHz 이상의 주파수 대역은 연평균 성장률(CAGR) 9.12%로 확대되고 있습니다. DC-44GHz를 커버하는 듀얼 패스 아키텍처를 통해 여러 계측기를 한 대에 통합하여 교정 체인을 간소화하고 있습니다.
로데 슈바르츠(Rohde & Schwarz)사의 초안정형 가변 THz 광원에 대표되는 포토닉 기술을 통해 내부 기준 주파수는 100GHz를 훨씬 초과하는 범위까지 확장되었으며, 이는 6G 시험의 전제조건이 됩니다. GaN 프런트엔드는 출력 전력의 롤오프를 완화하지만, 갈륨 공급 제약이 우려되고 있습니다. 측정기가 더 넓은 순간 대역폭을 지원함에 따라 기존의 대역 기반 구분은 점차 희미해지고 있지만, 조달 예산은 여전히 과거의 컷오프 지점을 기준으로 하고 있어 신호 발생기 시장 전체에 대한 지출 배분에서는 명확성이 유지되고 있습니다.
지역별 분석
북미는 지속적인 항공 및 방위(A&D) 분야에 대한 자금 지원과 5G의 조기 구축에 힘입어 2025년 매출의 32.10%를 차지했습니다. 미국 연방 정부의 예산은 레이더 업그레이드를 지원하고 있는 반면, 캐나다의 양자 클러스터는 초전도 큐비트 실험을 위해 초저 위상 잡음 장비를 구매하고 있습니다. 관세 제도에 따른 국내 조달 지향으로 인해 현지 공급업체가 우대받으며 고가 대가 유지되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 6.18%로 가장 빠르게 성장하고 있는 지역입니다. 중국이 2025년까지 450만 개의 5G 매크로 기지국을 가동하겠다고 발표함에 따라, sub-6GHz 벡터 제너레이터에 대한 수요가 지속적으로 확보될 전망입니다. 대만과 한국은 2027년까지 300mm 팹에 총 540억 달러 이상을 투자할 예정이며, 이에 따라 PXI 슬롯의 도입이 지속적으로 확대될 것입니다. 정부의 세액 공제가 현지 공급망 클러스터를 활성화시켜 신호 발생기 시장의 선순환을 강화하고 있습니다.
유럽에서는 꾸준한 성장세를 보이고 있으나, 성장 속도는 둔화되고 있습니다. 슈투트가르트, 뮌헨, 예테보리 주변의 자동차용 레이더 연구 개발이 고주파 수요의 기반이 되고 있지만, 전자파 방출 규제의 강화로 인해 20 dBm을 초과하는 출력에 대한 시험의 복잡성이 증가하고 있습니다. 그러나 갈륨 공급 부족으로 인해 국내 웨이퍼 생산 라인이 가동될 때까지 40GHz 이상 모델의 납기 지연이 발생할 위험이 있어, 이로 인해 해당 지역의 신호 발생기 시장 규모는 소폭 위축될 전망입니다. 아프리카은 현재 시장 규모가 작지만, 각국이 소형 위성 제조 공장에 대한 투자를 추진하고 있습니다. 조립 및 발사 현장에서의 시험에는 휴대용 RF 발생기가 활용되고 있으며, 발사 빈도가 증가하면 추가적인 성장이 예상됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, signal generator market size in 2026 is estimated at USD 1.89 billion, growing from 2025 value of USD 1.79 billion with 2031 projections showing USD 2.45 billion, growing at 5.34% CAGR over 2026-2031.
This report is Segmented by Product (General-Purpose Signal Generator, and More), Frequency Range (Less Than 3 GHz, 3-6 GHz, 6-12 GHz, and Above 12 GHz), Form Factor (Benchtop, and More), Technology (2G, 3G, 4G, and 5G NR), Application (Designing, Testing, and More), End-User Industry (Telecommunications, Automotive, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Signal Generator Market Trends and Insights
Accelerated 5G Base-Station Roll-outs in Asia Requiring High-Frequency Vector Signal Generators
China expects more than 4.5 million live 5G base stations in 2025, up from 4.19 million in 2024, obligating operators to purchase multi-channel vector units that validate sub-6 GHz and mmWave waveforms with tight phase coherence. Each site needs several generators for RF conformance, and the domino effect now extends to India and Southeast Asia, which are fast-tracking open-RAN trials. MIMO and beamforming checks call for wider modulation bandwidths, propelling premium models that cover 3.5-28 GHz. Microwave backhaul, used by 60% of cell sites, pushes additional procurement of high-frequency sources. Consequently, Asia-Pacific is shaping the demand curve for the signal generator market well into the medium term.
Radar Upgrade Programs in North-American A&D Boosting Demand for Above 18 GHz Generators
The U.S. Department of Defense funds GaN-based AESA retrofits, prompting contractors to secure generators capable of 8-54 GHz threat-scenario emulation. Keysight's VXG series, which streams coherent multichannel waveforms up to 54 GHz, typifies the new benchmark. Compounded by electronic-warfare red-team exercises and domestic sourcing mandates, demand for ultra-low phase-noise sources will persist into the next decade, incrementally lifting the signal generator market growth.
Entry-Level Chinese Benchtop Units Eroding Prices in LATAM
Chinese vendors leverage post-COVID supply normalization to ship 6 GHz generators at prices 30-40% under Western brands, especially in price-sensitive South America. Component availability gives them cost levers, pressuring incumbents to defend margins or migrate upmarket. The resulting discounting pulls average selling prices down, trimming near-term revenue growth for the signal generator market.
Other drivers and restraints analyzed in the detailed report include:
- mmWave Automotive Radar Prototyping by European Tier-1s Fuels Multi-Channel AWG Sales
- Semiconductor Test Capacity Expansions in Taiwan and South Korea Driving PXI Modular Units
- GaAs/MMIC Shortages Delaying European Deliveries
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
General-purpose instruments accounted for 46.10% of 2025 revenue, underscoring their versatility across RF education, troubleshooting, and legacy wireless protocols. However, vector and arbitrary-waveform units, buoyed by 5G NR's complex numerologies, will post a 6.85% CAGR and steadily shrink the gap. The signal generator market size for vector products is set to outpace conventional gear as two-box architectures give way to integrated I/Q modulators. Segment leaders now embed digital up-conversion and wide-bandwidth RF chains to span sub-GHz through 40 GHz, allowing one chassis to replace several legacy models.
Software-defined moves, such as Rohde & Schwarz's SMW200A, which adds mmWave amplifiers via plug-in heads, grant path-to-terahertz upgrades without full capital refresh. Function generators keep a niche in academia, though shrinking price gaps encourage labs to purchase entry-level AWGs instead. Across OEM R&D, twin drivers - time-to-market and reduced rack footprints - sustain demand for hybrid generation-and-analysis benches, reaffirming a premium for accuracy and spectral purity in the signal generator market.
The 3-6 GHz block delivered 33.70% of 2025 turnover through sub-6 GHz 5G, Wi-Fi 6E, and industrial IoT use cases. Yet, automotive radar, 5G mmWave backhaul, and satellite uplinks propel frequencies above 12 GHz at a 9.12% CAGR. Dual-path architectures covering DC-to-44 GHz compress multiple instruments into one, simplifying calibration chains.
Photonic techniques - demonstrated by Rohde & Schwarz's ultra-stable tunable THz sources - extend internal references well past 100 GHz, a prerequisite for 6G trials. GaN front-ends mitigate output-power roll-off, though gallium constraints loom. As instruments flex wider instantaneous bandwidths, traditional band-based segmentation fades, yet procurement budgets still reference historic cutoff points, preserving clarity when allocating spend across the signal generator market.
Complete Report Scope:
- By Product
- General-Purpose Signal Generator
- RF Signal Generator
- Microwave Signal Generator
- Arbitrary Waveform Generator
- Special-Purpose Signal Generator
- Video Signal Generator
- Audio Signal Generator
- Pitch Generator
- Function Generator
- Analog Function Generator
- Digital Function Generator
- Sweep Function Generator
- General-Purpose Signal Generator
- By Frequency Range
- Less than 3 GHz
- 3-6 GHz
- 6-12 GHz
- Above 12 GHz (mmWave)
- By Form Factor
- Benchtop
- Portable/Handheld
- Modular/PXI
- By Technology
- 2G (GSM, CDMA)
- 3G (W-CDMA, CDMA2000)
- 4G (LTE, WiMAX)
- 5G NR
- By Application
- Designing
- Testing
- Manufacturing
- Certification
- Troubleshooting
- Repairing
- By End-User Industry
- Telecommunications
- Aerospace and Defense
- Automotive
- Electronics Manufacturing and Semiconductors
- Healthcare/Medical Devices
- Education and Research
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordics (Denmark, Sweden, Norway, Finland)
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Southeast Asia
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 32.10% of 2025 revenue, buoyed by persistent A&D funding and early 5G roll-outs. U.S. federal budgets back radar upgrades, while Canadian quantum clusters purchase ultra-low-phase-noise gear for superconducting-qubit experiments. Domestic sourcing preferences following tariff regimes favor local vendors, preserving premium pricing.
Asia-Pacific is the fastest-growing region at 6.18% CAGR through 2031. China's announcement of 4.5 million live 5G macro sites in 2025 guarantees sustained sub-6 GHz vector-generator volume. Taiwan and South Korea will collectively pour more than USD 54 billion into 300 mm fabs by 2027, which will continuously expand PXI slot installations. Government tax credits catalyze local supply-chain clusters, reinforcing a virtuous cycle for the signal generator market.
Europe records steady but slower growth. Automotive radar R&D around Stuttgart, Munich, and Gothenburg anchors high-frequency demand, whereas stricter electromagnetic-emission norms raise test complexity for >20 dBm outputs. Gallium shortages, however, risk delivery delays for 40+ GHz models until on-shore wafer lines come online, marginally damping the regional signal generator market size. The Middle East and Africa, though currently small, invest in sovereign small-sat factories; portable RF sources accompany assembly and launch-site testing, offering upside once launch cadence accelerates.
- Keysight Technologies Inc.
- Rohde and Schwarz GmbH and Co KG
- Tektronix Inc. (Keithley Instruments)
- Anritsu Corporation
- National Instruments Corp.
- Teledyne Technologies Inc.
- BandK Precision Corp.
- Fluke Corporation
- Yokogawa Electric Corporation
- Good Will Instrument Co. Ltd.
- AnaPico AG
- Spirent Communications plc
- Mini-Circuits
- Tabor Electronics Ltd.
- Aim-TTi (Thurlby than dar)
- Siglent Technologies Co. Ltd.
- Rigol Technologies Co. Ltd.
- Stanford Research Systems
- Fortive Corp. (Fluke/Tektronix)
- Pico Technology
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated 5G Base-Station Roll-outs in Asia Requiring High-Frequency Vector Signal Generators
- 4.2.2 Radar Upgrade Programs in North-American AandD Boosting Demand for Above 18 GHz Generators
- 4.2.3 mmWave Automotive Radar Prototyping by European Tier-1s Fuels Multi-Channel AWG Sales
- 4.2.4 Semiconductor Test capacity Expansions in Taiwan and South Korea Driving PXI Modular Units
- 4.2.5 Quantum-Computing Research Hubs (Canada, NL) Needing Ultra-Low-Phase-Noise Sources
- 4.2.6 Middle-East Small-Sat Manufacturing Spurs Portable RF Generator Adoption
- 4.3 Market Restraints
- 4.3.1 Entry-Level Chinese Benchtop Units Eroding Prices in LATAM
- 4.3.2 GaAs/MMIC Shortages Delaying European Deliveries
- 4.3.3 EU Electromagnetic Emission Norms Raising Compliance Cost for Above 20 dBm Models
- 4.3.4 RF-Test Talent Shortage in Africa and Oceania Curbing Uptake
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Product
- 5.1.1 General-Purpose Signal Generator
- 5.1.1.1 RF Signal Generator
- 5.1.1.2 Microwave Signal Generator
- 5.1.1.3 Arbitrary Waveform Generator
- 5.1.2 Special-Purpose Signal Generator
- 5.1.2.1 Video Signal Generator
- 5.1.2.2 Audio Signal Generator
- 5.1.2.3 Pitch Generator
- 5.1.3 Function Generator
- 5.1.3.1 Analog Function Generator
- 5.1.3.2 Digital Function Generator
- 5.1.3.3 Sweep Function Generator
- 5.1.1 General-Purpose Signal Generator
- 5.2 By Frequency Range
- 5.2.1 Less than 3 GHz
- 5.2.2 3-6 GHz
- 5.2.3 6-12 GHz
- 5.2.4 Above 12 GHz (mmWave)
- 5.3 By Form Factor
- 5.3.1 Benchtop
- 5.3.2 Portable/Handheld
- 5.3.3 Modular/PXI
- 5.4 By Technology
- 5.4.1 2G (GSM, CDMA)
- 5.4.2 3G (W-CDMA, CDMA2000)
- 5.4.3 4G (LTE, WiMAX)
- 5.4.4 5G NR
- 5.5 By Application
- 5.5.1 Designing
- 5.5.2 Testing
- 5.5.3 Manufacturing
- 5.5.4 Certification
- 5.5.5 Troubleshooting
- 5.5.6 Repairing
- 5.6 By End-User Industry
- 5.6.1 Telecommunications
- 5.6.2 Aerospace and Defense
- 5.6.3 Automotive
- 5.6.4 Electronics Manufacturing and Semiconductors
- 5.6.5 Healthcare/Medical Devices
- 5.6.6 Education and Research
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Nordics (Denmark, Sweden, Norway, Finland)
- 5.7.2.7 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 South Korea
- 5.7.3.4 India
- 5.7.3.5 Southeast Asia
- 5.7.3.6 Australia
- 5.7.3.7 Rest of Asia-Pacific
- 5.7.4 South America
- 5.7.4.1 Brazil
- 5.7.4.2 Argentina
- 5.7.4.3 Rest of South America
- 5.7.5 Middle East and Africa
- 5.7.5.1 Middle East
- 5.7.5.1.1 United Arab Emirates
- 5.7.5.1.2 Saudi Arabia
- 5.7.5.1.3 Rest of Middle East
- 5.7.5.2 Africa
- 5.7.5.2.1 South Africa
- 5.7.5.2.2 Nigeria
- 5.7.5.2.3 Rest of Africa
- 5.7.5.1 Middle East
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (MandA, Partnerships, Product Launches)
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-Level Overview, Market-Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Keysight Technologies Inc.
- 6.4.2 Rohde and Schwarz GmbH and Co KG
- 6.4.3 Tektronix Inc. (Keithley Instruments)
- 6.4.4 Anritsu Corporation
- 6.4.5 National Instruments Corp.
- 6.4.6 Teledyne Technologies Inc.
- 6.4.7 BandK Precision Corp.
- 6.4.8 Fluke Corporation
- 6.4.9 Yokogawa Electric Corporation
- 6.4.10 Good Will Instrument Co. Ltd.
- 6.4.11 AnaPico AG
- 6.4.12 Spirent Communications plc
- 6.4.13 Mini-Circuits
- 6.4.14 Tabor Electronics Ltd.
- 6.4.15 Aim-TTi (Thurlby than dar)
- 6.4.16 Siglent Technologies Co. Ltd.
- 6.4.17 Rigol Technologies Co. Ltd.
- 6.4.18 Stanford Research Systems
- 6.4.19 Fortive Corp. (Fluke/Tektronix)
- 6.4.20 Pico Technology
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment