

|
시장보고서
상품코드
2124118
지방 알코올 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Fatty Alcohol - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 지방 알코올 시장 규모는 2025년에 413만 톤으로 평가되어 2026년 430만 톤에서 2031년까지 526만 톤에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.09%를 나타낼 전망입니다.
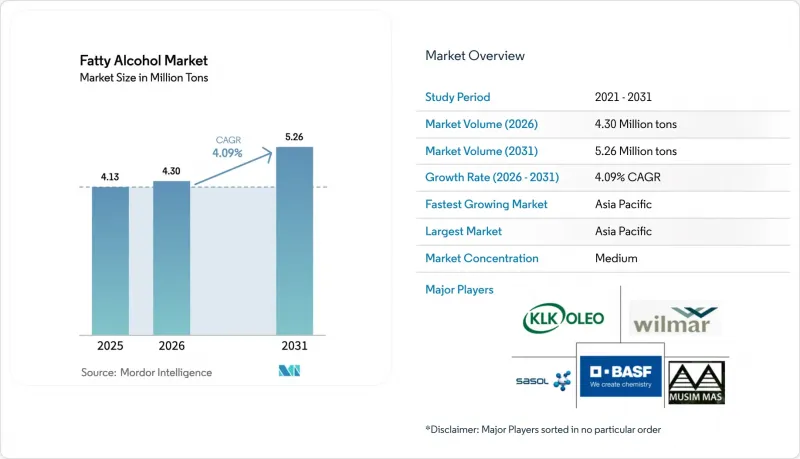
본 보고서는 원료별(천연 유래, 석유화학 유래),용도별(계면활성제, 퍼스널케어 및 화장품, 가정용·산업용 세제, 윤활유·그리스, 플라스틱 첨가제, 의약품 부형제 등), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 수량(톤) 기준으로 제시되어 있습니다.
세계 지방 알코올 시장 동향 및 인사이트
FMCG(일용소비재) 부문의 계면활성제 수요 급증
2024년, 지방 알코올 에톡실레이트를 기반으로 하는 비이온성 계면활성제는 전 세계 계면활성제 사용량의 40%를 차지했으며, 주요 FMCG 기업들은 경수 환경에서 성능을 향상시키기 위해 음이온성 계면활성제의 비율을 낮추고 있습니다. 프록터 앤 갬블(Procter & Gamble)의 특허 출원에 따르면, 황산염을 포함하지 않는 샴푸에서 1병당 지방 알코올 함유량을 최대 20%까지 늘리고 있는 것으로 밝혀졌습니다. 아시아태평양이 그 중심지가 되고 있으며, 가처분 소득 증가에 힘입어 도시 지역의 세제 소비량은 이미 1인당 8kg을 초과했습니다. 바이오 계면활성제의 양산화 지연으로 인해 지방 알코올 에톡실레이트의 가격은 톤당 1,500달러 미만을 유지하고 있어, 비용 면에서의 우위가 더욱 강화되고 있습니다. 동남아시아의 각 제조업체들은 원료 확보를 위해 팜 핵의 착유 공정에 대한 후방 통합을 추진하고 있으나, 이러한 전략으로 인해 2024년에 시행된 EU의 산림 벌채 규제에 노출될 위험이 높아지고 있습니다.
황산염 무첨가 및 저자극성 퍼스널케어 제품으로의 전환
2024년, 피부에 대한 우려와 소셜 미디어를 통한 확산을 배경으로, 무황산염 퍼스널케어 제품의 성장률은 기존 제품 라인의 2배에 달했습니다. 이러한 추세에 따라, 보습 효과로 평가받는 C16-C18 알코올과 순한 세정 베이스에서 보조 계면활성제 역할을 하는 C12-C14 알코올에 대한 수요가 증가하고 있습니다. EU 화장품 규정에서는 황산염 무첨가 표기를 의무화하고 있지는 않지만, 미래를 내다본 처방 재검토는 브랜드에게 있어 리스크 관리가 되고 있습니다. 클라리언트(Clariant)가 루카스 마이어 코스메틱스(Lucas Meyer Cosmetics)를 8억 1,000만 달러에 인수한 것은 ‘클린 뷰티’를 내세울 수 있게 해주는 특수 원료 포트폴리오에 대해 프리미엄 수준의 배수가 지불되고 있음을 보여줍니다. 이러한 추세는 바디워시나 세안제 등 카테고리를 넘어 확산되고 있으며, 예측 기간 동안 지방 알코올의 대상 시장을 약 12-15% 확대할 것으로 전망됩니다.
라우린산유 및 에틸렌 원료 가격 변동
엘니뇨 현상으로 인해 인도네시아와 말레이시아의 수확량이 감소함에 따라, 2025년 3월 팜 커널 오일 가격은 전년 동월 대비 75% 급등하여 톤당 2,063.59달러에 달했습니다. 원료비는 천연 알코올 생산 비용의 최대 70%를 차지합니다. 미국의 에탄 가격은 2024년 내내 갤런당 0.20달러 미만을 유지했으며, 이로 인해 미국의 지글러 공정 플랜트와 더 높은 브렌트 유가의 영향을 받는 유럽의 나프타 크래커 간의 비용 격차가 확대되었습니다. 중국의 석탄에서 합성 가스로의 전환 경로 덕분에, Zhejiang Jiahua는 라우린유와 에틸렌의 가격 변동 모두로부터 영향을 받지 않고 있으며, 이로 인해 지역 간 비용 격차가 두드러지게 나타나고 있습니다. 헤지 대책이 제한적이라는 점(유지 화학 기업의 불과 30%만이 팜 커널 오일 가격을 고정하고 있음)으로 인해, 이익률은 연간 최대 40%의 변동에 노출되어 있습니다.
부문별 분석
2025년 생산량의 76.91%는 천연 유래였으나, 미국에서 갤런당 0.20달러 미만의 에탄 가격과 중국에서 석탄 합성가스의 경제성을 배경으로, 석유화학 경로는 2031년까지 연평균 성장률(CAGR) 4.39%로 지방 알코올 시장을 앞지를 것으로 예측됩니다. 사솔(Sasol)은 EUDR(유럽 산림 관리 기준)의 적용 제외 대상인 합성 등급 제품을 명확하게 판매하고 있으며, 이러한 가치 제안은 산림 파괴에 관한 감사를 우려하는 유럽의 세제 제조업체들로부터 공감을 얻고 있습니다. 천연 유래 생산자들은 RSPO(지속 가능한 팜유 원탁 회의) 및 재생에너지 인증을 무기로 반격하고 있지만, 범용 계면활성제 부문에서는 저렴한 가격이 원산지보다 우선시되고 있습니다. 새로운 바이오 제조 경로는 제3의 길을 제시하고 있습니다. BASF의 CO₂에서 메탄올로의 전환 시범 프로젝트나,연창석유의 연간 150 ktpa 규모의 피셔-트로프스 공정 실증 플랜트는 모두 지방 알코올 생산을 팜유 및 화석 유래 에틸렌으로부터 분리하는 것을 목표로 하고 있으나, 그 상용화는 탄소 크레딧의 경제성에 좌우됩니다.
계면활성제 용도의 지방 알코올 시장에서는 천연 알코올이 여전히 지배적인 점유율을 유지하고 있습니다. 판매량을 유지하기 위해 동남아시아 기업들은 특수 용도 분야에 대한 투자를 추진하고 있습니다. 보습제 등급의 세틸알코올 및 스테아릴알코올은 C12-C14 세제용 등급에 비해 30%의 프리미엄이 붙습니다. 한편, 석유화학 제조업체들은 효율성 향상을 추구하고 있습니다. 미국 멕시코만 연안의 생산 거점은 저렴한 셰일 에탄을 원료로 사용하고, 연안 지역의 물류망을 활용함으로써 항해 거리가 길음에도 불구하고 말레이시아 수출업체보다 낮은 배송 비용으로 라틴아메리카에 공급하고 있습니다.
지역별 분석
아시아태평양은 2025년 생산량의 44.28%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 5.09%를 나타낼 것으로 예측되어 지방 알코올 시장의 중심지로 자리 잡고 있습니다. 중국은 연간 500만 톤 이상의 오일케미칼 생산 능력을 보유하고 있으며, 절강자화(浙江嘉華)의 연간 20만 톤 규모의 석탄 합성가스 플랜트는 동남아시아의 천연 알코올 공급업체와 동등한 비용 경쟁력을 실현하고 있습니다. 옌창 석유의 피셔-트로프스 공정 파일럿 플랜트는 원료 리스크를 더욱 분산시켜, 중국의 생산자들을 라우린산유 및 에틸렌의 가격 변동으로부터 보호할 가능성이 있습니다. 인도 수요 증가는 소비 주도형입니다. 고드레지(Godrej)사는 65개국에 수출하고 있음에도 불구하고 여전히 의약품 등급 알코올을 수입하고 있으며, 이는 품질 등급 측면에서 공급 격차를 여실히 드러내고 있습니다. 일본과 한국은 여전히 기술 수출국이며, 카오(Kao)의 독자적인 기술을 바탕으로 한 알콕실화 라인은 고급 퍼스널케어 제품에 활용되고 있습니다. 막대한 생산 능력을 보유하고 있음에도 불구하고, 아세안(ASEAN) 공급업체들은 중국이나 미국의 합성 원료 가격이 운송 비용을 밑돌고 있어 가격 압박에 직면해 있습니다.
2025년, 북미는 세계 생산량의 약 5분의 1을 차지했습니다. 셰일가스에 의한 에탄 생산량은 평균 하루 2.8 mbpd에 달하며, 이는 1 MMBtu당 3달러 미만의 원료 가격을 뒷받침하여 멕시코만 연안의 지글러 공정 플랜트의 비용 우위를 공고히 하고 있습니다. 쉘(Shell)사의 모나카 크래커(Monaca Cracker) 확장으로 인해 미국 동부의 에탄 수급 균형은 타이트해졌지만, 라틴아메리카 수출을 위한 합성 생산 능력도 강화되었습니다. EPA의 윤활유 규제와 황산염이 함유되지 않은 퍼스널케어 제품의 보급이 성장을 뒷받침하고 있지만, 그 속도는 아시아태평양(APAC)의 성장률에는 미치지 못하는 상황입니다.
2025년에는 유럽이 지방 알코올 소비의 대부분을 차지했습니다. 세제 소비는 포화 상태에 있지만, 특수 용도 분야에서는 성장이 예상됩니다. 2027년 가동이 예정된 BASF의 바이오메탄올 알코올화 플랜트는 EUDR(유럽 목재 규정) 준수로 인해 천연 유래 제품 수입에 장벽이 발생하고 있는 고순도 틈새 시장을 목표로 하고 있습니다. 사솔(Sasol)의 석유화학 등급 제품은 산림 벌채 규제를 회피할 수 있어 안정적인 구매처를 확보하고 있습니다. 북유럽 해운사들이 선박용 윤활유 전환을 주도하고 있으며, IFF-케밀라(IFF-Kemira)의 1억 3,000만 유로 규모의 핀란드 바이오폴리머 투자가 이를 뒷받침하고 있습니다.
남미 및 중동 및 아프리카에서는 지방 알코올 수요가 증가하고 있습니다. 브라질의 바이오디젤 붐은 수소화 반응용 글리세린공급원이 되고 있지만, 생산 능력이 수요를 따라가지 못해 지방 알코올 중간체의 수입이 확대되고 있습니다. 사우디아라비아는 아람코가 공급하는 유리한 조건의 에탄을 활용하고 있으며, SABIC은 잉여 올레핀을 합성 알코올로 전환하여 아시아로 수출하고 있습니다. 사하라 이남 아프리카는 여전히 시장 규모가 작지만, 사솔(Sasol)의 지역적 사업 확장을 통해 수요가 충족되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the fatty alcohol market size was valued at 4.13 million tons in 2025 and is estimated to grow from 4.30 million tons in 2026 to reach 5.26 million tons by 2031, at a CAGR of 4.09% during the forecast period (2026-2031).
This report is Segmented by Source (Natural, Petrochemical), Application (Surfactants, Personal Care and Cosmetics, Household and Industrial Cleaning, Lubricants and Greases, Plastics Additives, Pharmaceutical Excipients, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). Market Forecasts are Provided in Terms of Volume (tons).
Global Fatty Alcohol Market Trends and Insights
Surfactant Demand Boom in FMCG Sector
Nonionic surfactants built on fatty-alcohol ethoxylates represented 40% of global surfactant use in 2024, and FMCG majors are cutting anionic ratios to improve hard-water performance. Procter & Gamble's patent filings reveal sulfate-free shampoos that raise fatty-alcohol loading by up to 20% per bottle. Asia-Pacific is the epicenter; urban detergent consumption already stands above 8 kg per capita, driven by rising disposable income. Biosurfactant scale-up delays keep fatty-alcohol ethoxylates below USD 1,500 per ton, reinforcing their cost advantage. Southeast Asian producers are back-integrating into palm-kernel crushing to secure feedstock, but the strategy escalates exposure to EU deforestation rules that came into force in 2024.
Shift Toward Sulfate-Free and Milder Personal-Care Formulations
Sulfate-free personal-care products grew twice as fast as conventional lines in 2024, propelled by dermatological concerns and social-media amplification. The trend lifts demand for C16-C18 alcohols, valued for emolliency, and C12-C14 alcohols that co-surfact in mild cleansing bases. Although EU Cosmetics Regulation does not mandate sulfate-free claims, proactive reformulation has become brand risk management. Clariant's USD 810 million purchase of Lucas Meyer Cosmetics underscores premium multiples paid for specialty ingredient portfolios enabling "clean beauty" claims. Cross-category adoption extends to body washes and facial cleansers, expanding the fatty-alcohol addressable market by roughly 12-15% over the forecast horizon.
Volatile Lauric-Oil and Ethylene Feedstock Prices
Palm-kernel-oil prices surged 75% year-on-year to USD 2,063.59 per ton in March 2025 after El Nino trimmed yields in Indonesia and Malaysia, and feedstock represents up to 70% of natural-alcohol production cost. U.S. ethane stayed below USD 0.20 per gallon through 2024, sharpening cost gaps between American Ziegler plants and European naphtha crackers exposed to higher Brent prices. China's coal-to-syngas path shields Zhejiang Jiahua from both lauric oil and ethylene volatility, highlighting regional cost asymmetry. Limited hedging practices-only 30% of oleochemical firms lock in palm-kernel-oil prices-leave margins exposed to 40% intra-year swings.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Push for Biodegradable Lubricants
- Increasing Demand from Pharmaceutical Applications
- Over-Capacity in Southeast Asian Natural-Alcohol Plants
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Natural sources delivered 76.91% of the 2025 volume, but petrochemical routes are forecast to outpace the fatty alcohol market at a 4.39% CAGR through 2031 on the back of sub-USD 0.20-per-gallon U.S. ethane and coal-syngas economics in China. Sasol explicitly markets EUDR-exempt synthetic grades, a value proposition resonating with European detergent formulators wary of deforestation audits. Natural producers counter with RSPO and renewable-energy credentials, yet price overlooks provenance in commodity surfactant segments. Emerging bio-routes offer a third path: BASF's CO2-to-methanol pilot and Yanchang Petroleum's 150 ktpa Fischer-Tropsch demo each aim to decouple fatty-alcohol output from both palm oil and fossil ethylene, though commercialization hinges on carbon-credit economics.
Natural alcohols maintain dominance in the fatty alcohol market share for surfactant applications. To defend volume, Southeast Asian players are investing in specialty applications-emollient-grade cetyl and stearyl alcohols fetch 30% premiums over C12-C14 detergent grades. Petrochemical producers, meanwhile, chase efficiency gains; U.S. Gulf Coast sites leverage cheap shale-ethane feedstock and Gulf logistics to supply Latin America at a lower delivered cost than Malaysian exporters despite the longer voyage.
Complete Report Scope:
- By Source
- Natural
- Petrochemical
- By Application
- Surfactants
- Personal Care and Cosmetics
- Household and Industrial Cleaning
- Lubricants and Greases
- Plastics Additives
- Pharmaceutical Excipients
- Food Emulsifiers
- Other Industrial Uses
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Nordic Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific owned 44.28% of the 2025 volume and is projected to post a 5.09% CAGR to 2031, making it the epicenter of the fatty alcohol market. China runs more than 5 million tpa of oleochemical capacity, with Zhejiang Jiahua's 200 ktpa coal-syngas plant achieving cost parity with Southeast Asian natural-alcohol providers. Yanchang Petroleum's Fischer-Tropsch pilot further diversifies feedstock risk, potentially insulating Chinese producers from lauric-oil and ethylene volatility. India's demand growth is consumption led; Godrej exports to 65 countries yet still imports pharma-grade alcohols, illustrating a quality-grade supply gap. Japan and South Korea remain technology exporters, with Kao's proprietary alkoxylation lines serving premium personal care. Despite massive capacity, ASEAN suppliers face price pressure as Chinese and U.S. synthetic feedstocks undercut landed costs.
North America contributed about one-fifth of global volume in 2025. Shale-driven ethane output averaging 2.8 mbpd underpins sub-USD 3 per MMBtu feedstock, cementing the cost advantage of Gulf Coast Ziegler plants. Shell's Monaca cracker expansion tightened Eastern U.S. ethane balances but also added synthetic capacity for export to Latin America. EPA lubricant mandates and sulfate-free personal-care adoption sustain growth, albeit below APAC rates.
Europe accounted for the significant consumption of fatty alcohol in 2025. While detergent consumption is saturated, specialty growth abounds; BASF's bio-methanol alcoholates unit slated for 2027 targets high-purity niches where EUDR compliance raises barriers for natural imports. Sasol's petrochemical grades find ready buyers because they circumvent deforestation rules. Nordic shipping lines lead marine lubricant conversion, aided by IFF-Kemira's EUR 130 million Finnish biopolymer investment.
South America and the Middle East-Africa are witnessing rising demand for fatty alcohols. Brazil's biodiesel boom supplies glycerine streams for hydrogenation, yet capacity lags demand, prompting imports of fatty-alcohol intermediates. Saudi Arabia leverages advantaged ethane from Aramco, with SABIC funneling surplus olefins into synthetic alcohols for Asian export. Sub-Saharan Africa remains small but is served by Sasol's regional footprint.
- Arkema
- BASF
- Croda International Plc
- Emery Oleochemicals
- Godrej Industries Limited
- IOI Oleochemical
- Kao Chemicals Europe, S.L.U.
- KLK OLEO
- LG Chem
- Moeve
- Musim Mas
- Procter and Gamble
- PT Ecogreen Oleochemicals
- Sasol
- Shell
- VVF LLC
- Wilmar International Ltd.
- Zhejiang Jiahua Energy Chemical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surfactant demand boom in FMCG sector
- 4.2.2 Shift toward sulfate-free and milder personal-care formulations
- 4.2.3 Regulatory push for biodegradable lubricants
- 4.2.4 Increasing demand for fatty alcohol from pharmaceutical industry
- 4.3 Market Restraints
- 4.3.1 Volatile lauric-oil and ethylene feedstock prices
- 4.3.2 Over-capacity in SE-Asia natural alcohol plants squeezing margins
- 4.3.3 Technical hurdles in catalytic hydro-downgrading of CO2-derived alkanes
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Source
- 5.1.1 Natural
- 5.1.2 Petrochemical
- 5.2 By Application
- 5.2.1 Surfactants
- 5.2.2 Personal Care and Cosmetics
- 5.2.3 Household and Industrial Cleaning
- 5.2.4 Lubricants and Greases
- 5.2.5 Plastics Additives
- 5.2.6 Pharmaceutical Excipients
- 5.2.7 Food Emulsifiers
- 5.2.8 Other Industrial Uses
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Nordic Countries
- 5.3.3.6 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, ... Recent Developments)
- 6.4.1 Arkema
- 6.4.2 BASF
- 6.4.3 Croda International Plc
- 6.4.4 Emery Oleochemicals
- 6.4.5 Godrej Industries Limited
- 6.4.6 IOI Oleochemical
- 6.4.7 Kao Chemicals Europe, S.L.U.
- 6.4.8 KLK OLEO
- 6.4.9 LG Chem
- 6.4.10 Moeve
- 6.4.11 Musim Mas
- 6.4.12 Procter and Gamble
- 6.4.13 PT Ecogreen Oleochemicals
- 6.4.14 Sasol
- 6.4.15 Shell
- 6.4.16 VVF LLC
- 6.4.17 Wilmar International Ltd.
- 6.4.18 Zhejiang Jiahua Energy Chemical
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 C1-to-C6 bio-alcohol route commercialization (Formate and syngas fermentation)


