

|
시장보고서
상품코드
2124131
디지털 홀로그래피 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Digital Holography - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
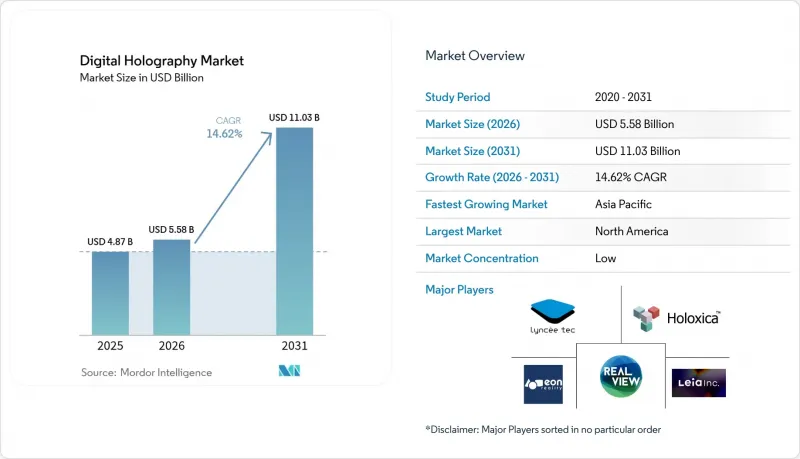
에 의하면, 디지털 홀로그래피 시장 규모는 2025년 48억 7,000만 달러로 평가되었고, 2026년에는 55억 8,000만 달러로 추정되고, 2026-2031년 CAGR 14.62%로 성장을 지속할 전망이며, 2031년에는 110억 3,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 제공 형태별(하드웨어, 소프트웨어), 기술별(오프축 홀로그래피, 인라인 홀로그래피 등), 용도별(디지털 홀로그래픽 디스플레이 등), 최종 사용자 산업별(의료 및 생명과학, 항공우주 및 방위, 자동차, 상업·소매 등) 및 지역별(북미, 유럽 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 디지털 홀로그래피 시장 동향 및 인사이트
재생의학 임상시험에서 라벨 프리 정량적 위상 이미징에 대한 수요 급증
일본 및 한국의 재생의학 연구자들은 2025년 일본이 시행한 2억 1,500만 달러 규모의 지원 프로그램의 후원을 받아, 염색 과정 없이 생세포를 연구하기 위해 디지털 홀로그래피 현미경에 대한 의존도를 높이고 있습니다. 디지털 홀로그래피는 진폭과 위상 정보를 동시에 포착할 수 있는 능력을 갖추고 있어, 연구자들은 생세포를 그 어느 때보다 상세하게 분석할 수 있게 되었으며, 기존 현미경으로는 확인할 수 없었던 세포의 형태와 동태를 밝혀낼 수 있습니다. Phase Holographic Imaging사는 2024년 1분기에 특히 재생의학 용도를 목표로 하는 스페인 및 포르투갈 시장으로의 전략적 확장을 발표했습니다. 이를 통해 형태나 세포 주기의 동태를 실시간으로 모니터링할 수 있게 됨에 따라, 임상시험 설계가 정교해지고 신약 개발 기간이 단축되어 정밀 세포 치료 분야에서의 아시아 선구자로서의 입지가 강화되었습니다. 유사한 정량적 위상 분석 워크플로우를 채택한 미국의 암 연구센터에서도 파급적인 수요가 나타났습니다.
독일 고급 자동차 제조업체들의 2026년형 모델 라인업에 홀로그래픽 HUD 채택
독일의 자동차 제조업체들은 프리미엄 차종에 홀로그래픽 헤드업 디스플레이(HUD)를 통합하는 데 있어 최첨단을 달리고 있으며, 2026년에 양산 도입이 예정되어 있습니다. BMW 그룹, 메르세데스-벤츠, 아우디는 5,000니트의 밝기를 유지하며 편광 선글라스를 착용한 상태에서도 식별 가능한, 전면 유리에 내장된 홀로그래픽 HUD를 탑재한 2026년형 모델을 출시할 것이라고 확인했습니다. 이스트만, 셀레스 홀로그래픽스, 코베스트로 각사는 이 솔루션의 핵심이 되는 홀로그래픽 인플레인 투명 디스플레이(HIPTD) 필름을 공급했습니다. 속도, 내비게이션, ADAS(첨단 운전자 보조 시스템) 알림을 운전자의 시선 내에 배치함으로써, 각 제조업체는 유로 NCAP 점수 향상과 주의 산만으로 인한 사고 감소를 목표로 하고 있습니다.
아시아태평양 파운드리에서의 고효율 4K 공간 광 변조기 공급 부족
디지털 홀로그래피 시장에서는 홀로그래픽 디스플레이 시스템의 핵심 구성 요소인 고효율 4K 공간 광 변조기(SLM)공급에 심각한 제약이 발생하고 있습니다. 아시아태평양의 파운드리, 특히 일본과 한국에서는 생산 능력의 한계와 반도체 제조 라인과의 우선순위 경쟁으로 인해 증가하는 수요에 대응하는 데 어려움을 겪고 있습니다. 이러한 공급 부족은 반도체 제조와 광학 공학 양쪽의 전문 지식을 필요로 하는 SLM 생산의 특수성으로 인해 더욱 악화되고 있습니다. 최근 조사에서는 기존 액정 SLM에 비해 고해상도 및 빠른 스위칭 속도 등의 장점을 가진 디지털 마이크로 미러 디바이스(DMD) 등 대체 방안이 검토되고 있습니다. 2025년에는 위상 제어 전용 디바이스의 현물 가격이 18% 급등했습니다.
부문 분석
2025년, 디지털 홀로그래피 시장의 61.35%를 하드웨어가 차지했습니다. 그 핵심은 레이저, 카메라, 그리고 광간섭을 실제 홀로그램으로 변환하는 공간 광 변조기입니다. 카메라는 현재 3µm 미만의 픽셀 피치로 1억 픽셀을 넘어 시스템 수준의 해상도를 향상시키고 있습니다. 한편, 반복 위상 복원, 신경망 업스케일링, 압축 모듈이 턴키 도입에 필수적인 요소로 자리 잡음에 따라, 소프트웨어 매출은 2031년까지 15억 8,000만 달러 증가할 전망입니다. UCLA 연구진은 재귀형 신경망을 활용한 재구성 기법을 입증하여 구조 유사성 지표를 40% 향상시키고 연산 시간을 15분의 1로 단축했습니다. 이는 잠재적 가치를 이끌어내는 데 소프트웨어가 수행하는 역할을 부각시키는 것입니다. 산업 분야의 OEM 구매자들은 펌웨어 업그레이드, 클라우드 렌더링 파이프라인, 온프레미스 디버깅 유틸리티를 수년에 걸친 서비스 수준 계약(SLA)에 묶은 구독 모델로 전환하고 있습니다. 이러한 변화는 벤더가 전체 스택을 패키지화하여 통합 기간을 단축하는 동시에 전환 비용을 높이는 미래를 시사하며, 그 결과 지속적인 수익의 관점에서 디지털 홀로그래피 시장 규모가 확대될 것입니다.
2세대 애플리케이션 프로그래밍 인터페이스(API)는 홀로그램 생성 엔진과 AR/VR 설계 패키지를 연동하여, 지금까지 컨텐츠 파이프라인을 분절시키던 장벽을 제거하고 있습니다. 의료 영상 진단 실험실에서는 오픈소스 Python 플러그인을 활용하여 위상 전개 워크플로우를 자동화함으로써 실험 설정 시간을 몇 시간에서 몇 분으로 단축하고 있습니다. 자동차 대시보드 공급업체는 곡면 앞유리에 레이저 변조기를 정렬하는 독자적인 보정 알고리즘의 라이선스를 취득하여, 이를 통해 현장 서비스의 물류가 간소화되고 이익률이 유지되고 있습니다. 이러한 동향을 종합해 보면, 소프트웨어는 현재 매출에서 차지하는 비중은 작지만, 디지털 홀로그래피 업계에서 장기적으로는 그에 상응하지 않을 정도의 수익성을 가져다줄 것으로 확인되었습니다.
오프축 홀로그래피는 포토리소그래피용 마스크 검사 및 항공우주 분야의 계측 시스템에 대한 꾸준한 도입으로 2025년에도 매출의 68.50%를 차지했습니다. 사용자들은 단일 노출을 통한 획득 및 고유한 노이즈 제거 기능을 높이 평가하고 있으며, 이러한 기능들은 진동이 있는 공장 현장에서도 데이터의 무결성을 유지해 줍니다. 한편, 합성 개구법 및 하이브리드 기법은 연속적으로 촬영된 이미지를 하나의 초고개구수 합성 이미지로 연결하는 멀티뷰 정렬 알고리즘에 힘입어 연평균 성장률(CAGR) 16.42%를 나타낼 것으로 예측됩니다. UCLA, 베이징 항공우주대학교, 프라운호퍼의 각 연구팀은 합성 개구법 조합을 통해 57°를 넘는 시야각을 실현했다고 보고하며, 과거 상업적 실용성을 제한하던 시야각의 장벽을 허물었습니다.
라벨 프리 현미경의 주력인 인라인 홀로그래피는 최고 해상도보다 간편한 정렬을 우선시하는 비용 중심의 대학 연구실에서 틈새 시장을 유지하고 있습니다. 2025년 4월, 나바라 공립대학교가 개발한 ‘촉각 가능한 홀로그래피’ 프로토타입은 초음파 위상 어레이를 이용하여 촉각 피드백을 추가함으로써, 박물관 및 교육 기술 분야의 시범 프로젝트를 촉진했습니다. 레이저 다이오드 가격 하락, 고정밀 서보 기술의 발전, AI 기반 재구성 기술의 융합으로 인해 하이브리드 시스템은 검사 라인에서 기존의 간섭계를 대체할 입지에 있으며, 2028년까지 시장 점유율의 5%를 합성 개구 아키텍처로 더 이동시킬 가능성이 있습니다. 공간 광 변조기(SLM)공급이 안정화된다면, 이러한 기술을 활용한 디지털 홀로그래피 시장 점유율 확대는 예측을 뛰어넘는 속도로 가속화될 가능성이 있습니다.
지역별 분석
북미는 미국 국방부의 연구개발(R&D) 예산 배분과 실리콘밸리 기업들의 시범 프로젝트에 힘입어 2025년에는 전 세계 매출의 41.70%를 차지했습니다. H.266/VVC가 대역폭 측면에서 실용 가능함이 입증됨에 따라, 미국의 통신 사업자들은 도심부의 텔레프레즌스 스튜디오 구축을 급속도로 추진하여 시카고, 댈러스, 샌프란시스코를 초기 거점으로 탈바꿈시켰습니다. 캐나다는 HUD(헤드업 디스플레이) 설계의 인큐베이터로 부상했으며, 주 정부 세액 공제를 활용하여 디트로이트와 뮌헨공급망을 뒷받침하는 광학 부품 스타트업 기업들을 유치했습니다. 2025년에는 몬트리올에 본사를 둔 센서 기업에 대한 벤처 자금 조달이 3억 달러를 넘어섰습니다.
이미 연평균 성장률(CAGR) 15.92%로 가장 빠르게 성장하고 있는 아시아태평양은 베이징의 5G-Advanced 네트워크 구축을 통해 번화가 부티크에 실시간 제품 홀로그램을 전송할 수 있게 되어, 소매용 디지털 홀로그래피 시장 규모 확대에 기여했습니다. 일본의 생명과학 복합 시설에서는 재생의학 실험에 고처리량 위상 이미징 장비가 도입된 반면, 한국의 자동차 제조업체는 HOE(홀로그래픽 광학 소자) 금형과 HUD(헤드업 디스플레이)용 전자 기기를 동기화함으로써 양산 개시까지의 주기를 단축했습니다. 인도의 전자 폐기물 문제 해결을 위한 노력의 일환으로, 사용 후 LCD 백라이트를 홀로그래피 지원 라이트 엔진으로 재사용하여 2025년에는 500톤의 매립 처분을 방지했습니다.
유럽에서는 독일의 자동차 기술 파트너십과 영국의 국민보건서비스(NHS)가 주관한 시범 사업을 통해 추진력이 유지되었습니다. ‘호라이즌 유럽’은 2025년에 첨단 포토닉스 프로젝트에 9,500만 유로를 배정했으며, 위상 전용 SLM 및 폴리머 필름 도파관 연구가 1차 지원 대상에 선정되었습니다. 이스라엘과 아랍에미리트(UAE)는 국방 분야에서의 LiDAR 도입을 추진했으며, 튀르키예는 스마트 시티용 홀로그래픽 매핑 입찰을 시작했습니다. 라틴아메리카는 체적 동영상 표준의 미비로 인해 뒤처지고 있으며, 브라질의 방송사는 사양이 명확해질 때까지 3D 스튜디오 개조를 연기했습니다. 그럼에도 불구하고 멕시코의 한 건축 사무소는 홀로그래픽을 활용한 가상 투어 기술을 통해 해외 계약을 수주하고 있으며, 이는 표준이 정립되면 잠재적 수요가 확대될 가능성을 시사합니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the digital holography market size is expected to grow from USD 4.87 billion in 2025 to USD 5.58 billion in 2026 and is forecast to reach USD 11.03 billion by 2031 at 14.62% CAGR over 2026-2031.
This report is Segmented by Offering (Hardware, and Software), Technique (Off-Axis Holography, In-Line Holography, and More), Application (Digital Holographic Displays, and More) End-User Vertical (Medical and Life Sciences, Aerospace and Defense, Automotive, Commercial and Retail, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Digital Holography Market Trends and Insights
Surge in label-free quantitative phase imaging demand in regenerative medicine trials
Japanese and South Korean regenerative-medicine investigators increasingly relied on digital holographic microscopy to study living cells without stains, supported by Japan's USD 215 million grant program in 2025. The ability of digital holography to capture both amplitude and phase information simultaneously enables researchers to analyze living cells with unprecedented detail, revealing cellular morphology and dynamics that remain invisible to conventional microscopy. Phase Holographic Imaging reported a strategic expansion into the Spanish and Portuguese markets in Q1 2024, specifically targeting regenerative medicine applications. The resulting ability to monitor morphology and cell-cycle kinetics in real time sharpened trial design, shortened discovery timelines and reinforced Asia's first-mover status in precision cell therapy. Spillover demand appeared in U.S. cancer-research centers adopting the same quantitative-phase workflows.
Adoption of holographic HUDs in premium German automotive OEM 2026 line-ups
German automotive manufacturers are at the forefront of integrating holographic head-up displays (HUDs) into their premium vehicle models, with production implementations scheduled for 2026. BMW Group, Mercedes-Benz and Audi confirmed 2026 model-year launches using windshield-embedded holographic HUDs that maintain 5 000-nit brightness and remain visible through polarized sunglasses. Eastman, Ceres Holographics and Covestro supplied Holographic In-Plane Transparent Display (HIPTD) films that anchor the solution. By relocating speed, navigation and ADAS alerts into the driver's line of sight, OEMs targeted higher Euro NCAP scores and reduced distraction-related incidents.
Sparse supply of high-efficiency 4K spatial light modulators from APAC foundries
The digital holography market faces significant supply constraints for high-efficiency 4K spatial light modulators (SLMs), a critical component in holographic display systems. APAC foundries, particularly in Japan and South Korea, are struggling to meet growing demand due to production capacity limitations and competing priorities for semiconductor manufacturing lines. This supply shortage is exacerbated by the specialized nature of SLM production, which requires expertise in both semiconductor fabrication and optical engineering. Recent research has explored alternative approaches, such as digital micromirror devices (DMDs), which offer advantages including higher resolution and faster switching speeds compared to traditional liquid crystal SLMs. Spot prices for phase-only devices spiked 18% in 2025.
Other drivers and restraints analyzed in the detailed report include:
- Standardization of H.266/VVC enabling bandwidth-light holographic telepresence on U.S. 5G networks
- Defense funding for long-range holographic LiDAR ISR payloads in Israel and UAE
- Prohibitive clean-room CAPEX (> USD 80 m) for phase-only SLM fabrication
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware captured 61.35% of digital holography market share in 2025, anchored by lasers, cameras and spatial-light modulators that convert optical interference into raw holograms. Cameras now exceed 100 MP at sub-3 µm pixel pitches, lifting system-level resolution. Meanwhile, software revenue is on course to add USD 1.58 billion through 2031 as iterative-phase retrieval, neural up-scaling and compression modules become indispensable for turnkey deployments. UCLA researchers demonstrated a recurrent-neural-network reconstruction that lifted structural-similarity metrics 40% and shortened compute time fifteen-fold, underscoring software's role in unlocking latent value. Industrial original-equipment buyers have shifted to subscription models that bundle firmware upgrades, cloud render pipelines and on-premises debugging utilities in multi-year service-level agreements. These shifts point toward a future in which vendors package complete stacks, compressing integration timelines and amplifying switching costs-thereby raising the digital holography market size in recurring-revenue terms.
Second-generation application-programming interfaces link hologram generation engines with AR/VR design packages, removing barriers that previously fragmented content pipelines. Medical imaging labs exploit open-source Python plug-ins to automate phase-unwrap workflows, cutting experiment-setup times from hours to minutes. Automotive dashboard suppliers license proprietary calibration algorithms that align laser modulators to curved windshields, simplifying field-service logistics and protecting margin. Collectively, these dynamics confirm that software, though representing the smaller top-line slice today, will deliver disproportionate long-term profitability inside the digital holography industry.
Off-axis holography retained 68.50% of revenue in 2025 owing to robust photolithography-mask inspection and aerospace metrology installations. Users appreciate its single-exposure acquisition and inherent noise rejection, which preserve data integrity on vibrating factory floors. Yet synthetic-aperture and hybrid approaches are projected to climb at a 16.42% CAGR, propelled by multiview registration algorithms that chain sequential captures into one ultra-high-numerical-aperture composite. UCLA, Beihang University and Fraunhofer teams each reported > 57° viewing angles derived from synthetic-aperture assembly, tearing down the field-of-view wall that once limited commercial viability.
In-line holography, a workhorse for label-free microscopy, maintains a niche in cost-sensitive university labs that favor simpler alignments over maximal resolution. Touchable-holography prototypes from the Public University of Navarra added tactile feedback via ultrasonic phased arrays in April 2025, prompting museum and ed-tech pilots. The confluence of decreasing laser-diode pricing, precision-servo advances and AI reconstruction now positions hybrid systems to usurp legacy interferometers in inspection lines, potentially redirecting another 5% share toward synthetic-aperture architectures by 2028. If spatial-light-modulator supply stabilizes, the digital holography market share of these techniques could accelerate faster than forecast.
Complete Report Scope:
- By Offering
- Hardware
- Lasers
- CCD/CMOS Image Sensors
- Spatial Light Modulators
- Beam Splitters and Optics
- Processors and Memory
- Software
- Reconstruction Algorithms
- Visualization/Rendering Engines
- Compression and Transmission Software
- Hardware
- By Technique
- Off-Axis Holography
- In-Line Holography
- Synthetic Aperture and Hybrid Techniques
- Touchable Holography
- By Application
- Digital Holographic Displays
- Digital Holographic Microscopy
- Holographic Telepresence and Communication
- Head-Up Displays (Automotive and Aviation)
- Data Storage and Security Authentication
- Manufacturing and Metrology Inspection
- By End-User Vertical
- Medical and Life Sciences
- Aerospace and Defense
- Automotive
- Commercial and Retail
- Education and Research Institutes
- Industrial Automation
- Media and Entertainment
- Consumer Electronics
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordics (Denmark, Sweden, Norway, Finland)
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Southeast Asia
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Gulf Cooperation Council Countries
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America captured 41.70% of global revenue in 2025, driven by Pentagon R&D allocations and Silicon Valley enterprise pilots. U.S. telecom carriers fast-tracked city-center telepresence studios after H.266/VVC proved bandwidth-viable, turning Chicago, Dallas and San Francisco into early hubs. Canada emerged as a HUD-design incubator, leveraging provincial tax credits to lure optical-component start-ups that feed Detroit and Munich supply chains. Venture funding exceeded USD 300 million in 2025 for Montreal-based sensor firms.
Asia-Pacific, already the fastest-growing region with a 15.92% CAGR, benefited from Beijing's 5G-Advanced footprint that streams real-time product holograms to high-street boutiques, advancing the digital holography market size for retail. Japanese life-science complexes adopted high-throughput phase-imaging rigs for regenerative-medicine assays, while South Korean automakers synchronized HOE tooling with HUD electronics to shorten ramp-up cycles. India's e-waste challenge repurposed obsolete LCD backlights into holography-ready light-engines, diverting 500 tons of landfill in 2025.
Europe sustained momentum through Germany's auto-tech partnerships and the UK's National Health Service pilots. Horizon Europe earmarked EUR 95 million for advanced photonics projects in 2025, with phase-only SLM and polymer-film waveguide research receiving first-round grants. Israel and the UAE advanced defense LiDAR adoption, while Turkey initiated smart-city holographic-mapping bids. Latin America trailed due to volumetric-video standard gaps; Brazil's broadcasters postponed 3D studio renovations pending specification clarity. Notwithstanding, Mexican architectural firms used holographic walk-throughs to win offshore contracts, hinting at latent demand growth once standards mature.
- RealView Imaging Ltd.
- Lyncee TEC SA
- Phase Holographic Imaging AB
- EON Reality Inc.
- Geola Digital UAB
- MetroLaser Inc.
- Leia Inc.
- Intelligent Imaging Innovations Inc.
- Light Logics Holography and Optics
- Jasper Display Corporation
- Holoxica Limited
- zSpace Inc.
- EchoPixel Inc.
- Zebra Imaging
- NKT Photonics A/S
- HYPERVSN (Baylan Ltd.)
- Ovizio Imaging Systems NV
- Realfiction ApS
- VNTANA
- Looking Glass Factory Inc.
- SeeReal Technologies GmbH
- Light Field Lab Inc.
- HoloTech Switzerland AG
- Daqri LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in label-free quantitative phase imaging demand in regenerative medicine trials across Japan and South Korea
- 4.2.2 Adoption of holographic HUDs in premium German automotive OEM 2026 line-ups
- 4.2.3 Standardization of H.266/VVC enabling bandwidth-light holographic telepresence on United States 5G networks
- 4.2.4 Defense funding for long-range holographic LiDAR ISR payloads in Israel and United Arab Emirates
- 4.2.5 Retail 5G-Advanced roll-out powering edge-rendered volumetric ads in Chinese Tier-1 malls
- 4.2.6 EU-MDR incentives for radiation-free holographic surgical guidance in French university hospitals
- 4.3 Market Restraints
- 4.3.1 Sparse supply of high-efficiency 4K spatial light modulators from Asia-Pacific foundries
- 4.3.2 Prohibitive clean-room CAPEX (Above USD 80 m) for phase-only SLM fabrication
- 4.3.3 Lack of volumetric-video standards among LATAM broadcasters hindering content roll-out
- 4.3.4 Clinician scepticism due to absence of multi-centre RCT evidence for holographic diagnostics
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Offering
- 5.1.1 Hardware
- 5.1.1.1 Lasers
- 5.1.1.2 CCD/CMOS Image Sensors
- 5.1.1.3 Spatial Light Modulators
- 5.1.1.4 Beam Splitters and Optics
- 5.1.1.5 Processors and Memory
- 5.1.2 Software
- 5.1.2.1 Reconstruction Algorithms
- 5.1.2.2 Visualization/Rendering Engines
- 5.1.2.3 Compression and Transmission Software
- 5.1.1 Hardware
- 5.2 By Technique
- 5.2.1 Off-Axis Holography
- 5.2.2 In-Line Holography
- 5.2.3 Synthetic Aperture and Hybrid Techniques
- 5.2.4 Touchable Holography
- 5.3 By Application
- 5.3.1 Digital Holographic Displays
- 5.3.2 Digital Holographic Microscopy
- 5.3.3 Holographic Telepresence and Communication
- 5.3.4 Head-Up Displays (Automotive and Aviation)
- 5.3.5 Data Storage and Security Authentication
- 5.3.6 Manufacturing and Metrology Inspection
- 5.4 By End-User Vertical
- 5.4.1 Medical and Life Sciences
- 5.4.2 Aerospace and Defense
- 5.4.3 Automotive
- 5.4.4 Commercial and Retail
- 5.4.5 Education and Research Institutes
- 5.4.6 Industrial Automation
- 5.4.7 Media and Entertainment
- 5.4.8 Consumer Electronics
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Nordics (Denmark, Sweden, Norway, Finland)
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 South Korea
- 5.5.3.4 India
- 5.5.3.5 Southeast Asia
- 5.5.3.6 Australia
- 5.5.3.7 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East
- 5.5.5.1 Gulf Cooperation Council Countries
- 5.5.5.2 Turkey
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 RealView Imaging Ltd.
- 6.4.2 Lyncee TEC SA
- 6.4.3 Phase Holographic Imaging AB
- 6.4.4 EON Reality Inc.
- 6.4.5 Geola Digital UAB
- 6.4.6 MetroLaser Inc.
- 6.4.7 Leia Inc.
- 6.4.8 Intelligent Imaging Innovations Inc.
- 6.4.9 Light Logics Holography and Optics
- 6.4.10 Jasper Display Corporation
- 6.4.11 Holoxica Limited
- 6.4.12 zSpace Inc.
- 6.4.13 EchoPixel Inc.
- 6.4.14 Zebra Imaging
- 6.4.15 NKT Photonics A/S
- 6.4.16 HYPERVSN (Baylan Ltd.)
- 6.4.17 Ovizio Imaging Systems NV
- 6.4.18 Realfiction ApS
- 6.4.19 VNTANA
- 6.4.20 Looking Glass Factory Inc.
- 6.4.21 SeeReal Technologies GmbH
- 6.4.22 Light Field Lab Inc.
- 6.4.23 HoloTech Switzerland AG
- 6.4.24 Daqri LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


