|
시장보고서
상품코드
2124139
의료용 보호 장비 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Medical Protective Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
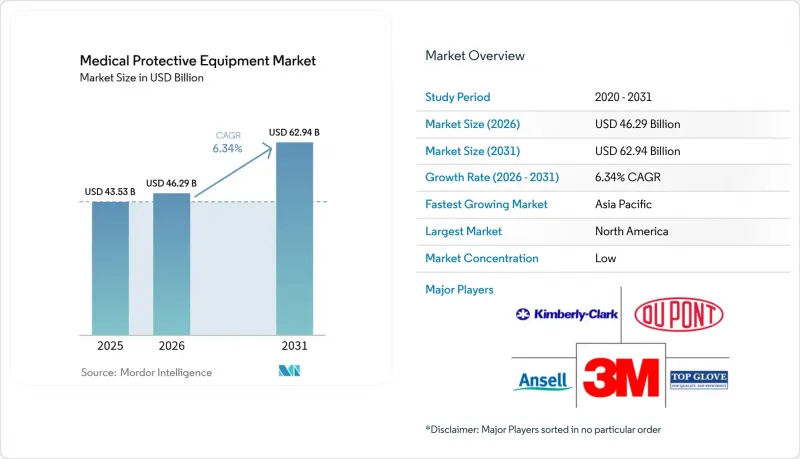
에 의하면, 의료용 보호 장비(PPE) 시장 규모는 2025년 435억 3,000만 달러로 평가되었고, 2026년에는 462억 9,000만 달러로 추정되고, 2026-2031년 CAGR 6.34%로 성장을 지속할 전망이며, 2031년에는 629억 4,000만 달러에 달할 것으로 예측됩니다.
본 보고서에서는 업계를 제품별(수술용 마스크, N95 마스크, 장갑, 가운, 안면 보호대, 기타 제품), 용도별(일회용, 재사용 가능), 최종 사용자별(병원 및 진료소, 외래수술센터(ASC), 진단실험실, 기타 최종 사용자), 그리고 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류하고 있습니다.
세계의 의료용 보호 장비 시장 동향 및 인사이트
수술 건수 증가
연기되었던 선택적 수술의 미처리 건수 증가와 고령화 진행으로 인해 전 세계 연간 수술 건수는 증가 추세를 보이고 있습니다. 특히 외래수술센터(ASC)에서는 향후 5년 동안 수술 건수가 12% 증가할 것으로 예측됩니다. 각 시술에는 장갑의 빈번한 교체, 내액성 가운, 비말 방지 쉴드가 필요하며, 이 모든 요소가 의료용 보호 장비(PPE) 시장의 확대에 직접적으로 기여하고 있습니다. 외래수술센터(ASC)는 재고를 최소화하며 운영되므로, 빈번하고 소량 단위의 납품을 보장할 수 있는 공급업체가 선호됩니다. 복잡한 최소 침습 수술에서는 현재 전용 호흡 보호구와 정밀한 배리어 드레이프가 필요해지면서 제품 범위가 더욱 확대되고 있습니다. 외래 환자 수가 증가함에 따라 조달 모델에는 수술 일정에 연동된 자동 재주문 포인트가 통합되어, 유통업체와 의료 기관 간의 협력이 더욱 긴밀해지고 있습니다.
코로나19 이후 감염 예방 요건 강화
CDC(미국 질병통제예방센터)의 업데이트된 목표에 따라, 1차 진료 클리닉이나 재택치료 방문 등 중증도가 낮은 의료 현장에서도 최소한의 PPE 재고를 유지해야 할 의무가 부과되어, 의료용 보호 장비 시장에 지속적인 수요가 정착되고 있습니다. 임상 실험실에서는 모든 기기에 대해 생물학적 안전성 위험 평가를 문서화해야 하므로, 이에 따라 더 높은 등급의 장갑과 고글에 대한 수요가 증가하고 있습니다. 핏 테스트 감사 결과, 직원 5명 중 1명은 기존 호흡용 보호구로 안전한 밀폐성을 확보하지 못하고 있는 것으로 밝혀졌으며, 이에 따라 폭넓은 사이즈 구성과 맞춤형 솔루션에 대한 수요가 증가하고 있습니다. 병원 인증 기관은 이러한 기준 준수 여부를 보상 지급 조건과 연계하고 있어 지속적인 재고 보충을 촉진하고 있습니다. 또한 규제 당국은 보관 기간 모니터링을 강화하고 있어, 시설들은 재고 부족의 위험을 감수하지 않으면서도 유통기한 만료를 최소화할 수 있는 수요 예측 소프트웨어 도입을 서두르고 있습니다.
원자재 가격 변동(니트릴 및 폴리프로필렌)
니트릴 부타디엔 고무의 가격은 분기마다 두 자릿수 변동을 보이기도 하며, 2025년 관세에 대한 추측이 새로운 불확실성을 더하고 있습니다. TSA의 장갑 수요 중 국내 조달 비중은 고작 15%에 그치고 있어, 지정학적 충격에 대한 노출 위험이 부각되고 있습니다. 장갑 제조업체들은 이중 조달 및 파생상품 계약을 통해 리스크 헤지를 하고 있지만, 병원 측은 여전히 분기별 카탈로그 가격 인상에 직면해 있습니다. 폴리프로필렌 역시 유사한 가격 변동을 겪고 있으며, 정유시설의 가동 중단이 멜트블로운 원단 공급 상황에 파급되고 있습니다. 이러한 가격 변동은 고정 가격 계약의 이익률을 압박할 뿐만 아니라, 운전 자금이 재고 완충에 할당됨으로써 설비 투자의 지연을 초래할 우려가 있습니다.
부문별 분석
장갑 시장은 2025년에 132억 4,000만 달러의 매출을 창출하여 의료용 보호 장비(PPE) 시장의 30.42%를 차지했습니다. 이는 모든 의료 시술에서의 사용과 급속한 소비에 힘입은 결과입니다. 라텍스 알레르기 환자를 위한 니트릴 대체품 덕분에 응급 의료에서 선택적 의료에 이르기까지 장갑의 필수성이 확고해졌습니다. 혁신의 핵심은 천자 경보 기능을 추가하면서도 의료진이 기구의 촉감을 유지할 수 있게 해주는 촉각 감지 코팅에 있습니다. 연평균 성장률(CAGR) 6.75%로 성장하는 보호복 시장은 격리 프로토콜의 확대와 재생 폴리프로필렌 섬유를 결합한 신소재 블렌드의 도입으로 혜택을 보고 있습니다. 라디치 그룹의 ‘Responsible(R)’ 원단은 폐쇄형 공급망으로의 전환을 상징합니다. 착용 시간을 기록하는 센서 실이 내장되어 있어 가운 교체 시기를 알려줌으로써 애프터마켓 소프트웨어 수익을 창출하고 있습니다.
마스크나 호흡용 보호구와 같은 2차 보호 장비 카테고리는 팬데믹의 정점을 지나면 안정화되겠지만, 착용 적합성 테스트 준수로 인해 고사양 SKU가 요구되는 상황에서는 여전히 중요합니다. 안면 및 눈 보호구는 비말 방지 지침과 관련하여 점진적인 성장이 예상되며, 풋커버는 클린룸에서 그 중요성을 유지하고 있습니다. 전반적으로, 이러한 틈새 시장은 장갑의 가격 변동 위험을 헤지하려는 공급업체에게 제품 다각화를 보장하며, 의료용 보호 장비(PPE) 시장의 경쟁 심화를 촉진하고 있습니다.
니트릴 고무는 뛰어난 내화학성과 라텍스 프리 제품에 대한 수용성 덕분에 2025년에도 매출 점유율 37.63%를 유지하며 의료용 보호 장비(PPE) 시장 규모 확대를 뒷받침하고 있습니다. 그러나 코로나19로 인한 공급 충격에 힘입어 천연 고무로의 전략적 조달 전환이 진행되면서, 라텍스 장갑의 연평균 성장률(CAGR)은 6.98%에 달했습니다. 태국에서는 고령화에 따른 의료 수요 증가에 힘입어 라텍스 제품의 수출이 꾸준히 늘어날 것으로 예측됩니다. 환자 측에 니트릴, 바깥쪽에 생분해성 층을 조합한 하이브리드 복합 소재는 비용, 쾌적성, 지속가능성의 균형을 맞추는 것을 목표로 하고 있습니다. 폴리프로필렌은 멜트블로우 마스크나 SMS 가운에서 여전히 핵심 소재이지만, 재생 소재의 비율은 해마다 소폭 증가하고 있습니다. 은 나노 입자를 직조한 면 소재는 재사용 가능한 가운의 시범 생산 단계에 접어들었으며, 특수 용도 수요에서 점유율을 확대되고 있습니다.
지역별 분석
북미는 2025년 매출의 41.65%를 차지했습니다. 이는 FDA가 ISO 13485 준수를 통해 품질 수준 향상을 요구하고, 지역 생산 강화를 위해 5억 1,000만 달러의 예산을 배정하는 등 국내 생산 복귀(리쇼어링) 노력이 촉진되었기 때문입니다. 의료용 보호 장비(PPE) 시장은 다년간의 구매 계약을 체결할 수 있는 통합 의료 시스템의 혜택을 받고 있으며, 이를 통해 첨단 멜트블로운 생산 라인에 대한 설비 투자에 따른 위험이 경감되고 있습니다. 재사용 가능한 가운에 대한 인식 제고 캠페인은 미국의 기후 변화 대응 노력과 연계되어 있으며, 병원 구매 위원회에 지속 가능한 SKU 채택을 촉진하고 있습니다.
아시아태평양에서는 각국 정부가 의료 체계를 확충하고 있으며, OEM 업체들이 니트릴 장갑 공장을 확장하고 있어 2031년까지 연평균 성장률(CAGR) 7.85%가 예상됩니다. 말레이시아의 관세 우대 조치와 인도의 PPE용 테크니컬 텍스타일 파크가 지역 공급 기반을 뒷받침하는 한편, 아세안 의료기기 지침에 따른 규제 조화가 해외 기업 시장 진입을 가속화하고 있습니다. 중산층의 의료비 지출 증가가 수술 건수를 끌어올려 잠재 수요를 확대시키고 있으며, 다국적 브랜드들이 현지 상황에 맞춘 착용 적합성 테스트를 수행하기 위해 합작 법인을 설립하도록 촉진하고 있습니다.
유럽에서는 PPE도 대상이 된 의료기기 규정(MDR)에 따라 꾸준한 진전이 나타나고 있습니다. 영국에서의 CE 마킹 적용 연장은 브렉시트 이후의 불확실성을 완화하고, 유럽 내 무역 흐름을 유지하고 있습니다. ‘그린 딜’에 구현된 지속가능성에 대한 요구로 인해 재사용 가능한 제품이 우선시되고 있으며, 병원에서는 멸균이 가능한 호흡용 보호구의 시범 도입이 진행되고 있습니다. 남미 및 중동 및 아프리카은 절대 수치상으로는 다른 지역에 뒤처져 있지만, 민간 병원이 감염 관리 기준을 강화하고 있는 지역에서는 국지적인 성장이 나타나고 있어, 의료용 보호 장비(PPE) 시장의 향후 성장 분야가 될 조짐을 보이고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the medical personal protective equipment market size is expected to grow from USD 43.53 billion in 2025 to USD 46.29 billion in 2026 and is forecast to reach USD 62.94 billion by 2031 at 6.34% CAGR over 2026-2031.
This report Segments the Industry Into by Product (Surgical Masks, N95 Respirators, Gloves, Gowns, Face Shields, Other Products), by Usability (Disposable, Reusable), by End User (Hospitals and Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories, Other End Users), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America).
Global Medical Protective Equipment Market Trends and Insights
Rising Surgical Procedure Volumes
Growing backlogs of deferred electives and aging populations are pushing annual global surgical counts upward, especially in ambulatory surgery centers where volumes are forecast to rise 12% within five years. Each intervention demands multiple glove changes, fluid-resistant gowns, and splash shields, all of which directly enlarge the medical personal protective equipment market. Ambulatory centers operate on lean inventories, so suppliers able to guarantee frequent, small-lot deliveries are favored. Complex minimally invasive procedures now require specialty respirators and precision barrier drapes, further widening product breadth. As outpatient volumes climb, procurement models are integrating automated reorder points tied to procedure schedules, tightening distributor-provider collaboration.
Heightened Infection-Prevention Mandates Post-COVID-19
Updated CDC targets now compel even low-acuity settings-such as primary care clinics and home-health visits-to maintain baseline PPE stocks, embedding durable demand into the medical personal protective equipment market. Clinical laboratories must document biosafety risk assessments for every instrument, triggering higher-grade glove and goggle requirements. Fit-testing audits reveal that one in five staff cannot achieve a safe seal with legacy respirators, prompting demand for inclusive sizing and custom-fit solutions. Hospital accreditation bodies link reimbursement to adherence with these standards, incentivizing continuous inventory replenishment. Regulators are also tightening shelf-life monitoring, pushing facilities toward demand-sensing software that minimizes expiries without risking stockouts.
Raw-Material Price Volatility (Nitrile & Polypropylene)
Nitrile butadiene rubber costs can swing double digits within a quarter, with 2025 tariff chatter adding fresh uncertainty. Only 15% of TSA's glove requirements are sourced domestically, underscoring exposure to geopolitical shocks. Glove makers are hedging via dual sourcing and derivative contracts, yet hospitals still confront quarterly catalog repricing. Polypropylene follows similar volatility, as refinery outages ripple into melt-blown fabric availability. These swings compress margins for fixed-price contracts and can delay capital upgrades when working capital is diverted to inventory buffers.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Reusable PPE to Curb Waste & Cost
- Advanced Material Science Enabling Lighter Barrier Fabrics
- Environmental Pushback on Single-Use Plastics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Gloves generated USD 13.24 billion, equivalent to 30.42% of the medical personal protective equipment market in 2025, underpinned by universal procedure use and rapid turnover. Nitrile substitutes for latex allergies lock in glove indispensability across emergent and elective care. Innovation centers on tactile-sensing coatings that allow clinicians to maintain instrument feel while adding puncture alerts. Protective clothing, buoyed by 6.75% CAGR, benefits from expanded isolation protocols and new material blends incorporating recycled polypropylene fibers. RadiciGroup's Respunsible(R) fabric exemplifies momentum toward closed-loop supply. Integrated sensor threads that log donning duration signal when gowns should be replaced, adding aftermarket software revenue.
Second-tier categories such as masks and respirators stabilize after pandemic peaks but remain critical where fit-test compliance dictates higher-spec SKUs. Face-and-eye protectors see incremental growth tied to splash guidelines, while foot covers preserve relevance in clean rooms. Collectively, these niches ensure product diversification for vendors seeking to hedge against glove price cycles, reinforcing competitive intensity within the medical personal protective equipment market.
Nitrile rubber retained 37.63% revenue share in 2025 thanks to strong chemical resistance and latex-free acceptance, supporting the medical personal protective equipment market size expansions. Yet supply shocks during COVID-19 triggered strategic sourcing pivots toward natural rubber, driving latex gloves to a 6.98% CAGR. Thailand forecasts a steady climb in latex exports as healthcare throughput rises with aging populations. Hybrid composites that blend nitrile on the patient side with biodegradable layers on the exterior seek to balance cost, comfort, and sustainability. Polypropylene remains fundamental in melt-blown masks and SMS gowns, although recyclate percentages inch higher each year. Silver-nanoparticle woven cotton enters pilot runs for reusable gowns, carving a growing slice of specialty demand.
Complete Report Scope:
- By Product Type
- Protective Clothing
- Masks & Respirators
- Gloves
- Face, Eye & Head Protection
- Foot & Shoe Covers
- Others
- By Material
- Non-woven Polypropylene
- Nitrile Rubber
- Natural Rubber/Latex
- Polyethylene & Other Plastics
- By Usability
- Disposable
- Reusable
- By End User
- Hospitals & Clinics
- Ambulatory Surgical Centers
- Diagnostic Laboratories
- Home Healthcare
- Research & Academic Institutes
- Others
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies & Drug Stores
- Direct Tenders & Group Purchasing
- Online Platforms
- By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America generated 41.65% of 2025 sales as FDA alignment with ISO 13485 demands elevated quality and spurred domestic re-shoring initiatives like the USD 510 million allocation to bolster regional production. The medical personal protective equipment market benefits from integrated health systems capable of multi-year offtake commitments that de-risk capital expenditure on advanced melt-blown lines. Education campaigns around reusable gowns tap into the U.S. climate agenda, nudging hospital purchasing committees toward sustainable SKUs.
Asia-Pacific is set for 7.85% CAGR to 2031 as governments boost healthcare capacity and OEMs expand nitrile glove factories. Malaysia's tariff incentives and India's PPE technical-textile parks anchor regional supply, while regulatory harmonization via ASEAN Medical Device Directive accelerates foreign entrant registration. Rising middle-class healthcare spend fuels surgical volumes, enlarging addressable demand and enticing multinational brands to establish joint ventures for localized fit testing.
Europe progresses steadily under the Medical Device Regulation, which now covers PPE. The CE-marking extension in the U.K. eases post-Brexit uncertainty and preserves intra-European trade flows. Sustainability imperatives, embodied in the Green Deal, prioritize reusables, pushing hospitals to trial sterilizable respirators. South America and Middle East & Africa trail in absolute value but register pockets of growth where private hospitals scale up infection-control standards, signaling future expansion corridors for the medical personal protective equipment market.
- 3M
- DuPont
- Ansell
- Cardinal Health
- Medline Industries
- Lakeland Industries, Inc.
- MSA Safety Incorporated
- Molnlycke Health Care
- Top Glove
- Supermax
- Hartalega Holdings
- Alpha Pro Tech, Ltd.
- Medtecs International Corp.
- Owens & Minor, Inc.
- Steris plc
- Dynarex
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising surgical procedure volumes
- 4.2.2 Heightened infection-prevention mandates post-COVID-19
- 4.2.3 Shift toward reusable PPE to curb waste & cost
- 4.2.4 Advanced material science enabling lighter barrier fabrics
- 4.2.5 On-site 3-D printing of customized respirators (under-radar)
- 4.2.6 AI-driven demand-sensing boosting distributor inventory turns (under-radar)
- 4.3 Market Restraints
- 4.3.1 Raw-material price volatility (nitrile & non-woven polypropylene)
- 4.3.2 Environmental pushback on single-use plastics
- 4.3.3 Counterfeit certification schemes eroding buyer trust (under-radar)
- 4.3.4 Robotics-enabled "no-touch" surgery lowering PPE intensity (under-radar)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Protective Clothing
- 5.1.2 Masks & Respirators
- 5.1.3 Gloves
- 5.1.4 Face, Eye & Head Protection
- 5.1.5 Foot & Shoe Covers
- 5.1.6 Others
- 5.2 By Material
- 5.2.1 Non-woven Polypropylene
- 5.2.2 Nitrile Rubber
- 5.2.3 Natural Rubber/Latex
- 5.2.4 Polyethylene & Other Plastics
- 5.3 By Usability
- 5.3.1 Disposable
- 5.3.2 Reusable
- 5.4 By End User
- 5.4.1 Hospitals & Clinics
- 5.4.2 Ambulatory Surgical Centers
- 5.4.3 Diagnostic Laboratories
- 5.4.4 Home Healthcare
- 5.4.5 Research & Academic Institutes
- 5.4.6 Others
- 5.5 By Distribution Channel
- 5.5.1 Hospital Pharmacies
- 5.5.2 Retail Pharmacies & Drug Stores
- 5.5.3 Direct Tenders & Group Purchasing
- 5.5.4 Online Platforms
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 U.S.
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 GCC
- 5.6.5.2 South Africa
- 5.6.5.3 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 3M Company
- 6.3.2 DuPont de Nemours, Inc.
- 6.3.3 Ansell Limited
- 6.3.4 Cardinal Health, Inc.
- 6.3.5 Medline Industries, LP
- 6.3.6 Lakeland Industries, Inc.
- 6.3.7 MSA Safety Incorporated
- 6.3.8 Molnlycke Health Care AB
- 6.3.9 Top Glove Corporation Bhd
- 6.3.10 Supermax Corporation Berhad
- 6.3.11 Hartalega Holdings Berhad
- 6.3.12 Alpha Pro Tech, Ltd.
- 6.3.13 Medtecs International Corp.
- 6.3.14 Owens & Minor, Inc.
- 6.3.15 Steris plc
- 6.3.16 Dynarex Corporation
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment