

|
시장보고서
상품코드
2124142
일회용 페이스 마스크 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Disposable Face Mask - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
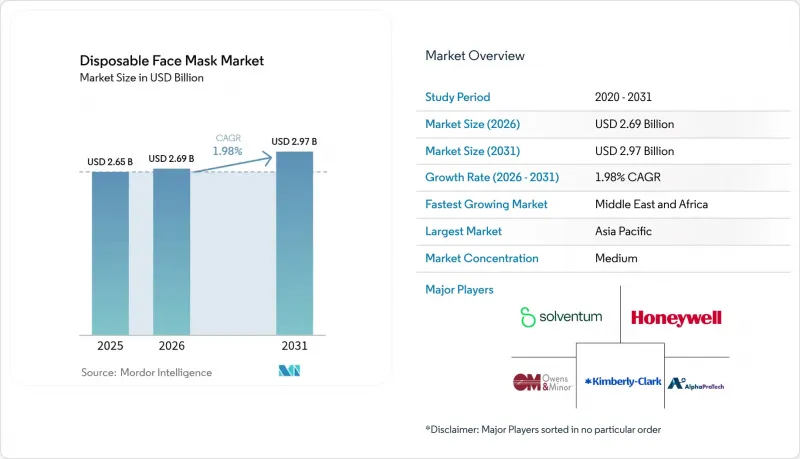
에 의하면, 일회용 페이스 마스크 시장 규모는 2025년 26억 5,000만 달러에서 2026년에는 26억 9,000만 달러로 확대되어 2031년까지 29억 7,000만 달러에 이를 것으로 예상되고 있어 2026년부터 2031년까지 CAGR 1.98%로 성장할 전망입니다.
본 보고서는 제품 유형(수술용 마스크, 호흡용 보호구, 시술용 마스크), 소재(멜트블로운 폴리프로필렌 등), 유통 채널(병원·약국 등), 사용자층(성인, 소아·어린이, 고령자),최종 사용자(의료 종사자 등), 지역(북미 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 일회용 페이스 마스크 시장 동향 및 인사이트
COVID-19 이후 국가 전략 비축에 따른 비축 동향
연방 정부 기관은 긴급 구매를 영구적인 순환 프로그램으로 전환하여, 수년에 걸친 호흡기 보호구 공급량을 확보했습니다. 2024년 현재, 미국 국가전략비축고에는 3억 5,000만 장의 N95 마스크가 비축되어 있으며, 이는 2020년 이전 수준의 26배에 해당합니다. 한편, 캐나다공급업체 관리 모델에서는 공급업체에게 유효기간이 만료되는 로트의 보충을 의무화하고 있습니다. 독일과 프랑스에서도 마찬가지로 6개월 분량공급 완충 재고가 마련되어 있으며, 특히 인증된 호흡용 보호구에 대해 기준 수요가 제도화되어 있을 뿐만 아니라, 제조업체가 NIOSH 기준을 준수하는 생산 라인을 유지하도록 동기를 부여하고 있습니다.
비급성기 의료 현장에서의 감염 예방 대책 재제도화
CMS는 2024년, 요양 시설을 위한 메디케어 상환 규정에 문서화된 마스크 정책을 포함시켜, 일시적인 마스크 사용을 규정 준수 요건으로 전환했습니다. 외래 투석 센터와 재택치료 기관은 현재 연중 내내 재고를 구매하고 있어, 수요가 여론의 영향을 받지 않게 되었습니다. ISO 45001과 같은 산업안전보건 프레임워크를 통해 의료 관련 서비스 전반에 걸쳐 호흡용 보호구 사용이 더욱 정착되고 있습니다.
멜트블로우용 폴리프로필렌 원자재 비용 급등
2025년 4분기 폴리프로필렌 가격은 톤당 평균 1,378달러를 기록했으며, 소규모 공급업체들은 원자재 가격 변동 위험을 헤지할 수 없었습니다. 고정 가격의 정부 계약은 원가 급등 시 이익률을 압박하며, 수직 통합형 기업이 아닌 업체들의 장기적인 생산 능력 투자를 저해하고 있습니다.
부문 분석
2025년에는 수술용 마스크가 일회용 페이스 마스크 시장의 61.24% 점유율을 차지했지만, 호흡용 보호구는 2031년까지 연평균 성장률(CAGR) 4.42%로 확대되고 있습니다. 인증된 N95 및 FFP2 제품은 평균 판매 가격(ASP)이 1.50-3달러로 우수한 이익률을 자랑하기 때문에 제조업체들은 생산 설비의 전환을 추진하고 있습니다. OSHA(미국 산업안전보건청)의 착용 적합성 테스트 의무화는 일회용 페이스 마스크 시장에서 인증된 제품으로의 전환 추세를 뒷받침하고 있으며, ASTM F3502 규격은 완전한 호흡용 보호구 프로토콜을 요구하지 않고,더 높은 보호 성능을 요구하는 구매자를 위해 중간 수준의 ‘작업장용 성능’ 등급을 규정하고 있습니다. 수술용 마스크는 외식 산업 등 비용을 중시하는 틈새 시장으로 후퇴하고 있습니다. 인증 제품부터 가성비를 중시하는 제품에 이르기까지 폭넓은 제품 라인업을 제공할 수 있는 제조업체야말로 변화하는 조달 패턴을 포착하는 데 있어 가장 유리한 입장에 있습니다.
2차적인 영향으로는 브랜드 파워가 있는 호흡용 보호구와 범용 수술용 마스크 간의 격차가 확대되고 있다는 점을 들 수 있습니다. 사내에 멜트블로우 생산 라인을 보유한 기업은 여과재의 품질을 관리하기 위해 수직 통합을 추진하고 있지만, 기타 기업들은 외주를 주면서도 포장이나 귀걸이의 착용감 등을 통해 차별화를 꾀하고 있습니다. 규격 갱신에 따른 교체 주기는 호흡용 보호구 제품군에 이익을 가져다주는 정기적인 수요 급증을 보장하며, 수익 구조를 인증된 SKU 쪽으로 더욱 기울게 하고 있습니다.
2025년, 일회용 페이스 마스크 시장 규모의 86.32%를 멜트블로운 폴리프로필렌이 차지했습니다. 이는 단위당 여과 효율이 높기 때문입니다. 그러나 EU의 재활용 규제로 인해 연구 개발 예산이 퇴비화 가능한 소재로 전환되고 있어, 대나무 섬유와 PLA 바이오플라스틱은 연평균 성장률(CAGR) 5.53%로 확대될 것으로 예측됩니다. 각 제조업체는 고가의 바이오플라스틱의 경제성과 불확실한 소비자의 지불 의향 사이에서 균형을 맞추면서, 지속가능성 지표를 중시하는 유럽의 입찰을 목표로 하고 있습니다. 현재로서는 정전기 유지력과 통기성 면에서 폴리프로필렌을 능가하는 소재는 없지만, 나노셀룰로오스 복합재용 파일럿 일렉트로스피닝 라인의 도입은 원자재 리스크를 신중하게 분산시키고 있음을 시사합니다.
비용 변동성도 다각화를 더욱 촉진하고 있습니다. 수직 통합형 공급업체는 정제소의 인수량을 관리함으로써 원료 가격 변동을 헤지하는 한편, 중견 기업들은 장기 수지 계약 체결이나 단위당 폴리프로필렌 사용량을 줄이는 경량 마스크 설계를 추구하고 있습니다. 이와 동시에, 소비자 대상 브랜드들은 PLA로 만든 외층과 기존의 멜트블로우 소재 코어를 결합하여 환경 의식이 높은 틈새 시장에 진출하고 있습니다. 이러한 하이브리드 접근 방식은 여과 성능 기준을 충족시키면서 동시에 환경 보호 노력을 강조하는 것입니다.
지역별 분석
아시아태평양은 2025년, 중국, 일본, 한국, 인도의 국내 소비 및 해당 지역의 수출 주도력에 힘입어 일회용 페이스 마스크 시장 점유율 39.62%를 유지했습니다. WHO의 인플루엔자 관련 권고로 인해 소비가 주기적으로 급증하는 한편, 대규모 인프라 프로젝트에 따라 산업 수요도 증가하고 있습니다. 국내 제조업체들은 멜트블로우 생산 능력을 신속하게 확대하고 있어, 지역적인 감염 확산이나 가격 변동에 즉각 대응할 수 있습니다.
북미는 2위 시장으로 자리매김했습니다. 미국과 캐나다는 계속해서 전략적 비축에 자금을 투입하고 있으며, 공급업체 관리 재고(VMI) 계약에 따라 롤링 방식의 보충 일정이 부과되고 있습니다. 멕시코는 니어쇼어링을 활용하여 아시아로부터의 조달 다각화를 모색하는 미국 바이어들에게 폴리프로필렌 마스크를 공급하고 있습니다. 그러나 캐나다에서 제정되고 있는 일회용 플라스틱에 관한 새로운 규제는 의료용 이외의 일회용 제품에 대한 감시가 강화될 것임을 예고합니다.
유럽 수요는 EN 149 FFP2 규격의 채택과 지속가능성에 관한 법규에 의해 주도되고 있습니다. 규정 2025/40에서는 소비자용 포장재에 높은 재활용 소재 함유율을 요구하고 있으며, 이는 생분해성 마스크의 연구 개발을 촉진하고 있습니다. 국가별로 분산된 조달 체계는 지역 밀착형 생산을 촉진하고 있으며, 많은 경우 전략적 자립을 목적으로 한 정부의 보조금을 통해 지원받고 있습니다.
중동 및 아프리카은 연평균 성장률(CAGR) 4.89%로 가장 빠르게 성장하고 있는 지역이며, GCC(걸프협력회의) 국가들의 병원 네트워크 확대와 ISO 및 ASTM 규격 준수를 규정하는 남아프리카공화국의 중앙 집중형 입찰의 혜택을 받고 있습니다. 사하라 이남 아프리카 국가들에서는 가격에 대한 민감성으로 인해 인증된 호흡용 보호구의 보급이 주춤하고 있지만, 팬데믹 대응을 위한 다자간 융자가 가격 면에서의 격차를 해소하는 역할을 하고 있습니다.
남미에서는 전자상거래의 보급이 현저히 진전되고 있습니다. 브라질과 아르헨티나의 온라인 소매업체들은 약국 가격보다 최대 40% 저렴한 자사 브랜드 마스크를 판매하고 있어 일회용 페이스 마스크 시장의 구도를 세분화하고 있습니다. 환율 변동과 수입 관세가 공급 계획 수립을 복잡하게 만들고 있지만, 긍정적인 인구 동향 덕분에 기준 판매량은 견조한 추세를 보이고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측(금액 : 달러)
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the disposable face mask market size is expected to increase from USD 2.65 billion in 2025 to USD 2.69 billion in 2026 and reach USD 2.97 billion by 2031, growing at a CAGR of 1.98% over 2026-2031.
This report is Segmented by Product Type (Surgical Masks, Respirators, Procedure Masks), Material (Melt-Blown Polypropylene, and More), Distribution Channel (Hospitals & Pharmacies, and More), User Demographics (Adult, Pediatric/Child, Geriatric), End-User (Healthcare Professionals, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Disposable Face Mask Market Trends and Insights
Post-COVID Stockpiling by National Strategic Reserves
Federal agencies converted emergency buys into permanent rotation programs that guarantee multi-year respirator volumes. The United States Strategic National Stockpile held 350 million N95s in 2024, 26 times pre-2020 levels, while Canada's vendor-managed model forces suppliers to backfill expiring lots. Similar six-month supply buffers in Germany and France institutionalize base-line demand, particularly for certified respirators, and motivate manufacturers to maintain NIOSH-compliant production lines.
Re-Institutionalized Infection-Prevention in Non-Acute Healthcare Settings
CMS embedded documented mask policies into Medicare reimbursement rules for nursing homes in 2024, turning episodic mask use into a compliance requirement. Outpatient dialysis centers and home-health agencies now purchase year-round stock, decoupling demand from public sentiment. Occupational health frameworks such as ISO 45001 further normalize respiratory protection across ancillary healthcare services.
Raw-Material Cost Spikes for Melt-Blown Polypropylene
Polypropylene prices averaged USD 1,378 per metric ton in Q4 2025, and smaller suppliers could not hedge feedstock exposure. Fixed-price government contracts squeeze margins during cost surges, discouraging long-term capacity investments outside vertically integrated firms.
Other drivers and restraints analyzed in the detailed report include:
- Mandated Mask Use During Severe Seasonal Flu in Asia
- Corporate "Air-Quality First" ESG Programs
- Saturation of Low-End SKUs Drives ASP Erosion
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Surgical masks captured 61.24% of Disposable face mask market share in 2025, while respirators are advancing at a 4.42% CAGR through 2031. Certified N95 and FFP2 devices command ASPs of USD 1.50-3.00, offering superior margin profiles that coax manufacturers to retool. OSHA fit-testing mandates reinforce the Disposable face mask market trend toward certified options, and ASTM F3502 provides an intermediate "Workplace Performance" tier for buyers who want better protection without full respirator protocols. Procedure masks retreat to cost-sensitive niches such as food service. Manufacturers capable of offering the entire certified-to-value continuum remain best positioned to capture shifting procurement patterns.
Second-order effects include the widening gap between brand-anchored respirators and commodity procedure masks. Companies with in-house melt-blown lines integrate vertically to control filtration media quality, while others outsource but differentiate through packaging or ear-loop comfort. Replacement cycles driven by standard updates ensure periodic demand spikes that benefit respirator portfolios, further tilting revenue mix toward certified SKUs.
Melt-blown polypropylene held 86.32% of the Disposable face mask market size in 2025, owing to high filtration efficiency per cost unit. Yet bamboo fiber and PLA bioplastics are projected to scale at a 5.53% CAGR as EU recycling mandates steer R&D budgets into compostable substrates. Producers juggle the economics of premium-priced bioplastics against uncertain willingness-to-pay, targeting European tenders that value sustainability metrics. For now, polypropylene remains unmatched in electrostatic charge retention and breathability, but pilot electro-spinning lines for nanocellulose composites point to a measured diversification of raw-material risk.
Cost volatility further motivates diversification. Vertically integrated suppliers hedge feedstock swings by controlling refinery off-takes, whereas mid-tier firms pursue long-term resin contracts or lightweight mask designs that use less polypropylene per unit. In parallel, consumer brands tap into eco-conscious niches by blending PLA outer layers with conventional melt-blown cores, a hybrid approach that meets filtration thresholds while signaling environmental progress.
Complete Report Scope:
- By Product Type
- Surgical Masks
- Respirators (N95/KN95/FFP2)
- Procedure Masks
- By Material
- Melt-blown Polypropylene
- Cotton & Cellulose
- Others (Bamboo, Silk, Bioplastics)
- By Distribution Channel
- Hospitals & Pharmacies (Offline)
- General Retail & Supermarkets
- Online & Direct-to-Consumer
- By User Demographics
- Adult
- Pediatric / Child
- Geraitric
- By End-User
- Healthcare Professionals
- Industrial/Construction Workers
- General Consumers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific retained 39.62% of Disposable face mask market share in 2025, buoyed by domestic consumption in China, Japan, South Korea, and India and by the region's export leadership. WHO flu advisories sustain periodic consumer spikes, while industrial demand climbs with large-scale infrastructure projects. Domestic manufacturers scale melt-blown capacity quickly, allowing rapid response to regional outbreaks and price changes.
North America stands as the second-largest market. The U.S. and Canada continue to fund strategic stockpiles that impose rolling replenishment schedules under vendor-managed inventory contracts. Mexico leverages nearshoring to supply polypropylene masks to U.S. buyers seeking diversification away from Asia. Yet emerging single-use-plastic rules in Canada foreshadow tighter scrutiny on non-medical disposables.
Europe's demand is driven by EN 149 FFP2 adoption and sustainability legislation. Regulation 2025/40 requires high recycled content in consumer packaging, nudging R&D toward compostable masks. Fragmented national procurement encourages localized production, often supported by government grants aimed at strategic autonomy.
Middle East and Africa, the fastest-growing cluster at 4.89% CAGR, benefits from expanded GCC hospital networks and South African centralized tenders that stipulate ISO and ASTM compliance. Price sensitivity slows certified respirator adoption in sub-Saharan economies, but multilateral financing for pandemic preparedness is bridging the affordability gap.
South America experiences strong e-commerce penetration. Brazilian and Argentine online retailers push private-label masks that undercut pharmacy prices by up to 40%, fragmenting the Disposable face mask market landscape. Currency volatility and import duties complicate supply planning, yet favorable demographics keep baseline volumes resilient.
- Alpha Pro Tech Ltd.
- Ansell
- BYD Co. Ltd. (Electronics)
- Cardinal Health
- Drager
- Honeywell International
- Kimberly-Clark Worldwide
- Lakeland Industries
- Makrite Industries
- Medicom
- Moldex-Metric
- Owens & Minor Inc.
- Prestige Ameritech
- Shanghai Dasheng
- Solventum
- UVEX Group
- Winner Medical
- Zhende Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Post-COVID Pandemic Stockpiling by National Strategic Reserves
- 4.2.2 Re-Institutionalization of Infection-Prevention Standards in Non-Acute Healthcare Settings
- 4.2.3 Mandated Use in Severe Seasonal Flu Outbreaks Across Asia
- 4.2.4 Corporate "Air-Quality First" ESG Commitments
- 4.2.5 Rapid E-Commerce Private-Label Penetration in LATAM
- 4.2.6 WHO-Led Filtration-Test Standardization (ISO 16890, ASTM F3502) Triggers Mask-Replacement Cycles
- 4.3 Market Restraints
- 4.3.1 Raw-Material Cost Spikes for Melt-Blown Polypropylene
- 4.3.2 Saturation of Low-End SKUs Driving ASP Erosion
- 4.3.3 Legislative Clampdown on Single-Use Plastics in the EU & Canada
- 4.3.4 Rise of Reusable Respirators & Biodegradable Mask Substitutes
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts ( Value in USD)
- 5.1 By Product Type
- 5.1.1 Surgical Masks
- 5.1.2 Respirators (N95/KN95/FFP2)
- 5.1.3 Procedure Masks
- 5.2 By Material
- 5.2.1 Melt-blown Polypropylene
- 5.2.2 Cotton & Cellulose
- 5.2.3 Others (Bamboo, Silk, Bioplastics)
- 5.3 By Distribution Channel
- 5.3.1 Hospitals & Pharmacies (Offline)
- 5.3.2 General Retail & Supermarkets
- 5.3.3 Online & Direct-to-Consumer
- 5.4 By User Demographics
- 5.4.1 Adult
- 5.4.2 Pediatric / Child
- 5.4.3 Geraitric
- 5.5 By End-User
- 5.5.1 Healthcare Professionals
- 5.5.2 Industrial/Construction Workers
- 5.5.3 General Consumers
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 France
- 5.6.2.3 United Kingdom
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Alpha Pro Tech Ltd.
- 6.3.2 Ansell Ltd.
- 6.3.3 BYD Co. Ltd. (Electronics)
- 6.3.4 Cardinal Health
- 6.3.5 Drager
- 6.3.6 Honeywell International Inc.
- 6.3.7 Kimberly-Clark Corporation
- 6.3.8 Lakeland Industries
- 6.3.9 Makrite Industries
- 6.3.10 Medicom
- 6.3.11 Moldex-Metric Inc.
- 6.3.12 Owens & Minor Inc.
- 6.3.13 Prestige Ameritech
- 6.3.14 Shanghai Dasheng
- 6.3.15 Solventum
- 6.3.16 UVEX Group
- 6.3.17 Winner Medical
- 6.3.18 Zhende Medical
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


