|
시장보고서
상품코드
2124143
심층 여과 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Depth Filtration - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 심층 여과 시장 규모는 2025년 30억 7,000만 달러, 2026년 33억 4,000만 달러에서 2031년까지 52억 3,000만 달러로 확대한다고 예측되고 있어 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 9.38%를 나타낼 전망입니다.
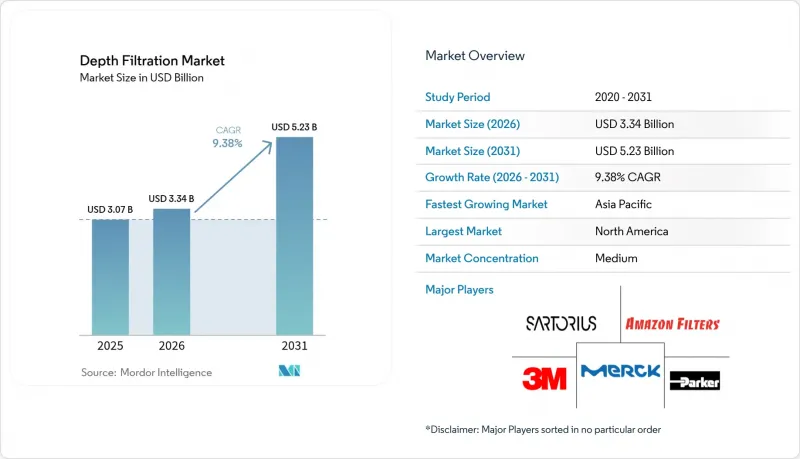
본 보고서는 여과재(셀룰로오스 섬유, 규조토, 활성탄 혼합물, 펄라이트, 기타), 제품(카트리지, 캡슐, 시트·패드,모듈·렌티큘러, 기타 제품), 용도(바이오의약품 등), 최종 사용자(제약·바이오기술 등), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 심층 여과 시장 동향 및 인사이트
바이오의약품 및 세포 및 유전자 치료제 생산량 증가
2024년 일회용 바이오리액터의 설비 증설 총량은 420만 리터에 달하며, 그중 31%는 여러 단계의 심층 여과 공정이 필요한 세포 및 유전자 치료 프로그램을 지원합니다. 2,000리터의 CAR-T 퍼퓨전 1회당 최대 80리터의 수확액이 얻어지는데, 이는 바이러스 벡터를 손상시키지 않고 정제해야 합니다. BARDA는 2024년, 일회용 심층 필터 사용을 의무화하는 백신 충전 및 마무리 공정의 확장에 5억 달러를 배정하여, 연방 정부의 자금 지원을 받는 제조 시설에서 이 워크플로우를 제도화했습니다. 현재 필터에는 활성탄 또는 하전된 규조토의 공층이 통합되어 있어, 20 nm의 바이러스 입자를 보유하면서 200 bp 미만의 DNA 단편을 포획할 수 있게 되었으며, 이를 통해 공급업체는 치료법 개발 후원사와 장기 계약을 체결하게 되었습니다.
모듈식 바이오프로세스에서의 일회용 심층 필터 도입
조립식 클린룸 포드는 기존 건설에 소요되는 36개월에 비해 18개월 만에 가동을 시작할 수 있으며, 각 CDMO 기업은 이러한 일정상의 우위를 활용하여 후기 단계의 프로젝트를 수주하고 있습니다. 론자(Lonza)의 비스프(Visp) 거점은 2024년 10월에 가동을 시작했으며, 완전 일회용 정제 라인을 도입함으로써 스테인리스제 정제 탱크에 비해 주사용수의 사용량을 40% 절감했습니다. 최신 ISPE 기준 가이드라인에서는 일회용 심층 필터가 저위험으로 분류되어 사이트 간 재검증이 면제됨에 따라, 여러 시설로의 도입이 가속화되고 있습니다. 2025년 3월 핀란드의 펄프 공장에서 발생한 화재로 인해 리드타임이 6주 연장되면서 공급망의 취약성이 부각되었습니다. 이에 따라 각 CDMO 기업들은 핵심 필터에 대해 이중 조달을 실시할 필요성을 재인식하게 되었습니다.
막 및 접선류 여과 분야의 경쟁
TFF 카세트의 가격은 2022년부터 2025년 사이에 22% 하락하여, 딥 필터와의 오랜 비용 격차가 좁혀졌습니다. 현재 하이브리드 처리 라인에서는 일회용 심층 필터 1개와 0.45μm TFF 공정을 결합하여 배치당 정제 비용을 15-20% 절감하고 있습니다. 2024년 9월에 출시된 Pall사의 ‘Depth-TFF’ 모듈은 이러한 워크플로우의 통합을 목적으로 하며, 특히 비용에 민감한 바이오시밀러 제조 시설에서 가격 경쟁을 격화시키고 있습니다.
부문 분석
2025년, 셀룰로오스 섬유는 심층 여과 시장에서 가장 큰 점유율을 차지했으며, 매출액은 14억 1,000만 달러로 전체 시장의 46.02%를 차지했습니다. 활성탄 블렌드는 향 조절과 미생물 저감을 동시에 요구하는 크래프트 맥주 양조장 수요에 힘입어 연평균 성장률(CAGR) 10.06%를 기록하며, 모든 경쟁 제품을 능가하는 성장이 예상됩니다. 규조토는 고형분 함량이 높은 와인의 침전물이나 도시수의 예비 처리에서 여전히 선호되고 있지만, EU 폐기물 기본 지침에 따른 처리 비용으로 인해 와이너리들은 폐기물이 적은 셀룰로오스 시트로 전환하고 있습니다. 합성 나노셀룰로오스는 아직 개발 단계에 있지만, 숙주 세포의 DNA를 정전기 포집하는 것이 가능하여 유전자 치료 라인에서 뉴클레아제 처리 공정을 줄일 뿐만 아니라, 프리미엄 바이오프로세스 용도에서 심층 여과 시장 점유율을 지키고 있습니다.
매체의 혁신으로 인해 심층 여과 업계는 기계적 체질과 흡착 화학을 융합한 다기능 필터로 전환되고 있습니다. 폴리페놀을 제거하는 활성탄의 능력은 소비자의 ‘클린 라벨’ 트렌드와 부합하며, 보존 안정성을 높입니다. 전하를 띤 나노셀룰로오스는 DNA 부하를 99.5% 감소시켜, 추가 공정을 거치지 않고도 엄격한 규제 요건을 충족합니다. 이러한 혼합물에 대한 인증을 획득한 공급업체는 임상시험 도중 매체 교체를 꺼리는 치료법 후원사의 존재로 인해 선구자로서의 입지를 확립할 수 있습니다.
2025년 시점에서 카트리지 필터는 심층 여과 시장의 38.27%를 차지했으나, 캡슐 형태는 2031년까지 연평균 성장률(CAGR) 11.63%를 기록할 전망입니다. 캡슐은 감마선 멸균 처리된 상태로 출하되므로 4-6시간의 증기 멸균(SIP) 사이클이 필요하지 않아, 임상시험에서 배치별 검증 작업 비용을 1,800달러 절감할 수 있습니다. RFID 지원 카트리지는 기존 하우징과 통합할 수 있어 기존의 스테인리스 스틸 라인에서는 여전히 주류를 이루고 있지만, 2024년 이후에 건설된 충전·포장 라인에서는 전환 시간을 단축하기 위해 캡슐이 표준 사양으로 채택되고 있습니다.
모듈식 및 렌티큘러 시스템은 더 콤팩트한 설치 면적에 처리 능력을 집중시키고 있으며, 클린룸 임대료가 연간 3,000달러/m²를 초과하는 경우, 이는 결정적인 요인이 됩니다. 와인 셀러에서 오랫동안 사용되어 온 시트와 패드는 작업자의 규조토 분진 노출을 줄여주는 렌티큘러 스택으로 그 자리를 점차 내주고 있습니다. 특수한 인라인 캡슐은 미국 지방 자치 단체의 상수도 시설 개보수 시 사용 지점에서의 납 제거에 기여하고 있으며, 안정적이면서도 이익률이 낮은 수익원이 되고 있습니다.
지역별 분석
북미는 2025년 매출의 34.08%를 차지하며, 이는 일회용 기기의 510(k) 승인을 신속하게 처리하는 FDA의 패스트 트랙 제도에 힘입은 것입니다. 보스턴, 샌프란시스코, RTP는 교차 오염을 줄이기 위해 일회용 정화 공정을 의무화하는 세포 치료 클러스터의 거점이며, 심층 여과를 표준 장비로 규정한 BARDA의 5억 달러 규모의 충전 및 마무리 공정 확장에 힘입어 성장하고 있습니다. 캐나다와 멕시코는 바이오시밀러 생산에 기여하고 있으며, 화이자의 샌포드 공장은 EU 및 라틴아메리카에 공급하기 위해 2024년에 일회용 제조 라인을 확장할 예정입니다.
아시아태평양은 세계 최고 수준인 연평균 성장률(CAGR) 11.07%를 나타낼 것으로 전망됩니다. 중국 국가약품감독관리국(NMPA)은 2024년에 7개의 국내 CAR-T 치료제를 승인했는데, 이들 모두는 프로그램 간 이월 위험을 피하기 위해 스테인리스제 정제 장치를 사용하지 않는 시설에서 제조되고 있습니다. 인도의 바이오시밀러 제조 공장에서는 실시간 압력 손실 기록을 의무화하는 유럽의약품청(EMA)의 데이터 무결성 규정을 충족하기 위해 심층 필터 카트리지 개조가 진행되고 있습니다. 일본에서는 검증된 일회용 심층 여과 공정을 채택할 경우 재생의료제품의 승인 기간이 12개월로 단축됨에 따라 CDMO에 대한 투자가 촉진되고 있습니다.
나머지 수요는 유럽, 중동 및 아프리카(MEA), 남미가 차지하고 있습니다. EU의 지속가능성 지침에 따라 공급업체들은 재활용 가능한 카트리지로 전환해야 하는 압박을 받고 있으며, 살토리아스(Sartorius)사는 비의약품 용도로 재사용을 목적으로 셀룰로오스를 회수하는 회수 루프의 시범 운영을 진행하고 있습니다. 브라질의 에탄올 산업 및 아르헨티나의 와인 산업에서는 규조토에 대한 수요가 견조한 추세를 보이고 있는 반면, GCC(걸프협력회의) 국가들의 해수 담수화 플랜트에서는 RO(역삼투) 멤브레인의 수명을 연장하기 위해 심층 프리필터가 도입되고 있습니다. 남미 수요는 여전히 상품 가격의 영향을 받기 쉬운 편이지만, 탁함이 없는 맑은 물이 요구되는 음료 수출 덕분에 혜택을 보고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the depth filtration market size is projected to expand from USD 3.07 billion in 2025 and USD 3.34 billion in 2026 to USD 5.23 billion by 2031, registering a CAGR of 9.38% between 2026 to 2031.
This report is Segmented by Media (Cellulose Fiber, Diatomaceous Earth, Activated Carbon Blends, Perlite & Others), Product (Cartridge, Capsule, Sheets & Pads, Modules & Lenticular, Other Products), Application (Biopharmaceutical, and More), End-User (Pharma & Biotech, and More), and Geography (North America, Europe, Asia-Pacific, MEA, South America). Market Forecasts are Provided in Terms of Value (USD).
Global Depth Filtration Market Trends and Insights
Rising Biologics & Cell-Gene Therapy Volumes
Single-use bioreactor capacity additions totaled 4.2 million L in 2024, and 31% of those vessels support cell- and gene-therapy programs that require multiple depth-filtration steps. Each 2,000 L CAR-T perfusion run yields up to 80 L of harvest, which must be clarified without damaging viral vectors. BARDA earmarked USD 500 million in 2024 for vaccine fill-finish expansions that mandate the use of disposable depth filters, institutionalizing this workflow in federally funded plants. Filters now incorporate co-layers of activated carbon or charged diatomaceous earth to capture sub-200 bp DNA fragments while preserving 20 nm virus particles, locking suppliers into long-term deals with therapy sponsors.
Single-Use Depth Filter Adoption in Modular Bioprocessing
Prefabricated cleanroom pods can be commissioned in 18 months versus 36 months for traditional builds, a schedule advantage CDMOs exploit to win late-phase projects. Lonza's Visp site came online in October 2024 with fully disposable clarification trains that cut water-for-injection use by 40% compared with stainless-steel clarifiers. The latest ISPE Baseline Guides classify single-use depth filters as low-risk, exempting them from site-to-site revalidation and accelerating multi-facility rollouts. Supply-chain fragility surfaced when a Finnish pulp mill fire in March 2025 added six-week lead times, reminding CDMOs to dual-source critical filters.
Membrane & Tangential-Flow Filtration Price Competition
TFF cassette prices slid 22% between 2022 and 2025, narrowing the historic cost gap with depth filters. Hybrid trains now pair one disposable depth filter with a 0.45 µm TFF step, trimming clarification spends 15-20% per batch. Pall's Depth-TFF module, launched in September 2024, targets this workflow consolidation and intensifies price pressure, especially in cost-sensitive biosimilar plants.
Other drivers and restraints analyzed in the detailed report include:
- Stringent Food & Beverage Clarity Standards
- Growth of Craft Breweries & Micro-Wineries
- Raw Material (Cellulose/ Diatomite) Supply Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cellulose fiber accounted for the largest share of the depth filtration market in 2025, at USD 1.41 billion, or 46.02% of revenue. Activated-carbon blends will outpace all rivals with a 10.06% CAGR, fueled by craft breweries that demand simultaneous aroma polishing and microbial reduction. Diatomaceous earth remains preferred for high-solids wine lees and municipal water pre-treatment, but disposal fees under the EU Waste Framework Directive are tilting wineries toward low-waste cellulose sheets. Synthetic nanocellulose, although nascent, unlocks electrostatic capture of host-cell DNA, trimming nuclease steps in gene-therapy lines and protecting depth filtration market share in premium bioprocess applications.
Media innovation is shifting the depth filtration industry toward multifunctional filters that marry mechanical sieving with adsorptive chemistry. Activated carbon's capacity to strip polyphenols aligns with consumer "clean label" trends and boosts shelf stability. Charged nanocellulose reduces DNA loads by 99.5%, meeting stringent regulatory requirements without adding unit operations. Suppliers that qualify these blends gain first-mover lock-in because therapy sponsors resist media switches mid-trial.
Cartridge filters accounted for 38.27% of the depth filtration market in 2025, yet capsule formats will post an 11.63% CAGR through 2031. Capsules arrive gamma-sterilized, eliminating 4-6 h steam-in-place cycles and cutting per-batch validation labor by USD 1,800 in clinical runs. RFID-enabled cartridges still dominate legacy stainless lines because they integrate with existing housings, but fill-finish suites built since 2024 default to capsules to shave changeover time.
Modules and lenticular systems are concentrating flow capacity into smaller footprints, a decisive factor when cleanroom rent exceeds USD 3,000/m2/y. Sheets and pads, long used in wine cellars, are ceding ground to lenticular stacks that reduce operator exposure to diatomaceous earth dust. Specialty in-line capsules serve point-of-use lead removal in U.S. municipal upgrades, adding a steady but low-margin revenue tail.
Complete Report Scope:
- By Media
- Cellulose Fiber
- Diatomaceous Earth
- Activated Carbon Blends
- Perlite & Others
- By Product
- Cartridge Filters
- Capsule Filters
- Filter Sheets & Pads
- Modules & Lenticular Systems
- Other Products
- By Application
- Biopharmaceutical Processing
- Food & Beverage Clarification
- Water & Waste-water Treatment
- Other Applications
- By End-user
- Pharmaceutical & Biotechnology Companies
- Contract Development & Manufacturing Organizations (CDMOs)
- Academic & Research Institutes
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 34.08% of 2025 revenue, underwritten by FDA fast-track pathways that speed single-use devices through 510(k) clearance. Boston, San Francisco, and RTP anchor cell-therapy clusters that mandate disposable clarification to mitigate cross-contamination, bolstered by BARDA's USD 500 million fill-finish expansion that codified depth filtration as standard equipment. Canada and Mexico contribute biosimilar output, with Pfizer's Sanford site expanding single-use trains in 2024 for EU and LATAM supply.
Asia-Pacific is poised for an 11.07% CAGR, the fastest worldwide. China's NMPA cleared seven domestic CAR-T therapies in 2024, each produced in facilities that reject stainless-steel clarifiers to sidestep cross-program carryover risks. India's biosimilar plants retrofit depth-filter cartridges to satisfy EMA data-integrity rules mandating real-time pressure-drop logs. Japan shortened regenerative-medicine approval timelines to 12 months for processes featuring validated single-use depth filtration, spurring CDMO investment.
Europe, MEA, and South America supply the balance. EU sustainability directives are pushing suppliers toward recyclable cartridges; Sartorius is piloting take-back loops to recover cellulose for non-pharma reuse. Brazil's ethanol and Argentina's wine sectors maintain steady diatomaceous earth demand, while GCC desalination plants add depth pre-filters to extend RO life. South American uptake remains commodity-price sensitive but benefits from beverage exports that require haze-free clarification.
- 3M
- Amazon Filters Ltd.
- Cobetter Filtration
- Critical Process Filtration
- Danaher Corp. (Pall)
- Eaton Filtration
- FILTROX
- Gemu Group
- Graver Technologies
- GS-Filt
- Hangzhou Darlly Filtration
- Meissner Filtration Products
- Merck
- Microclar
- Microdyn-Nadir
- Parker Hannifin
- Pentair
- Porvair Filtration
- Saint-Gobain Life Sciences
- Sartorius
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Biologics & Cell-Gene Therapy Volumes
- 4.2.2 Single-Use Depth Filter Adoption in Modular Bioprocessing
- 4.2.3 Stringent Food & Beverage Clarity Standards
- 4.2.4 Growth of Craft Breweries & Micro-Wineries
- 4.2.5 Emerging Demand for Exosome & Viral-Vector Purification
- 4.2.6 Micro-Algae Protein Extraction Scale-Up
- 4.3 Market Restraints
- 4.3.1 Membrane & Tangential-Flow Filtration Price Competition
- 4.3.2 Raw Material (Cellulose/Diatomite) Supply Volatility
- 4.3.3 High Disposal Cost for Single-Use Filter Waste
- 4.3.4 Regulatory Push Toward Plastic-Free Consumables
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Media
- 5.1.1 Cellulose Fiber
- 5.1.2 Diatomaceous Earth
- 5.1.3 Activated Carbon Blends
- 5.1.4 Perlite & Others
- 5.2 By Product
- 5.2.1 Cartridge Filters
- 5.2.2 Capsule Filters
- 5.2.3 Filter Sheets & Pads
- 5.2.4 Modules & Lenticular Systems
- 5.2.5 Other Products
- 5.3 By Application
- 5.3.1 Biopharmaceutical Processing
- 5.3.2 Food & Beverage Clarification
- 5.3.3 Water & Waste-water Treatment
- 5.3.4 Other Applications
- 5.4 By End-user
- 5.4.1 Pharmaceutical & Biotechnology Companies
- 5.4.2 Contract Development & Manufacturing Organizations (CDMOs)
- 5.4.3 Academic & Research Institutes
- 5.4.4 Other End Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 3M
- 6.3.2 Amazon Filters Ltd.
- 6.3.3 Cobetter Filtration
- 6.3.4 Critical Process Filtration
- 6.3.5 Danaher Corp. (Pall)
- 6.3.6 Eaton Filtration
- 6.3.7 FILTROX AG
- 6.3.8 Gemu Group
- 6.3.9 Graver Technologies
- 6.3.10 GS-Filt
- 6.3.11 Hangzhou Darlly Filtration
- 6.3.12 Meissner Filtration Products
- 6.3.13 Merck KGaA
- 6.3.14 Microclar
- 6.3.15 Microdyn-Nadir
- 6.3.16 Parker Hannifin Corp.
- 6.3.17 Pentair
- 6.3.18 Porvair Filtration
- 6.3.19 Saint-Gobain Life Sciences
- 6.3.20 Sartorius Stedim Biotech
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment