

|
시장보고서
상품코드
2124146
거래 모니터링 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Transaction Monitoring - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
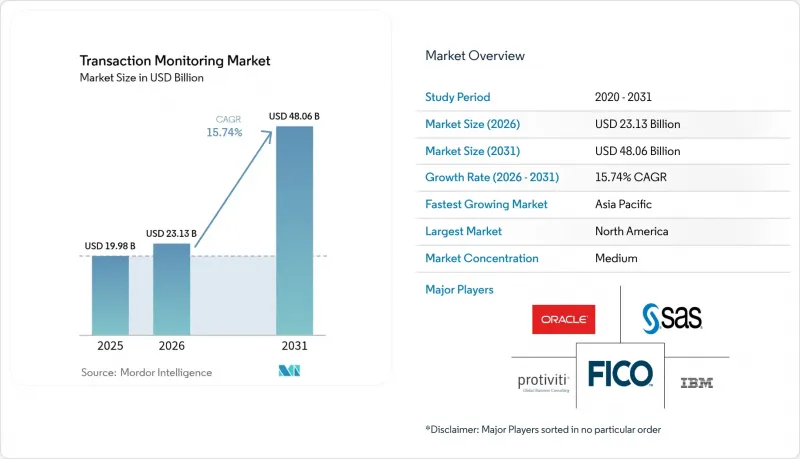
에 의하면, 거래 모니터링 시장 규모는 2025년에 199억 8,000만 달러로 평가되었고, 2026년 231억 3,000만 달러에서 2031년까지 480억 6,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 15.74%를 기록할 전망입니다.
본 보고서는 구성 요소별(솔루션 및 서비스), 도입 형태별(클라우드, 온프레미스), 용도별(자금 세탁 방지, 부정 감지·방지 등), 조직 규모별(대기업, 중소기업), 산업별(금융 및 보험·증권(BFSI), 정부·국방 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 거래 모니터링 시장 동향 및 인사이트
엄격한 AML 및 KYC 규제
2024년 전 세계 AML 관련 벌금은 전년 대비 31% 증가한 2억 6,300만 달러에 달했으며, 각 은행은 EU의 제6차 AML 지침(6AMLD) 및 미국의 기업 투명성법에 대응하기 위해, 적응형 AI 기반 엔진으로 전환하기 위해 기존의 규칙 세트를 폐지하는 움직임을 가속화하고 있습니다. 고도화된 모델을 도입한 금융기관에서는 오감지가 40% 감소했을 뿐만 아니라, 검사관들의 신뢰도가 대폭 향상되어 업무 워크플로우가 신속화되고, 컴플라이언스 업무의 적체가 해소되고 있습니다.
디지털 결제의 확대에 따라 실시간 모니터링이 필수적
실시간 결제 네트워크에서는 1초 미만의 스코어링이 요구되며, 모니터링 파이프라인을 업그레이드한 기업에서는 부정 방지 효과가 49% 향상되었습니다. 소매업 및 전자상거래 도입 기업들은 동일한 관리 기법을 활용하여 로열티 프로그램의 부정 이용이나 카드 테스트 공격을 차단함으로써, 고객 경험을 유지하면서도 부정 거래로 인한 손실을 최대 60%까지 줄이고 있습니다.
높은 오탐률로 인한 경보 피로
규칙 중심 시스템에서는 여전히 90% 이상의 노이즈 비율이 발생하고 있어, 은행은 대규모 분석가 팀을 고용할 수밖에 없으며, 경보 과부하로 인해 위협을 놓칠 위험에 노출되어 있습니다. TD 은행에 부과된 30억 달러의 벌금은 부적절한 분류가 초래하는 비용을 여실히 드러냈습니다. AI를 활용한 케이스 매니저는 오탐률을 40% 줄여, 조사 담당자가 더 가치 있는 심사에 집중할 수 있도록 지원하고 있습니다.
부문 분석
2025년에는 솔루션이 70.85%의 점유율을 차지한 것으로 평가되었으며, 외부 전문 지식에 대한 의존도가 높아지고 있는 점은 지속적인 개선을 중시하는 아웃소싱으로의 전환을 시사합니다. 전문 제공업체들은 도입 후 최적화를 중심으로 지속적인 수익을 창출하고 있으며, 규정 준수 요건이 엄격해지는 가운데 거래 모니터링 시장이 경기 사이클 전반에 걸쳐 견조한 수요를 유지할 것임을 보장하고 있습니다.
그러나 금융 기관들이 기술만으로는 효과적인 규정 준수를 유지할 수 없습니다는 사실을 인식함에 따라, 거래 모니터링 시장의 서비스 수익은 2026-2031년 연평균 성장률(CAGR) 18.12%로 증가할 것으로 예측됩니다. 현재, AI 모델 검증, 시나리오 조정, 데이터 품질 개선을 포괄하는 서비스 계약이 대부분의 플랫폼 도입과 함께 체결되고 있습니다. 특히, 국가마다 규제 당국의 기대치가 다른 상황에 직면한 국경 간 은행의 경우 이러한 경향이 두드러집니다. 이러한 자문 및 관리 서비스 계층은 정확도를 높여 위협 감지율을 최대 30%까지 향상시키고 있습니다.
클라우드 플랫폼은 2025년 거래 모니터링 시장 규모의 63.25%를 차지했으며, 탄력적인 처리량과 규칙의 자동 업데이트에 힘입어 2031년까지 연평균 성장률(CAGR) 19.28%를 나타낼 것으로 예측됩니다. 이전에는 엔터프라이즈급 인프라가 부족했던 중규모 은행 및 핀테크 기업에게도 수억 건 규모의 트랜잭션에 대한 실시간 스크리닝이 경제적으로 실현 가능해졌습니다.
데이터 보호 규제가 엄격한 관할 구역의 규제 대상 기업들은 여전히 온프레미스 핵심 시스템과 클라우드 분석을 병행하고 있지만, 프라이버시 강화형 컴퓨팅의 보급으로 인해 이러한 거부감은 점차 줄어들고 있습니다. 서비스 제공 비용이 낮아짐에 따라, 클라우드 도입을 통해 고객 심사나 제재 대상 확인과 같은 관련 분석이 가능해지면서, 거래 모니터링 시장에서 벤더들의 교차 판매 추세가 더욱 강해지고 있습니다.
지역별 분석
2025년, 북미는 거래 모니터링 시장에서 32.65%의 점유율을 차지하며 시장을 주도했습니다. 이는 FinCEN(미국 금융범죄단속국)의 집행 활동과 Tier 1 은행들의 지속적인 기술 투자가 뒷받침한 결과입니다. 오감지율 감소를 서두르는 미국의 금융기관들은 검사관의 투명성 기준을 충족하는 ‘설명 가능한 AI’의 시범 운영을 진행하고 있는 반면, 캐나다의 FinTRAC(금융거래보고분석센터)은 중견 금융기관을 대상으로 실시간 분석 도입을 추진하고 있습니다.
아시아태평양은 중국, 인도, 인도네시아가 결제 생태계를 대규모로 디지털화하고 있어 2031년까지 연평균 성장률(CAGR) 17.14%로 가장 높은 성장세를 보일 것으로 예측됩니다. 중국 중앙은행의 규제로 인해 국내 벤더들은 슈퍼앱의 결제 인프라에 지속적인 모니터링 기능을 통합해야 하는 압박을 받고 있습니다. 한편, 인도의 UPI 생태계에서는 마이크로 거래 처리량을 관리하기 위해 24시간 상시 모니터링이 요구되고 있습니다. 일본, 한국, 호주 등의 선진국 시장에서는 숙련된 분석가 부족을 보완하기 위해 AI를 활용한 이상 감지에 주력하고 있습니다.
유럽에서는 제6차 자금세탁방지지침(6AMLD)에 따라 AML(자금세탁방지) 체제가 통일되었고, MiCA(암호자산 시장 규제)에 의해 감시 대상이 암호자산 서비스 제공업체까지 확대됨에 따라 견조한 성장을 유지하고 있습니다. 독일과 프랑스는 GDPR(EU 개인정보보호규정)(일반 데이터 보호 규정)을 준수하기 위해 개인정보 보호형 분석을 중시하는 반면, 영국의 FCA(금융행위감독청)는 감시 체계의 미비에 대해 엄격한 처벌을 부과하고 있어, 이에 따라 최신 플랫폼 도입이 가속화되고 있습니다. 범유럽적인 오픈 뱅킹 이니셔티브는 데이터 입력의 폭을 넓히는 동시에 복잡성도 증가시키고 있어, 거래 모니터링 시장 전반에서 API 중심의 솔루션에 대한 수요를 높이고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the transaction monitoring market size was valued at USD 19.98 billion in 2025 and estimated to grow from USD 23.13 billion in 2026 to reach USD 48.06 billion by 2031, at a CAGR of 15.74% during the forecast period (2026-2031).
This report is Segmented by Component (Solution and Services) and by Deployment Mode (Cloud, On-Premises), by Application (Anti-Money Laundering, Fraud Detection and Prevention, and More), by Organization Size (Large Enterprises, Small and Medium Enterprises), by Industry Vertical (BFSI, Government and Defense, and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Transaction Monitoring Market Trends and Insights
Stringent AML & KYC regulations
Global AML penalties climbed 31% year on year to USD 263 million in 2024, prompting banks to retire legacy rule sets in favor of adaptive, AI-enabled engines that address the EU 6AMLD and the US Corporate Transparency Act. Institutions deploying advanced models report 40% fewer false positives and materially stronger examiner confidence, speeding case workflows and reducing compliance backlogs.
Digital payments expansion necessitates real-time monitoring
Real-time payment rails demand sub-second scoring, and firms that upgrade monitoring pipelines see a 49% lift in fraud-prevention effectiveness. Retail and e-commerce adopters leverage the same controls to stem loyalty fraud and card-testing attacks, cutting fraud losses by up to 60% while preserving customer experience.
High false-positive alert fatigue
Rule-centric systems still generate above-90% noise ratios, forcing banks to hire large analyst teams and risking missed threats amid alert overload. TD Bank's USD 3 billion penalty underscored the cost of poor triage. AI-powered case managers are cutting false positives by 40%, freeing investigators for high-value reviews.
Other drivers and restraints analyzed in the detailed report include:
- AI and machine learning transform detection accuracy
- CBDC pilots trigger new surveillance mandates
- Synthetic identity fraud evades traditional controls
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions held 70.85% share in 2025, growing reliance on external expertise signals a shift toward continuous-improvement outsourcing. Specialized providers build recurring revenue around post-implementation optimization, ensuring the transaction monitoring market maintains resilient demand through economic cycles as compliance requirements tighten.
However, Services revenue within the transaction monitoring market is expected to rise at an 18.12% CAGR from 2026-2031 as institutions recognize that technology alone cannot sustain effective compliance. Engagements covering AI-model validation, scenario tuning, and data-quality remediation now accompany most platform deployments, especially for cross-border banks contending with divergent regulator expectations. These advisory and managed-service layers boost precision, delivering up to 30% better threat capture rates.
Cloud platforms accounted for 63.25% of the transaction monitoring market size in 2025 and are projected to grow at 19.28% CAGR through 2031, propelled by elastic throughput and automatic rule updates. Real-time screening across hundreds of millions of transactions has become economically viable for midsize banks and fintechs that previously lacked enterprise-grade infrastructure.
Regulated entities in data-sensitive jurisdictions still blend on-premise cores with cloud analytics, but privacy-enhancing computation is narrowing resistance. As cost-to-serve falls, cloud adoption unlocks adjacent analytics such as customer screening and sanctions testing, reinforcing vendor cross-sell momentum in the transaction monitoring market.
Complete Report Scope:
- By Component
- Solutions
- Services
- By Deployment Mode
- Cloud
- On-Premises
- By Application
- Anti-Money Laundering (AML)
- Fraud Detection and Prevention
- Customer Identity Management
- Compliance Management
- Other Niche Use-Cases
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Industry Vertical
- Banking, Financial Services and Insurance (BFSI)
- Government and Defence
- IT and Telecom
- Retail and E-commerce
- Healthcare
- Energy and Utilities
- Manufacturing
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- APAC
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of APAC
- Middle East and Africa
- Middle East
- GCC
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America led the transaction monitoring market with a 32.65% share in 2025, supported by FinCEN enforcement activity and sustained technology spending by tier-1 banks. U.S. institutions racing to lower false positives are piloting explainable AI that meets examiner transparency criteria, while Canada's FinTRAC pushes mid-tier lenders to adopt real-time analytics.
Asia-Pacific is projected to post the highest 17.14% CAGR through 2031 as China, India, and Indonesia digitize payment ecosystems at scale. China's central-bank mandates drive domestic vendors to embed continuous monitoring into super-app payment infrastructure, whereas India's UPI ecosystem requires round-the-clock screening to manage micro-transaction volumes. Developed markets such as Japan, South Korea, and Australia focus on AI-based anomaly detection to offset skilled-analyst shortages.
Europe maintains robust growth as 6AMLD harmonizes AML regimes and MiCA extends surveillance to crypto-asset service providers. Germany and France emphasize privacy-preserving analytics to align with GDPR, while the United Kingdom's FCA levies stiff penalties for tuning lapses, accelerating modern-platform adoption. Pan-European open-banking initiatives simultaneously widen data inputs and complexity, reinforcing demand for API-centric solutions across the transaction monitoring market.
- NICE Ltd (Actimize)
- Oracle Corp.
- Fair Isaac Corp (FICO)
- SAS Institute Inc.
- IBM Corp.
- Fidelity National Information Services (FIS)
- Fiserv Inc.
- BAE Systems plc
- ACI Worldwide Inc.
- LexisNexis Risk Solutions
- Protiviti Inc.
- Feedzai Inc.
- ComplyAdvantage Ltd
- FeatureSpace Ltd
- Temenos AG
- Napier AI Ltd
- Tookitaki Holding Pte Ltd
- Fenergo Group
- ThetaRay Ltd
- Silent Eight Pte Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent AML and KYC regulations
- 4.2.2 Rising volumes of digital and real-time payments
- 4.2.3 Integration of AI and ML to cut false positives
- 4.2.4 Shift toward cloud-based compliance platforms
- 4.2.5 Open-Banking APIs enabling cross-bank monitoring
- 4.2.6 CBDC pilots triggering new surveillance mandates
- 4.3 Market Restraints
- 4.3.1 High false-positive alert fatigue
- 4.3.2 Shortage of skilled AML data analysts
- 4.3.3 Data-sovereignty and privacy-law friction
- 4.3.4 Surge in synthetic-ID fraud bypassing rules
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Information-Sharing Structures by Region
- 4.8 Technology Enablers for Secure Data Sharing
- 4.9 Porter's Five Forces
- 4.9.1 Bargaining Power of Suppliers
- 4.9.2 Bargaining Power of Buyers
- 4.9.3 Threat of New Entrants
- 4.9.4 Threat of Substitutes
- 4.9.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-Premises
- 5.3 By Application
- 5.3.1 Anti-Money Laundering (AML)
- 5.3.2 Fraud Detection and Prevention
- 5.3.3 Customer Identity Management
- 5.3.4 Compliance Management
- 5.3.5 Other Niche Use-Cases
- 5.4 By Organization Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Medium Enterprises (SMEs)
- 5.5 By Industry Vertical
- 5.5.1 Banking, Financial Services and Insurance (BFSI)
- 5.5.2 Government and Defence
- 5.5.3 IT and Telecom
- 5.5.4 Retail and E-commerce
- 5.5.5 Healthcare
- 5.5.6 Energy and Utilities
- 5.5.7 Manufacturing
- 5.5.8 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 APAC
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia and New Zealand
- 5.6.4.6 Rest of APAC
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 GCC
- 5.6.5.1.2 Turkey
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 NICE Ltd (Actimize)
- 6.4.2 Oracle Corp.
- 6.4.3 Fair Isaac Corp (FICO)
- 6.4.4 SAS Institute Inc.
- 6.4.5 IBM Corp.
- 6.4.6 Fidelity National Information Services (FIS)
- 6.4.7 Fiserv Inc.
- 6.4.8 BAE Systems plc
- 6.4.9 ACI Worldwide Inc.
- 6.4.10 LexisNexis Risk Solutions
- 6.4.11 Protiviti Inc.
- 6.4.12 Feedzai Inc.
- 6.4.13 ComplyAdvantage Ltd
- 6.4.14 FeatureSpace Ltd
- 6.4.15 Temenos AG
- 6.4.16 Napier AI Ltd
- 6.4.17 Tookitaki Holding Pte Ltd
- 6.4.18 Fenergo Group
- 6.4.19 ThetaRay Ltd
- 6.4.20 Silent Eight Pte Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


