

|
시장보고서
상품코드
2124148
직선 운동 시스템 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Linear Motion System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 직선 운동 시스템 시장 규모는 2026년에 136억 1,000만 달러로 추정되고, 2031년까지 182억 8,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 6.08%를 기록할 전망입니다.
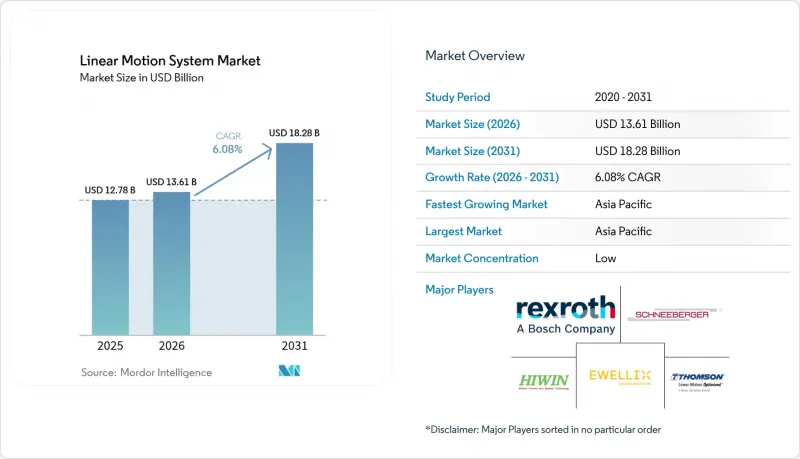
본 보고서는 유형별(단축, 다축, 벨트 구동, 볼 스크류 등), 구성 요소별(액추에이터 및 모터, 리니어 가이드, 리니어 베어링, 컨트롤러, 볼 스크류 및 리드 스크류 등), 최종 사용자 산업별(자동차 등), 용도별(자재관리, 공작기계 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 직선 운동 시스템 시장 동향 및 인사이트
인더스트리 4.0에 따른 자동화 도입 가속화
산업 분야의 경영진은 생산의 디지털화를 통해 측정 가능한 이익을 얻을 수 있다고 인식하고 있습니다. 공기압 실린더를 전기 기계식 액추에이터로 교체하는 플랜트 업그레이드를 통해 서브 마이크로미터 단위의 피드백이 가능해지며, 무선으로 업데이트할 수 있을 뿐만 아니라 시운전 시간을 최대 40% 단축할 수 있습니다. 엣지 지원 모션 컨트롤러는 현재 리눅스 기반의 앱 생태계를 탑재하고 있으며, 펌웨어 및 디지털 트윈 데이터를 생산 현장에 직접 전달합니다. 이러한 기능을 통해 제품 배치가 세분화될 때의 전환 간격이 단축되며, 실시간 센서 데이터를 바탕으로 예측 유지보수 일정을 자동으로 생성할 수 있게 됩니다. 그 결과, 직선 운동 시스템 시장은 기존의 자본 설비 예산이 아닌 인더스트리 4.0의 투자 주기와 점점 더 밀접하게 연계되고 있습니다.
전자상거래의 확대가 자동화 창고를 뒷받침
풀필먼트 사업자들은 익일 배송 약속을 지키기 위해 수직 리프트 모듈, 셔틀 시스템 및 이동 로봇을 도입하고 있습니다. 각 하위 시스템은 토트를 밀리초 단위로 정밀하게 위치시키는 고사이클 리니어 스테이지에 의존하고 있습니다. 자동 창고 타워 1기로 10,000 ft²의 고정 랙을 대체할 수 있으므로, 공간 활용 효율 향상이라는 이점은 매우 매력적입니다. 또한, 에너지 효율이 뛰어난 직접 드라이브 모터를 통해 10년 동안 총 소유 비용을 최대 20%까지 절감할 수 있습니다. 제3자 물류 서비스 제공업체들이 네트워크를 지방 도시로 확대함에 따라, 설치 면적이 작고 유지보수가 필요 없는 액추에이터가 새로운 크로스독 허브의 주요 사양으로 자리 잡고 있습니다.
희토류 자석의 가격 변동
영구 자석식 리니어 모터는 네오디뮴·철·붕소 합금에 의존하고 있지만, 정제된 원료의 90% 이상을 중국이 공급하고 있습니다. 네오디뮴 및 프라세오디뮴 산화물의 가격은 2020년부터 2025년 사이 243% 상승했으며, 중국 이외의 지역에서 진행되는 신규 프로젝트는 더 높은 자본 집약도와 더 엄격한 환경 허가 요건에 직면해 있습니다. 페라이트나 릴랙턴스 방식의 대안을 검토하고 있는 모터 제조업체들은 힘 밀도가 30% 감소하는 것을 감수할 수밖에 없으며, 이러한 대안은 저토크 용도로만 제한되어 단기적인 다각화 노력이 제약을 받고 있습니다.
부문 분석
리니어 모터의 직접 드라이브 플랫폼은 예방 정비를 통해 가동 중단 시간을 대폭 줄이고 에너지 소비를 최대 30%까지 절감할 수 있기 때문에 유형별 카테고리 중 가장 높은 연평균 성장률(CAGR) 6.78%를 나타낼 것으로 예측됩니다. 다축 어셈블리는 협동 동작이 필요한 공작기계의 갠트리 및 반도체 핸들러에 힘입어 2025년 매출의 절반 이상을 계속 차지할 것으로 보입니다. 단축 시스템은 서브미크론 수준의 정밀도보다 비용과 속도가 우선시되는 단순한 픽 앤 플레이스 작업에 적합합니다.
벨트 구동식 스테이지는 중간 수준의 하중에서 스트로크가 10m를 초과하는 경우 여전히 선호되는 솔루션이지만, 볼 스크류 액추에이터는 일반적인 산업 자동화 분야에서 추력과 가격의 균형을 잘 맞추고 있습니다. 직선 운동 시스템 시장에서는 사용자가 사이클 속도, 정밀도, 환경적 제약 조건에 맞추어 아키텍처를 선택하기 때문에 다양한 토폴로지에 대한 수요가 유지되고 있습니다. 제조업체들은 토폴로지를 선택할 때 기계적 성능뿐만 아니라 안전 인증, 총 비용, 디지털 트윈 지원 여부를 점점 더 중요하게 여기고 있습니다.
엣지 모듈이 과거에는 별도의 하드웨어가 필요했던 진동 억제, 적응형 이송 속도 제어, 상태 모니터링을 현재 처리할 수 있게 되었기 때문에 컨트롤러 시장 성장률은 연평균 성장률(CAGR) 6.96%로 다른 구성 요소를 상회할 것으로 예측됩니다. 리니어 가이드 시장 규모는 공작기계 및 포장 셀에서의 보급으로 인해 2025년 매출의 거의 절반을 차지할 것으로 전망됩니다.
리니어 베어링, 액추에이터 및 모터는 수명을 연장하고 열적 안정성을 향상시키는 브러쉬리스 영구 자석 설계로 전환되고 있습니다. 볼 스크류와 리드 스크류는 여전히 5:1에서 50:1의 기계적 이점을 제공하지만, 고정밀 분야에서는 직접 드라이브 모터에 그 자리를 내주고 있습니다. 케이블 체인, 리미트 센서, 윤활 카트리지가 시스템의 부품 목록을 구성하고 있으며, 퀵 커넥트 인터페이스를 통해 설치 시간이 단축되고 있습니다.
지역별 분석
2025년, 아시아태평양은 전 세계 출하량의 46.84%를 차지한 것으로 평가되었으며, 중국의 희토류 공급망과 일본의 부품 기술력이 그 기반이 되고 있습니다. 인도의 생산 연계형 인센티브 제도에 따른 보조금과 한국의 2,300억 달러 규모의 반도체 로드맵에 힘입어, 이 지역의 초정밀 스테이지 수주가 촉진될 전망입니다. 북미는 2025년 매출의 약 22%를 차지했으며, 전기차 조립 라인과 최근 미국의 정책 인센티브에 힘입은 의료기기의 국내 복귀의 혜택을 받고 있습니다. 멕시코로의 니어쇼어링에 따른 유입은 미국 고객에게 서비스를 제공하는 자동차 및 전자기기 공장을 위한 액추에이터 수요로 직접 이어지고 있습니다.
유럽은 2025년 도입 대수의 약 20%를 차지했으며, 독일의 ‘인더스트리 4.0’ 프로그램 덕분에 에너지 가격 급등이라는 압박에도 불구하고 공작기계 수출이 유지되고 있습니다. 프랑스의 재산업화 이니셔티브에서는 차세대 리니어 모터와 엣지 컨트롤러를 도입하여 포장 및 제약 공장의 설비 갱신이 진행되고 있습니다. 사우디아라비아와 아랍에미리트(UAE)가 주도하는 중동은 정부의 보조금을 통해 그린필드 공장의 초기 설비 투자가 충당됨에 따라, 틈새 자동화 거점으로 부상하고 있습니다.
남미는 브라질의 자동차 산업과 아르헨티나의 식품 가공 산업이 인건비 급등을 억제하기 위해 자동화를 추진함에 따라, 2031년까지 연평균 성장률(CAGR) 6.84%로 가장 빠르게 성장할 것으로 예측됩니다. 아프리카는 여전히 개발도상국 단계이지만, 남아프리카공화국의 자동차 조립 라인과 이집트의 식품 가공 라인에서는 모션 컨트롤 도입이 초기 단계에서 나타나고 있습니다. 각 지역에서 직선 운동 시스템 시장은 기술 보급에 영향을 미치는 다양한 관세, 기술력, 전력 비용과 같은 장벽에 직면해 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the linear motion system market size is projected to be USD 13.61 billion in 2026 and reach USD 18.28 billion by 2031, growing at a CAGR of 6.08% between 2026 and 2031.

This report is Segmented by Type (Single-Axis, Multi-Axis, Belt-Driven, and Ball Screw, and More), Component (Actuators and Motors, Linear Guides, Linear Bearings, Controllers, Ball Screws and Lead Screws, and More), End-User Industry (Automotive, and More), Application (Material Handling, Machine Tools, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Linear Motion System Market Trends and Insights
Accelerating Adoption of Industry 4.0 Automation
Industrial executives see measurable gains from digitalized production. Plant upgrades that replace pneumatic cylinders with electromechanical actuators provide sub-micrometer feedback, enable over-the-air updates, and cut commissioning time by up to 40%. Edge-ready motion controllers now host Linux-based app ecosystems that push firmware and digital-twin data directly to the shop floor. These capabilities shorten changeover intervals when product batches fragment and allow predictive maintenance schedules to be generated automatically from live sensor data. As a result, the linear motion system market is increasingly tied to Industry 4.0 investment cycles rather than traditional capital-equipment budgets.
Expanding E-Commerce Boosting Automated Warehousing
Fulfilment operators are deploying vertical lift modules, shuttle systems, and mobile robots to meet next-day delivery promises. Each subsystem relies on high-cycle linear stages that position totes within milliseconds. Space utilization benefits are compelling because a single automated storage tower can replace 10,000 ft2 of static racks, while energy-efficient direct-drive motors reduce total ownership cost by up to 20% over a decade. As third-party logistics providers extend networks into secondary cities, small-footprint, maintenance-free actuators become a core specification for new cross-dock hubs.
Rare-Earth Magnet Price Volatility
Permanent-magnet linear motors depend on neodymium-iron-boron alloys, yet China supplies more than 90% of refined material. Prices for neodymium-praseodymium oxide climbed 243% between 2020 and 2025, and new non-Chinese projects face higher capital intensity and stricter environmental permits. Motor makers evaluating ferrite or reluctance alternatives must accept a 30% loss of force density, limiting those options to low-torque applications and constraining near-term diversification efforts.
Other drivers and restraints analyzed in the detailed report include:
- Rising Semiconductor and Electronics Precision Needs
- Demand Surge for Miniature Maintenance-Free LMS in Diagnostic Devices
- High Upfront Cost and ROI Cycle of Customized Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Linear motor direct-drive platforms are expected to post a 6.78% CAGR, the highest among type categories, because they slash preventive-maintenance downtime and reduce energy use by up to 30%. Multi-axis assemblies still anchor more than half of 2025 revenue, driven by machine-tool gantries and semiconductor handlers that need coordinated motion. Single-axis systems satisfy simple pick-and-place duties where cost and speed outweigh sub-micron accuracy.
Belt-driven stages remain the preferred solution for strokes exceeding 10 m at moderate loads, while ball-screw actuators balance thrust and pricing for general industrial automation. The linear motion system market maintains diverse topology demand because users match architecture to cycle rate, accuracy, and environmental constraints. Manufacturers increasingly evaluate safety certification, total cost, and digital-twin readiness alongside mechanical performance when selecting a topology.
Controllers are projected to outpace other components at a 6.96% CAGR because edge modules now handle vibration suppression, adaptive feed-rate control, and condition monitoring that once required separate hardware. The linear motion system market size for linear guides was nearly half of 2025 revenue thanks to their ubiquity in machine tools and packaging cells.
Linear bearings, actuators, and motors are transitioning toward brushless permanent-magnet designs that prolong life and improve thermal stability. Ball screws and lead screws still offer 5:1 to 50:1 mechanical advantage but cede precision niches to direct-drive motors. Cable chains, limit sensors, and lubrication cartridges round out system bills of material, and quick-connect interfaces shorten installation time.
Complete Report Scope:
- By Type
- Single-Axis Linear Motion System
- Multi-Axis Linear Motion System
- Belt-Driven Linear Motion System
- Ball Screw Linear Motion System
- Linear Motor Direct-Drive System
- By Component
- Actuators and Motors
- Linear Guides
- Linear Bearings
- Controllers
- Ball Screws and Lead Screws
- Other Components
- By End-User Industry
- Automotive
- Electronics and Semiconductor
- Manufacturing, Metals and Machinery
- Aerospace and Defense
- Healthcare and Medical Devices
- Food and Beverage
- Logistics and Warehousing
- Other End-User Industries
- By Application
- Material Handling
- Machine Tools
- Robotics and Cobots
- Packaging and Labelling
- Pick-and-Place
- Inspection and Metrology
- Other Applications
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific represented 46.84% of global shipments in 2025, anchored by China's rare-earth supply chain and Japan's component expertise. Subsidies under India's production-linked incentive scheme and South Korea's USD 230 billion semiconductor roadmap will bolster regional orders for ultra-precision stages. North America contributed roughly 22% of 2025 revenue, benefitting from electric-vehicle assembly lines and medical-device reshoring supported by recent U.S. policy incentives. Mexico's nearshoring inflows are translating directly into actuator demand for automotive and electronics plants serving United States customers.
Europe accounted for about 20% of 2025 installations, with Germany's Industry 4.0 program sustaining machine-tool exports despite energy-price pressures. France's re-industrialization initiative is upgrading packaging and pharmaceutical plants with next-generation linear motors and edge controllers. The Middle East, led by Saudi Arabia and the United Arab Emirates, is emerging as a boutique automation hub as government grants offset initial capex for greenfield factories.
South America is projected to grow fastest at 6.84% CAGR through 2031 as Brazilian automotive and Argentine food processors automate to curb labour inflation. Africa remains nascent, though South African auto assembly and Egyptian food-processing lines signal early motion-control adoption. Across regions, the linear motion system market encounters varying tariff, skills, and power-cost barriers that shape technology uptake.
- Bosch Rexroth AG
- THK Co. Ltd
- Hiwin Corporation
- Schneeberger Group
- NSK Ltd
- Nippon Bearing Co. Ltd
- Thomson Industries Inc. (Regal Rexnord Corporation)
- The Timken Company
- Rockwell Automation Inc.
- Parker Hannifin Corporation
- HepcoMotion Inc.
- Ewellix AB
- Rollon S.p.A.
- SKF AB
- Schneider Electric Motion USA Inc.
- PBC Linear Inc.
- Altra Industrial Motion Corp.
- Akribis Systems Pte Ltd
- Aerotech Inc.
- Lintech Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Adoption of Industry 4.0 Automation
- 4.2.2 Expanding E-Commerce Boosting Automated Warehousing
- 4.2.3 Rising Semiconductor and Electronics Precision Needs
- 4.2.4 Demand Surge for Miniature Maintenance-Free LMS in Diagnostic Devices
- 4.2.5 Sustainable Flexible-Package Formats Requiring High-Precision Motion
- 4.2.6 Reshoring Incentives for Medical-Device Clean-Room Lines
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost and ROI Cycle of Customised Systems
- 4.3.2 Scarcity of Skilled LMS Technicians
- 4.3.3 Rare-Earth Magnet Price Volatility
- 4.3.4 IEC-62443 Cybersecurity Compliance Cost for Smart LMS
- 4.4 Industry Value-Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Technological Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Intensity of Competitive Rivalry
- 4.8.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Single-Axis Linear Motion System
- 5.1.2 Multi-Axis Linear Motion System
- 5.1.3 Belt-Driven Linear Motion System
- 5.1.4 Ball Screw Linear Motion System
- 5.1.5 Linear Motor Direct-Drive System
- 5.2 By Component
- 5.2.1 Actuators and Motors
- 5.2.2 Linear Guides
- 5.2.3 Linear Bearings
- 5.2.4 Controllers
- 5.2.5 Ball Screws and Lead Screws
- 5.2.6 Other Components
- 5.3 By End-User Industry
- 5.3.1 Automotive
- 5.3.2 Electronics and Semiconductor
- 5.3.3 Manufacturing, Metals and Machinery
- 5.3.4 Aerospace and Defense
- 5.3.5 Healthcare and Medical Devices
- 5.3.6 Food and Beverage
- 5.3.7 Logistics and Warehousing
- 5.3.8 Other End-User Industries
- 5.4 By Application
- 5.4.1 Material Handling
- 5.4.2 Machine Tools
- 5.4.3 Robotics and Cobots
- 5.4.4 Packaging and Labelling
- 5.4.5 Pick-and-Place
- 5.4.6 Inspection and Metrology
- 5.4.7 Other Applications
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 France
- 5.5.3.3 United Kingdom
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Egypt
- 5.5.6.3 Nigeria
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Bosch Rexroth AG
- 6.4.2 THK Co. Ltd
- 6.4.3 Hiwin Corporation
- 6.4.4 Schneeberger Group
- 6.4.5 NSK Ltd
- 6.4.6 Nippon Bearing Co. Ltd
- 6.4.7 Thomson Industries Inc. (Regal Rexnord Corporation)
- 6.4.8 The Timken Company
- 6.4.9 Rockwell Automation Inc.
- 6.4.10 Parker Hannifin Corporation
- 6.4.11 HepcoMotion Inc.
- 6.4.12 Ewellix AB
- 6.4.13 Rollon S.p.A.
- 6.4.14 SKF AB
- 6.4.15 Schneider Electric Motion USA Inc.
- 6.4.16 PBC Linear Inc.
- 6.4.17 Altra Industrial Motion Corp.
- 6.4.18 Akribis Systems Pte Ltd
- 6.4.19 Aerotech Inc.
- 6.4.20 Lintech Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


