

|
시장보고서
상품코드
2124160
컨텐츠 인텔리전스 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Content Intelligence - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
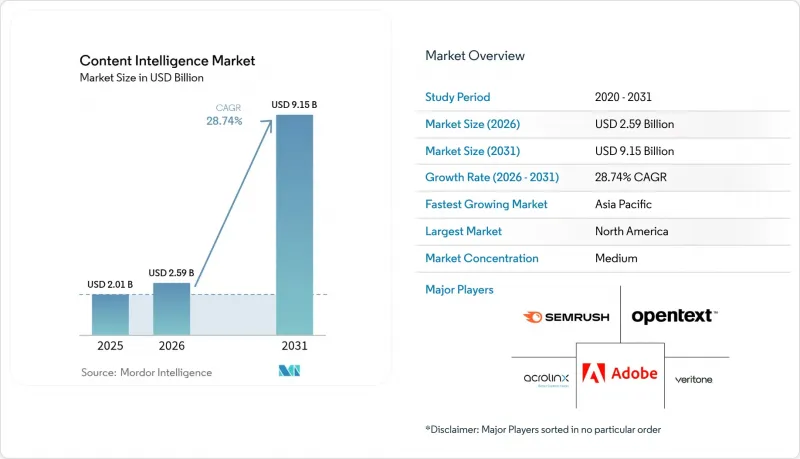
에 의하면, 컨텐츠 인텔리전스 시장 규모는 2025년 20억 1,000만 달러로 평가되었고, 2026년에는 25억 9,000만 달러로 추정되고, 2026-2031년 CAGR 28.74%로 성장을 지속할 전망이며, 2031년에는 91억 5,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 구성 요소별(솔루션, 서비스), 도입 형태별(클라우드, 온프레미스, 하이브리드), 조직 규모별(중소기업, 대기업), 최종 사용자 업종별(미디어 및 엔터테인먼트, 정부·공공 부문 등) 및 지역별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러)으로 표시되어 있습니다.
세계의 컨텐츠 인텔리전스 시장 동향 및 인사이트
대규모의 개인화된 데이터 기반 컨텐츠에 대한 수요
기업들은 현재 획일적인 메시징만으로는 소비자의 정교한 필터를 뚫기 어렵다는 사실을 인식하고 있습니다. 어도비의 ‘고객 경험 오케스트레이션(Customer Experience Orchestration)’ 플랫폼은 2024년 배너 변형에서 최대 30%의 참여도 향상을 입증했습니다. 퍼스트 파티 데이터 전략으로의 전환을 통해 기업들은 그 어느 때보다 정밀한 개인화 모델을 구축할 수 있는 독자적인 동력을 얻고 있습니다. 컨텐츠 인텔리전스 시장 플랫폼을 활용하는 조직들은 컨텐츠 제작 주기가 40-70% 단축되고 관련성 점수도 향상되었다고 보고하고 있으며, 이는 규모와 품질이 더 이상 상충 관계가 아님을 입증하고 있습니다. 금융 서비스, 헬스케어, 소매 업계에서는 AI가 규제 및 고객의 미묘한 차이에 맞추어 컨텐츠를 최적화함으로써 유사한 이점을 얻고 있습니다. 성과 측정이 중요시됨에 따라, 참여도 향상을 정량화하는 분석 모듈에 대한 투자가 가속화되고 있습니다. 이러한 동향은 컨텐츠 인텔리전스 시장의 중기적 성장 전망을 더욱 견고하게 만들고 있습니다.
마케팅 기술(MarTech) 스택 전반에 걸친 AI/ML 통합
생성형 AI는 단순한 부가 기능에서 핵심 인프라로 전환되었습니다. 어도비의 ‘GenStudio’는 제작, 브랜드 거버넌스, 분석을 하나의 워크플로우로 통합하여, AI가 제작 지연 요인이었던 수작업 이관 과정을 어떻게 제거하는지 보여주고 있습니다. OpenText의 ‘Titanium X’는 15개의 AI 에이비에이터와 100개 이상의 에이전트를 결합하여, 프로세스 집약형 고객사에게 10년 동안 10억 달러의 비용 절감을 약속하고 있습니다. 시장 통합이 진행되는 가운데, 레거시 벤더들은 업그레이드를 강요받고 있으며, 그렇지 않으면 AI 네이티브 신생 기업들에게 시장을 빼앗길 위험이 있습니다. 기업들은 현재 일회성 라이선스 구매가 아닌, 지속적인 모델 튜닝, 에이전트 오케스트레이션, 데이터 운영(Data-Ops)에 예산을 할당하고 있습니다. 통합 스택을 조기에 도입한 기업들은 실시간 A/B 테스트와 완전 자동화된 캠페인 반복 과정에서 AI 오케스트레이션의 이점을 누리고 있습니다. 이러한 통합을 통해 2030년까지 컨텐츠 인텔리전스 시장 전체에 걸쳐 지속적인 성장이 촉진될 것입니다.
데이터 개인정보 보호 및 GDPR(EU 개인정보보호규정)/DMA 규정 준수 비용
2025년 OpenAI에 부과된 1,500만 유로의 벌금은 데이터의 부적절한 사용에 따른 재정적 위험을 여실히 보여줍니다. 유럽 데이터 보호 위원회(EDPB)의 새로운 지침에 따라, 기업은 훈련, 모니터링, 추론 과정에서 모든 개인 데이터의 이용에 대해 그 정당성을 설명할 의무가 있습니다. 따라서 컨텐츠 인텔리전스 시장에 진출하는 기업은 개인정보 보호 아키텍처, 온프레미스 배포, 합성 데이터 파이프라인에 대한 투자가 필요합니다. 규정 준수 감사는 총 소유 비용(TCO)을 25-40% 가중시키며, 규제가 엄격한 분야에서는 구매 주기 지연을 초래하고 있습니다. 이러한 부담에도 불구하고, 기업들은 EU 시장 접근성을 유지하기 위해 더 높은 비용을 감수하고 있습니다.
부문 분석
솔루션이 2025년 매출의 63.10%를 차지한 반면, 서비스 부문은 2031년까지 연평균 성장률(CAGR) 33.02%로 급속한 성장을 이뤘습니다. 기업들이 도구 도입 외에도 컨설팅, 워크플로우 재설계 및 변경 관리를 필요로 하고 있기 때문에 서비스 부문의 컨텐츠 인텔리전스 시장 규모는 급격히 확대될 것으로 예측됩니다. 대규모 규제 대상 기업들은 AI의 산출물을 규정 준수 의무와 일치시킬 수 있는 전문 통합 업체에 의뢰하는 경향이 있습니다. 그 대표적인 예로 어도비(Adobe)와 PwC의 제휴를 들 수 있습니다. 이는 규제가 엄격한 업계를 대상으로 플랫폼, 데이터 거버넌스 및 도메인 전문 지식을 묶어 제공하는 것을 목표로 합니다. 솔루션 매출은 여전히 큰 규모를 유지하고 있지만, 기본적인 AI 기능의 상품화로 인해 성장 속도는 둔화되고 있습니다. 벤더들은 업계별 맞춤형 모델이나 로우코드 기반의 오케스트레이션을 도입하여 차별화를 꾀하고 있지만, 구매자들은 여전히 해당 기능을 비즈니스 가치로 전환하기 위해 서비스 파트너에 의존하고 있습니다. 바로 이러한 의존 관계가 컨텐츠 인텔리전스 시장 전체에서 서비스 분야의 지속적인 성장을 뒷받침하는 기반이 되고 있습니다.
성공적인 도입 지표는 이러한 변화를 여실히 보여주고 있습니다. 소프트웨어와 매니지드 서비스를 결합한 조직은 도구만 도입한 경우에 비해 도입률이 20-30% 더 높고, 가치 실현까지 걸리는 기간도 더 짧다고 보고되고 있습니다. Veritone의 고객 계약 중 구독형 서비스가 현재 76%를 차지하고 있어, 성과 중심의 계약 형태로의 전환을 시사하고 있습니다. 예측 기간 동안 AI가 시범 단계에서 본격적인 운영 단계로 전환됨에 따라, 성숙한 기업들은 예산을 자문 서비스, 모델 미세 조정, 지속적인 최적화 쪽으로 재분배할 것입니다.
2025년에도 클라우드는 76.20%의 점유율로 지배적인 위치를 유지했지만, 하이브리드 구성은 연평균 성장률(CAGR) 35.95%라는 가장 빠른 성장 궤도를 타고 있습니다. 기업들이 기밀 데이터를 로컬 클러스터로 분할하는 한편, 버스트 워크로드는 퍼블릭 클라우드에 유지함에 따라 하이브리드 구성의 컨텐츠 인텔리전스 시장 점유율은 상승하고 있습니다. 하이브리드 배포는 실시간 개인화에서 지연 시간을 줄이고, 탄력적인 확장성을 희생하지 않으면서도 각 관할 구역별 데이터 규제 요건을 충족합니다. 조기 도입 기업들은 대용량 멀티미디어 자산을 처리할 때, 올 클라우드 환경에 비해 30-50%의 운영 비용 절감을 실현하고 있습니다. 각 벤더들은 이에 대응하여 환경 간 이동이 용이한 컨테이너화된 마이크로 서비스를 제공함으로써, 사용자가 인프라의 복잡성에 시달리지 않고 이용할 수 있도록 하고 있습니다.
온프레미스 환경은 국방 분야나 규제가 엄격한 의료 분야의 고객에게 틈새 시장을 형성하고 있습니다. CPU 코어에서 높은 성능을 발휘하는 소형이며 특정 분야에 특화된 언어 모델의 등장으로, GPU를 많이 사용하는 데이터센터에 대한 의존도가 더욱 낮아져 로컬에서의 추론이 현실적인 선택지가 되고 있습니다. 향후에는 정책, 모델 버전 관리, 사용량 측정을 추상화하는 멀티클라우드 제어 플레인이 표준이 될 것입니다. 이러한 유연성 덕분에 하이브리드 환경은 컨텐츠 인텔리전스 시장 전체에서 주류 선택지로 자리 잡게 될 것입니다.
지역별 분석
북미는 기업용 AI의 조기 도입과 탄탄한 클라우드 인프라 덕분에 2025년 매출의 37.40%를 차지했습니다. 이 지역은 명확한 리더십을 유지하고 있지만, 대기업들이 실험 단계에서 최적화 단계로 전환함에 따라 성장은 안정화되고 있습니다. 북미의 컨텐츠 인텔리전스 시장 규모는 접근성 관련 규제의 추진과 제로파티 데이터 전략의 부상으로 인해 꾸준히 확대되고 있습니다. 벤더 생태계는 확립된 기술 허브를 중심으로 집적되어 있으며, 벤처 자금 확보와 시스템 통합사업자와의 파트너십 구축이 진행되고 있습니다.
아시아태평양은 각국의 AI 프로그램과 다국어·멀티플랫폼 컨텐츠에 대한 수요를 뒷받침하는 활기찬 크리에이터 경제에 힘입어 연평균 성장률(CAGR) 33.84%라는 가장 빠른 성장 속도를 보이고 있습니다. 현지 스타트업들은 지역 언어에 맞추어 미세 조정된 경량 모델을 출시하며, 브랜드의 대규모 현지화를 지원하고 있습니다. 또한, 데이터 거주지 규제와 비용 압박이 공존하는 지역에서는 하이브리드 클라우드 도입도 증가하고 있습니다. 이러한 요인으로 인해 북미의 우위는 서서히 약화되고 있지만, 여전히 이 두 지역이 컨텐츠 인텔리전스 시장의 대부분을 차지하고 있습니다.
유럽에서는 GDPR(EU 개인정보보호규정) 및 향후 시행될 EU AI 법에 따라 기업들이 컨텐츠 거버넌스 및 설명 가능성 도구의 도입을 피할 수 없게 됨에 따라 견조한 성장이 나타나고 있습니다. 많은 기업이 엄격한 데이터 주권 관련 요건을 준수하기 위해 하이브리드 또는 온프레미스 도입을 선택하고 있습니다. 남미 및 중동 및 아프리카은 여전히 발전 단계에 있지만 매력적인 시장입니다. 광대역 환경의 개선과 정부의 디지털화 계획으로 인해 SaaS 제공업체에게 새로운 비즈니스 기회가 창출되고 있습니다. 전 세계적인 보급 현황은 AI를 활용한 컨텐츠 인텔리전스가 얼리 어답터들의 전유물에서 주류의 필수 요소로 전환되고 있음을 뒷받침하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the content intelligence market size is expected to grow from USD 2.01 billion in 2025 to USD 2.59 billion in 2026 and is forecast to reach USD 9.15 billion by 2031 at 28.74% CAGR over 2026-2031.
This report is Segmented by Component (Solution, Service), Deployment (Cloud, On-Premise, Hybrid), Organization Size (SMEs, Large Enterprises), End-User Vertical (Media and Entertainment, Government and Public Sector, and More), and Geography. The Market Size and Forecasts are Provided in Terms of Value (USD).
Global Content Intelligence Market Trends and Insights
Demand for personalised, data-driven content at scale
Enterprises now recognize that generic messaging struggles to cut through sophisticated consumer filters. Adobe's Customer Experience Orchestration platform demonstrated engagement gains of up to 30% for banner variants in 2024. The move toward first-party data strategies gives firms proprietary fuel for ever-more-accurate personalization models. Organizations using content intelligence market platforms report 40-70% faster creation cycles and higher relevance scores, confirming that scale and quality are no longer trade-offs. Financial services, healthcare, and retail all cite similar benefits as AI tailors content to regulatory or customer nuances. The emphasis on performance measurement accelerates spending on analytics modules that quantify engagement lifts. These dynamics strengthen the content intelligence market outlook for mid-term growth.
AI/ML integration across martech stacks
Generative AI has shifted from bolt-on feature to core infrastructure. Adobe's GenStudio unifies creation, brand governance, and analytics in one workflow, showing how AI removes hand-offs that slowed production. OpenText's Titanium X combines 15 AI aviators and more than 100 agents, promising USD 1 billion in savings over a decade for process-heavy clients. Consolidation pressures legacy vendors to upgrade or risk displacement by AI-native entrants. Firms now budget for continuous model tuning, agent orchestration, and data-ops rather than one-time licenses. Early adopters of integrated stacks credit AI orchestration for real-time A/B testing and fully automated campaign iteration. This integration drives a sustained uplift across the content intelligence market through 2030.
Data-privacy and GDPR / DMA compliance costs
OpenAI's EUR 15 million fine in 2025 illustrates the financial exposure tied to data misuse. New European Data Protection Board guidance obliges firms to justify every personal-data use in training, monitoring, and inference. Enterprises adopting the content intelligence market must therefore invest in privacy-preserving architectures, on-premise deployments, and synthetic data pipelines. Compliance audits add 25-40% to total cost of ownership, slowing buying cycles in heavily regulated sectors. Despite the drag, firms accept higher costs to retain EU market access.
Other drivers and restraints analyzed in the detailed report include:
- Omnichannel content explosion on video and social platforms
- Accessibility regulations (WCAG 3.0) accelerating adoption
- Shortage of content-AI talent and change-management gaps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services captured rapid growth with a 33.02% CAGR through 2031 even though Solutions retained 63.10% of 2025 revenue. The Content intelligence market size for services is projected to climb sharply as companies need consulting, workflow redesign, and change management alongside tooling. Larger regulated enterprises turn to specialized integrators that align AI output with compliance obligations. Case in point, Adobe's collaboration with PwC targets heavily regulated verticals to bundle platform, data governance, and domain expertise. Solutions revenue remains sizable, yet commoditization of basic AI features tempers its pace. Vendors differentiate by embedding industry-specific models and low-code orchestration, yet buyers still lean on service partners to translate capability into business value. That dependence underpins sustained Services acceleration across the content intelligence market.
Implementation success metrics underscore the shift: organizations pairing software and managed services report 20-30% higher adoption rates and quicker time-to-value than tool-only deployments. Subscription-based services now account for 76% of Veritone's customer contracts, signaling a pivot toward outcome-centric engagements. Over the forecast horizon, mature enterprises will rebalance budgets toward advisory, model fine-tuning, and continuous optimization as AI moves from pilot to production.
Cloud remained dominant at a 76.20% share in 2025, but hybrid configurations now post the fastest trajectory at 35.95% CAGR. The Content intelligence market share for hybrid setups rises as firms split sensitive data onto local clusters while keeping burst workloads in public clouds. Hybrid rollouts lower latency for real-time personalization and meet jurisdictional data mandates without forgoing elastic scaling. Early adopters have measured 30-50% operating-expense savings compared with all-cloud when processing heavy multimedia assets. Vendors respond with containerized micro-services that slide easily between environments, shielding users from infrastructure complexity.
On-premise instances hold niche value for defense and highly regulated healthcare customers. The release of small, domain-tuned language models that perform well on CPU cores further reduces reliance on GPU-rich data centers, making local inference practical. Over time, multi-cloud control planes that abstract policy, model versioning, and usage metering will become standard. This flexibility cements hybrid as a mainstream choice across the content intelligence market.
Complete Report Scope:
- By Component
- Solution
- Service
- By Deployment
- Cloud
- On-premise
- Hybrid
- By Organisation Size
- Small and Medium-sized Enterprises (SMEs)
- Large Enterprises
- By End-user Vertical
- Media and Entertainment
- Government and Public Sector
- Banking, Financial Services and Insurance (BFSI)
- IT and Telecommunications
- Manufacturing
- Healthcare and Life-sciences
- Retail and e-Commerce
- Others
- By Geography
- North America
- United States
- Canada
- Europe
- Germany
- United Kingdom
- France
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- United Arab Emirates
- Rest of Middle East and Africa
- North America
Geography Analysis
North America generated 37.40% of 2025 revenue thanks to early enterprise AI rollouts and deep cloud infrastructure. The region maintains clear leadership, yet growth stabilizes as large enterprises shift from experimentation to optimization. The Content intelligence market size in North America climbs steadily, supported by regulatory pushes for accessibility and rising zero-party data strategies. Vendor ecosystems cluster around established tech hubs, securing venture funding and fostering partnerships with system integrators.
Asia-Pacific exhibits the fastest pace at 33.84% CAGR, driven by national AI programs and a flourishing creator economy that fuels demand for multilingual, multi-platform content. Local start-ups launch lightweight models fine-tuned for regional languages, helping brands localize at scale. Hybrid cloud adoption also rises where data-residency rules coexist with cost pressures. These forces gradually chip away at North American dominance, although the two regions together still command most of the content intelligence market.
Europe shows resilient expansion as GDPR and the forthcoming EU AI Act compel enterprises to adopt content governance and explainability tooling. Many firms choose hybrid or on-premise deployments to align with stringent data-sovereignty mandates. South America and the Middle East and Africa remain nascent but attractive; improved broadband and government digitization plans create green-field opportunities for SaaS providers. Global penetration confirms that AI-enabled content intelligence is trending from early adopter privilege toward mainstream necessity.
- Adobe Inc.
- OpenText Corporation
- Semrush Holdings Inc.
- Acrolinx GmbH
- Veritone Inc.
- M-Files Corporation
- Smartlogic Holdings Ltd.
- Curata Inc.
- Scoop.it SAS
- Socialbakers a.s. (now Emplifi)
- Concured Ltd.
- Atomic Reach Inc.
- OneSpot Inc.
- Vennli Inc.
- Sitecore Holding II A/S
- BrightEdge Technologies Inc.
- StoryChief NV
- Sprinklr Inc.
- Vyond Inc.
- ChapsVision Group
- Degreed Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demand for personalised, data-driven content at scale
- 4.2.2 AI/ML integration across martech stacks
- 4.2.3 Omnichannel content explosion on video and social platforms
- 4.2.4 Accessibility regulations (WCAG 3.0) accelerating adoption
- 4.2.5 Deployment of in-house small language models lowering TCO
- 4.2.6 Synthetic audience data unlocking zero-party targeting
- 4.3 Market Restraints
- 4.3.1 Data-privacy and GDPR / DMA compliance costs
- 4.3.2 Shortage of content-AI talent and change-management gaps
- 4.3.3 GPU/ASIC supply-chain bottlenecks inflating inference costs
- 4.3.4 Hallucination-driven brand-liability risks
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers/Consumers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solution
- 5.1.2 Service
- 5.2 By Deployment
- 5.2.1 Cloud
- 5.2.2 On-premise
- 5.2.3 Hybrid
- 5.3 By Organisation Size
- 5.3.1 Small and Medium-sized Enterprises (SMEs)
- 5.3.2 Large Enterprises
- 5.4 By End-user Vertical
- 5.4.1 Media and Entertainment
- 5.4.2 Government and Public Sector
- 5.4.3 Banking, Financial Services and Insurance (BFSI)
- 5.4.4 IT and Telecommunications
- 5.4.5 Manufacturing
- 5.4.6 Healthcare and Life-sciences
- 5.4.7 Retail and e-Commerce
- 5.4.8 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 India
- 5.5.3.2 China
- 5.5.3.3 Japan
- 5.5.3.4 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 United Arab Emirates
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Adobe Inc.
- 6.4.2 OpenText Corporation
- 6.4.3 Semrush Holdings Inc.
- 6.4.4 Acrolinx GmbH
- 6.4.5 Veritone Inc.
- 6.4.6 M-Files Corporation
- 6.4.7 Smartlogic Holdings Ltd.
- 6.4.8 Curata Inc.
- 6.4.9 Scoop.it SAS
- 6.4.10 Socialbakers a.s. (now Emplifi)
- 6.4.11 Concured Ltd.
- 6.4.12 Atomic Reach Inc.
- 6.4.13 OneSpot Inc.
- 6.4.14 Vennli Inc.
- 6.4.15 Sitecore Holding II A/S
- 6.4.16 BrightEdge Technologies Inc.
- 6.4.17 StoryChief NV
- 6.4.18 Sprinklr Inc.
- 6.4.19 Vyond Inc.
- 6.4.20 ChapsVision Group
- 6.4.21 Degreed Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


