|
시장보고서
상품코드
2124194
유럽의 상업용 드론 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Commercial Drones - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
2025년에는 건설 분야가 판매량 35.64%를 차지했으며, 일상적인 현장 지도제작이나 구조물 점검을 통해서 유럽의 상업용 드론 시장을 지탱했습니다.
각국의 인프라 계획에서 드론을 활용한 진행 상황 확인이 의무화됨에 따라, 이 분야는 계속해서 주도적인 위치를 유지할 것으로 예측됩니다. 현재 규모는 작지만, 신규 해상 풍력 발전 시설에 대한 육안 검사가 의무화되어 있어 에너지 분야는 연평균 성장률(CAGR) 14.07%로 성장할 전망입니다.
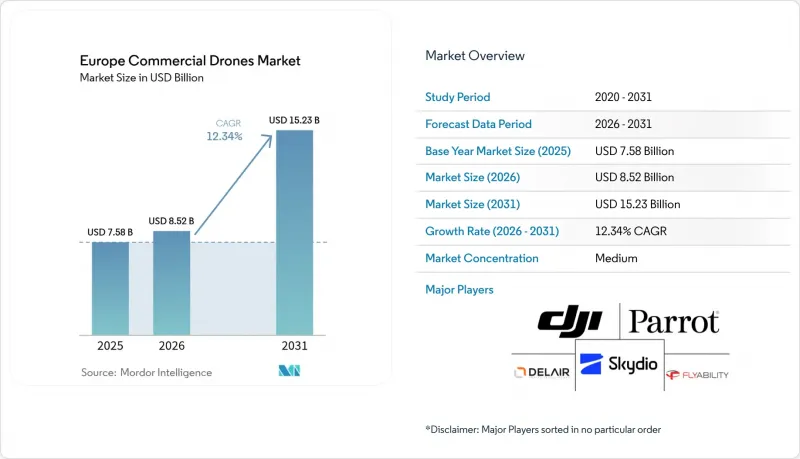
Mordor Intelligence에 따르면, 2025년 유럽 상업용 드론 시장 규모는 75억 8,000만 달러에 달할 전망입니다. 본 보고서는 용도별(건설, 농업 등), 유형별(고정익 드론 등), 중량 등급별(나노/마이크로, 소형 등), 운용 모드별(원격 조종, 옵션 조종 등), 최종 사용자별(상업용 및 소비자/애호가 등), 국가별(영국, 독일, 프랑스 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽의 상업용 드론 시장 동향 및 인사이트
EU 전역에 걸친 U-space 규제 도입이 시장 통합을 가속화
유럽의 통합된 U-space 규정은 고도 120미터 미만의 드론을 위한 단일 교통 관리 계층을 구축하여, 지금까지 국경을 넘는 임무마다 각기 다른 국가 규정을 준수해야 했던 사업자들의 부담을 해소함으로써 기존의 파편화를 해소합니다. 자동화된 비행 허가, 원격 식별(Remote ID), 공통 위험 평가를 통해 대규모 사업자의 관리 부담이 경감되고, 서비스 제공업체는 장거리 노선을 자신 있게 계획할 수 있게 됩니다. 독일, 네덜란드, 프랑스의 민간항공 당국은 이미 시범 비행 회랑을 운영 중이며, 완전 자동화된 공역 조정을 통해 하루 수백 편의 비행을 사고 없이 지원할 수 있음이 입증되었습니다. 2027년에 도입 단계가 완료되면, 국제 항공기 운항 사업자들은 유럽 대륙을 하나의 연속된 목표 시장으로 인식하게 될 것이며, U-space 인터페이스를 기반으로 설계된 하드웨어 및 소프트웨어에 대한 수요가 증가할 것입니다.
BIM과 디지털 트윈 워크플로가 건설 분야의 응용을 혁신
드론을 이용한 사진 측량과 빌딩 정보 모델링(BIM)을 결합함으로써, 건설사는 센티미터 단위의 정밀도로 현장의 간섭을 감지할 수 있게 되어, 재시공을 줄이고 작업자의 안전성을 높일 수 있습니다. Kier Group은 고해상도 정사 모자이크 이미지를 디지털 트윈 엔진에 통합함으로써 고속도로 개보수 공사에서 200만 달러의 비용 절감을 실현했습니다. 스칸디나비아 국가들의 엄격한 산업안전법 및 높은 인건비가 도입을 가속화하는 한편, 독일의 종합 건설사들은 입찰 서류에 드론 매핑을 명시하는 사례가 늘고 있습니다. 5G 통신이 보급됨에 따라 현장 상황을 실시간으로 스트리밍하여 현장 외부에 있는 엔지니어가 매일 진행 상황을 확인할 수 있게 됨에 따라, 드론은 프로젝트의 핵심 워크플로우에 더욱 깊이 통합될 것입니다.
GDPR(EU 개인정보보호규정) 준수가 운영 비용의 부담 요인으로 작용
인구 밀집 지역 상공에서의 드론 비행은 매번 개인 데이터 보호 조치의 발동을 필요로 합니다. 운영자는 데이터 보호 영향 평가를 실시하고, 기내 저장 장치를 암호화하며, 일반 공개용 공지 사이트를 개설해야 합니다. ‘프라이버시 바이 디자인(Privacy by Design)’ 기능을 통합하는 것은 제조 단계에서 비반복적인 엔지니어링 비용을 증가시킵니다. 소규모 서비스 제공업체, 특히 프랑스와 벨기에의 스타트업 기업들은 지속적인 규정 준수 감사에 드는 법적 비용으로 어려움을 겪고 있으며, 일부는 무인 지역으로의 운항 제한이나 인증된 처리 업체에 데이터 처리를 위탁할 수밖에 없는 상황에 처해 있습니다.
부문 분석
농업 분야는 보조금에 의한 인센티브에 힘입어 여전히 조기 도입 분야로 자리 잡고 있습니다. 또한, 공공 안전 기관에서는 현재 군중 관리의 표준 업무 절차에 드론을 통합하고 있습니다.
유럽의 상업용 드론 시장에서 건설 업계에 서비스를 제공하는 업체들은 데이터 분석 기능을 세트로 제공하는 경우가 많으며, 이를 통해 현장 관리자는 입방 야드 단위의 토공량이나 콘크리트 타설량을 실시간으로 추적할 수 있게 되었습니다. 에너지 분야에 주력하는 벤더들은 VTOL 기체에 AI 기반 균열 감지 알고리즘을 탑재하는 사례가 늘어나고 있으며, 작업은 수동 점검에서 결함 자동 태깅으로 전환되고 있습니다. 이러한 변화로 인해 인력을 비례적으로 늘리지 않고도 더 높은 출동률을 실현할 수 있게 되었습니다.
2025년에는 농업 및 국경 경비 분야에서 장거리 매핑이 여전히 필수적이기 때문에 고정익 플랫폼이 45.62%의 점유율을 차지했습니다. 그러나 구매자들이 활주로가 필요 없는 운용을 요구함에 따라 하이브리드/VTOL 설계는 연평균 13.82%의 성장률을 보이고 있습니다. 회전익 항공기는 교량 내부 검사 등 좁은 공간에서의 작업에서 여전히 확고한 입지를 유지하고 있지만, 적재량 제한으로 인해 활용 범위는 제한적입니다.
TEKEVER사의 ARX 시스템은 이러한 전환을 여실히 보여줍니다. 이륙 중량 600kg인 이 기체는 12시간의 비행 시간과 수직 이륙 기능을 겸비하고 있으며, 모듈식 센서 포드를 운반할 수 있습니다. 이전에는 혼합 기단을 운영하던 운영자들도 현재는 25m의 빈 공간에 착륙할 수 있음에도 불구하고, 200km에 달하는 파이프라인을 커버할 수 있는 단일 VTOL 기체를 선호하게 되었습니다. 소프트웨어를 통한 자율화로 조종사의 업무 부담이 경감되고, 엄격한 근무 시간 규정을 준수하기도 쉬워집니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09Construction generated 35.64% of revenue in 2025, anchoring the Europe commercial drones market through routine site mapping and structure inspection. The sector is expected to keep its lead as national infrastructure programs specify drone-verified progress reports. While smaller today, energy is on course for a 14.07% CAGR thanks to mandatory visual checks on new offshore wind arrays.
According to Mordor Intelligence, the Europe commercial drones market size is worth USD 7.58 billion in 2025. This report is Segmented by Application (Construction, Agriculture, and More), Type (Fixed-Wing Drones, and More), Weight Class (Nano/Micro, Small, and More), Mode of Operation (Remotely Piloted, Optionally Piloted, and More), End-User (Commercial and Consumer/Hobbyist, and More), and Country (United Kingdom, Germany, France, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Commercial Drones Market Trends and Insights
EU-wide U-space Regulatory Rollout Accelerates Market Integration
Europe's unified U-space rules create a single traffic-management layer for drones below 120 m and remove legacy fragmentation that previously forced operators to meet different national rules for every cross-border mission. Automated flight authorizations, remote-ID, and common risk assessments reduce overhead for scale operators and let service providers confidently plan long-range routes. National civil aviation agencies in Germany, the Netherlands, and France already run pilot corridors, demonstrating that fully automated airspace coordination can support hundreds of daily flights without incident. As implementation phases conclude in 2027, international fleet operators will treat the continent as a contiguous addressable market, boosting demand for hardware and software designed around the U-space interface.
BIM and Digital-Twin Workflows Transform Construction Applications
Drone photogrammetry paired with Building Information Modeling helps contractors detect site clashes at centimeter-level accuracy, cutting rework and improving worker safety. Kier Group documented USD 2 million cost avoidance on motorway upgrades by feeding high-resolution orthomosaics into its digital-twin engine. Scandinavia's strict worker-safety laws and high labor costs accelerate adoption, while German general contractors increasingly specify drone mapping in tender documents. As 5G connectivity becomes pervasive, real-time site streaming will allow off-site engineers to validate progress daily, further embedding drones into core project workflows.
GDPR Compliance Creates Operational Cost Pressures
Every drone flight over populated areas triggers personal-data safeguards. Operators must run Data Protection Impact Assessments, encrypt onboard storage, and publish public-access notice sites. Embedding privacy-by-design features adds non-recurring engineering costs at the manufacturing stage. Small service providers-especially start-ups in France and Belgium-struggle with the legal fees for ongoing compliance audits, forcing some to restrict operations to unpopulated zones or subcontract data handling to certified processors.
Other drivers and restraints analyzed in the detailed report include:
- Precision Agriculture Subsidies Catalyze Rural Technology Adoption
- Renewable Energy Infrastructure Drives Inspection Demand
- Pilot Training Infrastructure Constrains Market Expansion
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Agriculture remains an early adopter, aided by subsidy incentives, and public-safety agencies now incorporate drones into crowd-management standard operating procedures.
Europe's commercial drone market operators serving construction often bundle data analytics, letting site managers track cubic-yard earthworks or concrete pour volumes in real time. Energy-focused vendors increasingly equip VTOL airframes with AI crack-detection algorithms, moving the task from manual review to automatic defect tagging. This shift supports higher sortie rates without proportional head-count growth.
Fixed-wing platforms held a 45.62% share in 2025 because long-range mapping remains essential in agriculture and border patrol. Hybrid/VTOL designs, however, are growing 13.82% annually as buyers seek runway-free operations. Rotary-wing craft keep their foothold in confined-space tasks such as bridge-cavity inspection, yet payload limits cap their reach.
TEKEVER's ARX system illustrates the transition: the 600 kg take-off-weight craft combines 12-hour endurance with vertical launch and can ferry modular sensor pods. Operators who formerly ran mixed fleets now prefer a single VTOL that lands in a 25 m clearing yet still covers 200 km of pipelines. Software autonomy reduces pilot workloads, easing compliance with tight duty-time rules.
Complete Report Scope:
- By Application
- Construction
- Agriculture
- Energy
- Entertainment
- Law Enforcement
- Other Applications
- By Type
- Fixed-Wing Drones
- Rotary-Wing Drones
- Hybrid/VTOL Drones
- By Weight Class
- Nano/Micro (Less than 2 kg)
- Small (2 to 25 kg)
- Medium (25 to 150 kg)
- Large (Greater than 150 kg)
- By Mode of Operation
- Remotely Piloted
- Optionally Piloted
- Fully Autonomous
- By End-User
- Commercial and Consumer/Hobbyist
- Government and Civil
- By Country
- United Kingdom
- Germany
- France
- Spain
- Italy
- Netherlands
- Switzerland
- Poland
- Rest of Europe
List of Companies Covered in this Report:
- SZ DJI Technology Co., Ltd.
- Parrot Drones SAS
- Delair SAS
- Flyability SA
- AZUR DRONES SAS
- Quantum-Systems GmbH
- Schiebel Corporation
- Wingtra
- Autel Robotics Co., Ltd.
- Skydio, Inc.
- SURVEY COPTER SAS
- Aerialtronics DV B.V.
- AltiGator
- Yuneec International (ATL Drone)
- Thales Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU-wide U-space regulatory rollout (2025-27)
- 4.2.2 Surge in drone-enabled BIM and digital-twin workflows
- 4.2.3 Precision agriculture subsidies accelerating drone adoption
- 4.2.4 Renewable energy asset inspection demand
- 4.2.5 Growth of indoor swarm-inspection service contracts
- 4.2.6 EDF-backed dual-use tech spin-offs
- 4.3 Market Restraints
- 4.3.1 GDPR-driven data-privacy compliance cost
- 4.3.2 Pilot-training and licensing bottlenecks
- 4.3.3 Lithium-battery transport restrictions
- 4.3.4 Urban anti-drone counter-measure rollout
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Construction
- 5.1.2 Agriculture
- 5.1.3 Energy
- 5.1.4 Entertainment
- 5.1.5 Law Enforcement
- 5.1.6 Other Applications
- 5.2 By Type
- 5.2.1 Fixed-Wing Drones
- 5.2.2 Rotary-Wing Drones
- 5.2.3 Hybrid/VTOL Drones
- 5.3 By Weight Class
- 5.3.1 Nano/Micro (Less than 2 kg)
- 5.3.2 Small (2 to 25 kg)
- 5.3.3 Medium (25 to 150 kg)
- 5.3.4 Large (Greater than 150 kg)
- 5.4 By Mode of Operation
- 5.4.1 Remotely Piloted
- 5.4.2 Optionally Piloted
- 5.4.3 Fully Autonomous
- 5.5 By End-User
- 5.5.1 Commercial and Consumer/Hobbyist
- 5.5.2 Government and Civil
- 5.6 By Country
- 5.6.1 United Kingdom
- 5.6.2 Germany
- 5.6.3 France
- 5.6.4 Spain
- 5.6.5 Italy
- 5.6.6 Netherlands
- 5.6.7 Switzerland
- 5.6.8 Poland
- 5.6.9 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 SZ DJI Technology Co., Ltd.
- 6.4.2 Parrot Drones SAS
- 6.4.3 Delair SAS
- 6.4.4 Flyability SA
- 6.4.5 AZUR DRONES SAS
- 6.4.6 Quantum-Systems GmbH
- 6.4.7 Schiebel Corporation
- 6.4.8 Wingtra
- 6.4.9 Autel Robotics Co., Ltd.
- 6.4.10 Skydio, Inc.
- 6.4.11 SURVEY COPTER SAS
- 6.4.12 Aerialtronics DV B.V.
- 6.4.13 AltiGator
- 6.4.14 Yuneec International (ATL Drone)
- 6.4.15 Thales Group
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment