|
시장보고서
상품코드
2124210
클린룸 소모품 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cleanroom Consumables - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 클린룸 소모품 시장 규모는 2025년에 56억 1,000만 달러로 평가되었고, 2026년 60억 1,000만 달러에서 2031년까지 85억 1,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 7.18%를 기록할 전망입니다.
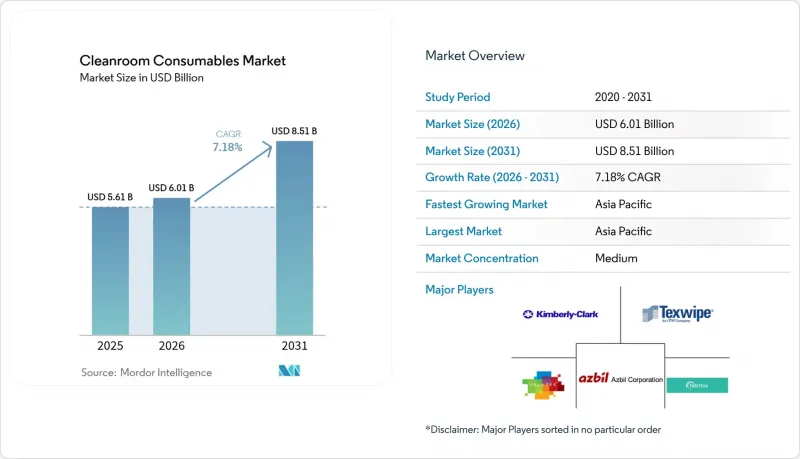
본 보고서는 제품별(안전 소모품, 세정 소모품, 클린룸 문구), 용도별(반도체·마이크로전자, 제약·바이오기술 제조 등), 지역별(북미, 유럽, 남미, 아시아태평양, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러) 단위로 제시되어 있습니다.
세계의 클린룸 소모품 시장 동향 및 인사이트
아시아의 반도체 생산 능력 확대가 초저입자 함유 소모품 수요를 견인
세계 웨이퍼 팹 생산 능력은 2024년에 6%, 2025년에 7% 증가하여 월간 3,370만 장에 달할 전망이며, 첨단 5nm 노드만으로도 2024년에는 13%의 성장이 예상됩니다. 아시아태평양의 팹에서는 ISO 클래스 1-3의 환경이 요구되고 있으며, 서브미크론 입자 제거를 목적으로 설계된 장갑, 보호복, 와이프에 대한 수요가 증가하고 있습니다. 중국의 생산 능력은 2025년까지 14% 증가할 것으로 예측되는 반면, 대만과 한국에서는 최첨단 생산 라인이 확충되고 있습니다. AI 워크로드를 위한 고대역폭 DRAM의 확장을 추진하는 메모리 제조업체의 존재가 클린룸 소모품 시장 전체에서 배리어 등급 소모품에 대한 안정적인 수요를 뒷받침하고 있습니다.
EU GMP 부록 1의 엄격한 개정에 따라 무균 등급 작업복의 채택이 확대되고 있습니다.
2023년 8월에 발효되는 59페이지 분량의 개정판에서는 오염 관리 전략, 등급 A 구역 내 생물 부하 제로화, 그리고 RABS 아이솔레이터의 보다 광범위한 사용이 의무화되었습니다. EU의 지침에 따라 전 세계 제약 시설들은 미생물 및 입자 관련 기준치를 충족하는 검증된 일회용 커버올 및 무균 와이퍼로 전환을 추진하고 있으며, 이를 통해 전환 시간 단축 및 문서화 부담 경감을 도모하고 있습니다. 1-2년의 규정 준수 대응 기간을 배경으로, 일회용 가운 및 미리 적신 와이퍼의 대량 주문이 이미 잇따르고 있어 클린룸 소모품 시장의 성장세가 더욱 강해지고 있습니다.
니트릴 및 라텍스 원자재 가격 변동이 장갑의 이익률에 영향을 미침
니트릴 부타디엔 고무(NBR)공급 부족에 따라 미국 정부는 연방 정부의 장갑 조달과 관련하여 공급 요건 면제 조치를 발령했으며, 2025년 하반기까지 국내 공급 부족이 지속될 것으로 확인되었습니다. 가격 급등(탑글로브사의 2024년 평균 판매 가격은 1,000장당 70달러에 달함)으로 인해 유통업체의 이익률이 압박을 받고 있으며, 대규모 반도체 및 제약 시설의 예산 편성이 복잡해지고 있습니다. 이러한 불확실성으로 인해 클린룸 소모품 시장의 일부에서 수주 전망이 불투명해지고 있습니다.
부문 분석
안전용 소모품은 2025년에 매출의 56.85%를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 7.21%로 성장할 전망입니다. 장갑만으로도 안전 부문의 39.35%를 차지했으며, 연평균 성장률(CAGR) 7.42%로 성장할 전망입니다. 이는 첨단 노드 및 클린룸에서의 엄격한 입자 수 제한을 반영한 것입니다. 부문별로 보면, 2025년에는 안전용 소모품이 클린룸 소모품 시장 규모의 56.85%를 차지했으나, 초급 수준의 오염 관리가 엄격해짐에 따라 접착 매트는 청소용 소모품 시장에서 입지를 확대하며 연평균 성장률(CAGR) 8.29%를 나타낼 것으로 예측됩니다.
일회용 니트릴 장갑에 대한 수요는 NBR 공급량을 계속해서 상회하고 있으며, 미국 연방 정부의 5,550만 상자 발주는 지속적인 공급 부족을 여실히 보여주고 있습니다. 커버올과 플록은 섬유로의 침투를 억제하는 부속서 1의 강화된 장벽 규정의 혜택을 받고 있습니다. 세정용 소모품은 클린룸 소모품 시장의 약 35.00%를 차지하고 있으며, 그중 미리 액체가 함침된 와이프가 42.30%의 점유율을 차지하고 있습니다. 이러한 편의성과 교차 오염 방지 대책은 검증된 잔류물 프로파일이 요구되는 세포 치료용 작업 셀에서 높이 평가되고 있습니다. 이온 제어 노트나 ESD 대응 펜과 같은 틈새 문구류는 리소그래피 스테퍼나 웨이퍼 검사 스테이션을 정전기로 인한 이상으로부터 보호합니다.
지역별 분석
아시아태평양은 2025년 매출의 41.35%를 차지했으며, 최첨단 생산 능력의 대부분을 차지하는 중국, 대만, 한국의 팹에 의해 뒷받침되고 있습니다. 중국만 해도 2025년에는 생산 능력이 14% 증가할 전망입니다. 인도의 ‘반도체 미션’에 따른 정부의 우대 조치로 인해 새로운 ISO 클래스 3 공정 홀에 대한 투자가 촉진되어 클린룸 소모품 시장 규모가 확대되고 있습니다. 일본과 인도네시아에서의 배터리 기가팩토리 확장에 따라, 정전기 방지복 및 이온 필터가 장착된 와이프에 대한 지역별 수주 전망이 더욱 확대되고 있습니다.
북미는 2위를 차지하고 있으며, ‘CHIPS 법’에 따른 자금 지원을 통해 국내 반도체 생산 능력이 강화되면서 그 입지를 공고히 하고 있습니다. 엔테그리스(Entegris)사가 콜로라도스프링스에 건설을 계획하고 있는 FOUP 공장은 오염 관리 공급망을 확보하기 위한 수직 통합 투자의 한 예입니다. 이 지역에서 성숙해 가고 있는 세포 치료 클러스터로 인해, 로트 간 오염 경로를 줄여주는 일회용 가운, 장갑 및 미리 알코올이 함침된 와이프에 대한 수요가 더욱 높아지고 있습니다. 견고한 규제 환경으로 인해 미국 FDA 및 캐나다 보건부의 감사를 원활하게 진행하는 데 도움이 되는 제3자 기관의 검증을 거친 소모품에 대한 수요가 증가하고 있습니다.
남미는 규모는 작지만, 브라질과 아르헨티나의 제약 공장이 WHO의 PIC/S 지침 및 EU의 승인 요건을 준수하려는 움직임에 따라 2031년까지 연평균 성장률(CAGR)이 8.49%로 가장 높을 것으로 예측됩니다. 바이오시밀러 충전 라인을 위한 클린룸 업그레이드에 더해, 현지에서 반도체 패키징에 대한 관심이 높아짐에 따라 일회용 커버올 및 모듈식 접착 매트의 출하량이 증가하고 있습니다. 유럽에서는 독일, 스페인, 스칸디나비아 국가들의 Annex 1 준수 및 배터리 기가팩토리 계획에 힘입어 한 자릿수 중반대의 성장률을 유지하고 있습니다. 중동 및 아프리카에서는 ISO 클래스 1 세탁 처리 능력 부족으로 인해 성장세가 점차 둔화되고 있으며, 많은 사업자가 일회용 키트 수입에 의존할 수밖에 없어 클린룸 소모품 시장에서 현지 부가가치 창출이 제한되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the cleanroom consumables market size was valued at USD 5.61 billion in 2025 and estimated to grow from USD 6.01 billion in 2026 to reach USD 8.51 billion by 2031, at a CAGR of 7.18% during the forecast period (2026-2031).
This report is Segmented by Product (Safety Consumables, Cleaning Consumables, and Cleanroom Stationery), Application (Semiconductor and Micro-Electronics, Pharmaceutical and Biotechnology Manufacturing, and More), and Geography (North America, Europe, South America, Asia-Pacific, and Middle East and Africa). Market Forecasts are Provided in Value (USD).
Global Cleanroom Consumables Market Trends and Insights
Semiconductor capacity expansion in Asia driving ultra-low-particulate consumable demand
Global wafer-fab capacity is set to rise 6% in 2024 and 7% in 2025, hitting 33.7 million wafers per month, and advanced 5 nm nodes alone are on track for 13% growth in 2024. Asia-Pacific fabs require ISO Class 1-3 environments, amplifying demand for gloves, garments, and wipes engineered for sub-micron particulate removal. Chinese capacity is forecast to climb 14% by 2025, while Taiwan and South Korea boost leading-edge lines. Memory makers scaling high-bandwidth DRAM for AI workloads reinforce a steady pull for barrier-grade consumables across the cleanroom consumables market.
Stringent EU GMP Annex 1 revisions elevating sterile-grade apparel adoption
The 59-page revision, effective August 2023, mandates contamination-control strategies, zero bioburden in Grade A areas, and wider use of RABS isolators. EU guidance prompts pharmaceutical sites worldwide to upgrade to validated disposable coveralls and aseptic wipes that meet microbial and particulate thresholds, shortening changeover times and easing documentation. Compliance timelines of one to two years have already catalyzed bulk orders for single-use gowns and pre-saturated wipers, reinforcing momentum within the cleanroom consumables market.
Volatility in nitrile and latex raw-material prices impacting glove margins
Nitrile butadiene rubber (NBR) shortages led the U.S. government to issue supply waivers for federal glove purchases, confirming domestic supply gaps lasting until late 2025. Price spikes - Top Glove's average selling price hit USD 70 per 1,000 pieces in 2024 - compress margins for distributors, complicating budgeting for high-volume semiconductor and pharma facilities. This uncertainty tempers order visibility within portions of the cleanroom consumables market.
Other drivers and restraints analyzed in the detailed report include:
- Ramp-up of cell and gene therapy suites requiring single-use wipes in North America
- Electrification of automotive industry spurring battery cleanrooms in Europe
- Energy-intensive laundering costs curtailing reusable garment adoption
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Safety consumables delivered 56.85% revenue in 2025 and will grow at 7.21% CAGR through 2031. Gloves alone represented 39.35% of the safety segment and are on track for 7.42% CAGR, reflecting strict particulate limits in advanced nodes and aseptic suites. At the segment level, safety commanded 56.85% of the cleanroom consumables market size in 2025, while adhesive mats are forecast to widen their presence within cleaning consumables, expanding at 8.29% CAGR as entry-point contamination controls harden.
Disposable nitrile glove demand continues to outstrip NBR supply, as U.S. federal orders for 55.5 million boxes highlight persistent shortages. Coveralls and frocks benefit from Annex 1's heightened barrier provisions that discourage textile permeation. Cleaning consumables account for roughly 35.00% of the cleanroom consumables market, with pre-saturated wipes holding a 42.30% share in that subset. Their convenience and cross-contamination safeguards resonate in cell-therapy work cells that require validated residue profiles. Niche stationery, such as ion-controlled journals and ESD-safe pens, safeguards lithography steppers and wafer-inspection stations from electrostatic excursions.
Complete Report Scope:
- By Product
- Safety Consumables
- Gloves
- Coveralls and Frocks
- Boot and Shoe Covers
- Bouffants and Hoods
- Face Masks and Goggles
- Other Safety Consumables
- Cleaning Consumables
- Pre-Saturated Wipes
- Dry Wipes
- Mops and Mop Buckets
- Squeegees and Wringers
- Validation Swabs
- Adhesive Mats
- Other Cleaning Consumables
- Cleanroom Stationery and Miscellaneous
- Papers and Notebooks
- Labels and Adhesive Pads
- Binders and Clipboards
- ESD-Safe Pens and Markers
- Other Stationery
- Safety Consumables
- By Application
- Semiconductor and Micro-electronics
- Pharmaceutical and Biotechnology Manufacturing
- Medical Device Production
- Food and Beverage Processing
- Aerospace and Defense Laboratories
- Automotive and Battery Manufacturing
- University and Government Research Labs
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- ASEAN
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific contributed 41.35% of 2025 turnover, sustained by Chinese, Taiwanese, and Korean fabs that together represent the bulk of leading-edge capacity. China alone is slated for 14% capacity growth in 2025. Government incentives under India's semiconductor mission funnel investment into new ISO Class 3 process halls, expanding the cleanroom consumables market footprint. Battery gigafactory roll-outs across Japan and Indonesia further thicken regional order pipelines for antistatic garments and ionic-filtered wipes.
North America ranks second, strengthening via domestic chip capacity gains funded through the CHIPS Act. Entegris' planned Colorado Springs FOUP factory illustrates vertical integration investments that secure contamination-control supply chains. The region's maturing cell-therapy cluster intensifies the flow of single-use gowns, gloves, and pre-saturated alcohol wipes that mitigate cross-batch vectors. A resilient regulatory environment inflates demand for third-party validated consumables that facilitate U.S. FDA and Health Canada inspections.
South America, though smaller, records the highest 8.49% CAGR to 2031 as Brazilian and Argentinian pharma plants align with WHO PIC/S guidance and EU authorizations. Cleanroom upgrades for biosimilar filling lines, alongside growing local semiconductor packaging interests, lift shipments of disposable coveralls and modular sticky mats. Europe sustains mid-single-digit growth, propelled by Annex 1 compliance and battery gigafactory programs in Germany, Spain, and Scandinavia. The Middle East and Africa exhibit gradual momentum hindered by scarce ISO Class 1 laundry capacity, pushing many operators toward imports of disposable kits and limiting local value capture in the cleanroom consumables market.
- DuPont de Nemours, Inc.
- Kimberly-Clark Corporation (Kimtech)
- Ansell Limited (Nitritex)
- Illinois Tool Works Inc. (Texwipe)
- Contec Inc.
- Valutek Inc.
- Berkshire Corporation
- Micronova Manufacturing Inc.
- Micronclean Ltd.
- Lakeland Industries Inc.
- Bunzl PLC (Cleanroomshop)
- Azbil Corporation
- SteriCycle Inc. (CleanMax)
- Thermo Fisher Scientific (Patheon) - Consumables Division
- Clean Air Products
- Aramark (Cleanroom Laundry)
- Helapet Ltd.
- Shield Scientific B.V.
- DuPont Personal Protection
- Foamtec International
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Semiconductor capacity Expansion in Asia Driving Ultra-Low-Particulate Consumable Demand
- 4.2.2 Stringent EU GMP Annex 1 Revisions Elevating Sterile-Grade Apparel Adoption
- 4.2.3 Ramp-Up of Cell and Gene Therapy Suites Requiring Single-Use Wipes in North America
- 4.2.4 Fast-Track COVID-19 Vaccine Facilities Accelerating Spend on Disposable Gloves in Emerging Markets
- 4.2.5 Electrification of Automotive Industry Spurring Battery Cleanrooms in Europe
- 4.2.6 Rising Outsourced Fill-Finish Services Boosting Sterile Packaging Consumables
- 4.3 Market Restraints
- 4.3.1 Volatility in Nitrile and Latex Raw Material Prices Impacting Glove Margins
- 4.3.2 Energy-Intensive Laundering Costs Curtailing Reusable Garment Adoption
- 4.3.3 Complex Multi-Jurisdictional ISO 14644 Certification Process for SMEs
- 4.3.4 Limited Availability of Class 1 Cleanroom Laundry Services in Africa and Oceania
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.5.1 Key Global Standards (ISO 14644, EU GMP Annex 1, USPLess than 797Above )
- 4.5.2 Automation and IoT in Consumable Dispensing Systems
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product
- 5.1.1 Safety Consumables
- 5.1.1.1 Gloves
- 5.1.1.2 Coveralls and Frocks
- 5.1.1.3 Boot and Shoe Covers
- 5.1.1.4 Bouffants and Hoods
- 5.1.1.5 Face Masks and Goggles
- 5.1.1.6 Other Safety Consumables
- 5.1.2 Cleaning Consumables
- 5.1.2.1 Pre-Saturated Wipes
- 5.1.2.2 Dry Wipes
- 5.1.2.3 Mops and Mop Buckets
- 5.1.2.4 Squeegees and Wringers
- 5.1.2.5 Validation Swabs
- 5.1.2.6 Adhesive Mats
- 5.1.2.7 Other Cleaning Consumables
- 5.1.3 Cleanroom Stationery and Miscellaneous
- 5.1.3.1 Papers and Notebooks
- 5.1.3.2 Labels and Adhesive Pads
- 5.1.3.3 Binders and Clipboards
- 5.1.3.4 ESD-Safe Pens and Markers
- 5.1.3.5 Other Stationery
- 5.1.1 Safety Consumables
- 5.2 By Application
- 5.2.1 Semiconductor and Micro-electronics
- 5.2.2 Pharmaceutical and Biotechnology Manufacturing
- 5.2.3 Medical Device Production
- 5.2.4 Food and Beverage Processing
- 5.2.5 Aerospace and Defense Laboratories
- 5.2.6 Automotive and Battery Manufacturing
- 5.2.7 University and Government Research Labs
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 United Kingdom
- 5.3.2.3 France
- 5.3.2.4 Italy
- 5.3.2.5 Spain
- 5.3.2.6 Russia
- 5.3.2.7 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 Japan
- 5.3.3.3 South Korea
- 5.3.3.4 India
- 5.3.3.5 ASEAN
- 5.3.3.6 Rest of Asia-Pacific
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 United Arab Emirates
- 5.3.5.3 Turkey
- 5.3.5.4 Rest of Middle East
- 5.3.6 Africa
- 5.3.6.1 South Africa
- 5.3.6.2 Rest of Africa
- 5.3.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, capacity Expansions)
- 6.3 Market Share Analysis (2024)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 DuPont de Nemours, Inc.
- 6.4.2 Kimberly-Clark Corporation (Kimtech)
- 6.4.3 Ansell Limited (Nitritex)
- 6.4.4 Illinois Tool Works Inc. (Texwipe)
- 6.4.5 Contec Inc.
- 6.4.6 Valutek Inc.
- 6.4.7 Berkshire Corporation
- 6.4.8 Micronova Manufacturing Inc.
- 6.4.9 Micronclean Ltd.
- 6.4.10 Lakeland Industries Inc.
- 6.4.11 Bunzl PLC (Cleanroomshop)
- 6.4.12 Azbil Corporation
- 6.4.13 SteriCycle Inc. (CleanMax)
- 6.4.14 Thermo Fisher Scientific (Patheon) - Consumables Division
- 6.4.15 Clean Air Products
- 6.4.16 Aramark (Cleanroom Laundry)
- 6.4.17 Helapet Ltd.
- 6.4.18 Shield Scientific B.V.
- 6.4.19 DuPont Personal Protection
- 6.4.20 Foamtec International
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment