

|
시장보고서
상품코드
2124316
클라우드 백업 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cloud Backup - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
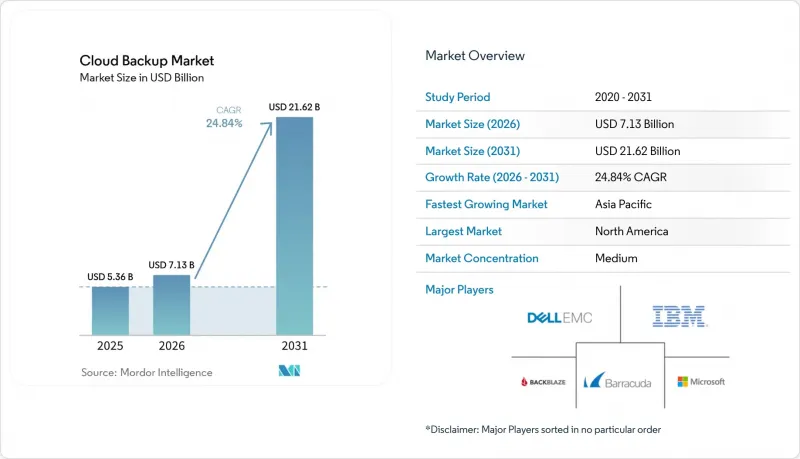
에 의하면, 클라우드 백업 시장 규모는 2025년에 53억 6,000만 달러로 평가되었고, 2026년 71억 3,000만 달러에서 2031년까지 216억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 24.84%를 기록할 전망입니다.
본 보고서는 구성 요소별(솔루션 및 서비스), 도입 모델별(퍼블릭 클라우드 등), 최종 사용자 산업별(은행 및 금융 서비스·보험, IT 및 통신 등), 서비스 제공업체별(매니지드 서비스 제공업체 등), 조직 규모별(대기업, 중소기업), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 클라우드 백업 시장 동향 및 인사이트
합리적인 가격의 확장 가능한 스토리지가 필요한 데이터 생성량의 폭발적 증가
2024년, 기업들은 120제타바이트의 데이터를 생성하여 고정 용량 어레이에 부담을 주고 있습니다. 종량제 클라우드 백업은 비용을 활성 데이터 세트에 맞추어 조정하고, 3년 주기의 하드웨어 업데이트 주기를 해소합니다. Amazon S3 Glacier Instant Retrieval과 같은 하이퍼스케일러의 콜드 오브젝트 계층은 기가바이트당 1센트 미만의 가격을 실현하여, 과도한 지출 없이 10년 이상의 보관을 가능하게 합니다. 변경된 블록만 전송하는 엣지 캐싱은 대역폭 제약을 완화하며, 백업 텔레메트리 분석은 선제적인 용량 계획을 지원합니다. 이러한 요인들이 결합되어 클라우드 백업 시장에 대한 지속적인 수요를 뒷받침하고 있습니다.
SaaS 플랫폼의 기업 도입 가속화가 통합 백업 수요를 견인
Microsoft 365는 2024년에 유료 라이선스 수가 4억 개를 돌파했으나, 마이크로소프트의 ‘책임 분담 모델’에서는 용도 계층의 보호가 대상에서 제외됩니다. 따라서 기업들은 93일간의 ‘휴지통’ 기간이 지난 후에도 Exchange, SharePoint, OneDrive 데이터를 스냅샷으로 생성할 수 있는 워크로드 지원 도구를 도입하고 있습니다. Salesforce나 Google Workspace에도 유사한 공백이 존재하며, 현재 평균적인 기업은 130종의 SaaS 도구를 사용하고 있습니다. 서로 다른 API에 걸친 세밀한 스냅샷을 조정하는 통합 정책 엔진이 필수적이며, 클라우드 백업 시장은 SaaS 거버넌스의 핵심 축으로 자리 잡고 있습니다.
엄격한 데이터 주권 및 국경을 넘는 전송에 관한 규제
중국의 ‘개인정보보호법(PIPL)’은 개인 데이터를 국내에 보관할 것을 의무화하고 있는 반면, 인도의 ‘데이터 보호 및 개인정보 보호법(DPDP)’은 정부가 제한 대상 범주를 지정할 수 있는 권한을 부여하고 있습니다. 유럽의 수출업체는 데이터 전송 전에 제3국의 감시 관련 법률을 검증해야 하므로, 이로 인해 실사 부담이 증가하고 있습니다. 이러한 규제로 인해 다국적 기업은 관할 구역별로 중복된 저장소를 구축할 수밖에 없게 되어 인프라 비용은 상승하는 반면, 클라우드 백업 시장에서의 지역별 지출은 촉진되고 있습니다.
부문 분석
2025년에는 솔루션 계약이 매출의 63.19%를 차지했으나, 서비스 부문은 연평균 성장률(CAGR) 25.99%로 더 빠른 성장이 예상됩니다. 클라우드 백업 시장에서 서비스 부문의 규모는 아키텍처 설계, 정책 스크립트 작성 및 관리형 테스트에 대한 수요 증가를 반영하고 있습니다. 멀티테넌트형 SaaS, 컨테이너 클러스터, 레거시 메인프레임을 병행하여 사용하는 기업들은 통합 작업을 전문 업체에 위탁하고 있으며, 이로 인해 계약 금액이 증가하고 있습니다. 각 벤더사는 AI를 접목해 데이터를 분류하고 저장 계층을 자동으로 할당함으로써, 규정 준수 체계를 강화하는 동시에 스토리지 운영 비용을 절감하고 있습니다.
서비스의 성장은 스토리지, 소프트웨어, 지원을 묶은 종량제 구독 모델에 힘입고 있습니다. Metallic은 보호 대상 워크로드별로 요금을 부과하며, 이를 통해 재무 부서의 조달 프로세스가 간소화됩니다. 백업 무결성에 대한 독립적인 검증은 규제상 필수 요건이 되어, 제3자 감사 서비스에 대한 수요를 끌어올리고 있습니다. ISO 27001 또는 SOC 2 인증을 획득한 관리형 서비스 제공업체(MSP)는 고부가가치 계약을 수주하며 클라우드 백업 시장의 장기적인 성장을 뒷받침하고 있습니다.
2025년 수요에서는 퍼블릭 클라우드가 48.41%를 차지하며 선두를 달렸지만, 기업들이 국내 규제 요건과 하이퍼스케일러의 경제성을 모두 충족해 나감에 따라 하이브리드 클라우드는 연평균 성장률(CAGR) 25.59%로 확대될 것으로 예측됩니다. 규제 당국이 데이터 현지화를 의무화하고, 한편 이사회가 오프사이트 중복성을 요구할 경우, 하이브리드 설계의 클라우드 백업 시장 점유율은 상승할 것입니다. 하이브리드 토폴로지는 계층형 복구도 지원합니다. 미션 크리티컬 워크로드는 온프레미스 사본에서 몇 분 이내에 복구될 수 있는 반면, 아카이브 데이터는 클라우드 리포지토리에서 몇 시간이 걸려 복구됩니다.
엣지 컴퓨팅은 하이브리드의 중요성을 더욱 높이고 있습니다. 매장, 공장, 통신 타워 등은 이용 피크 시간대 이외의 시간대에 로컬 스냅샷을 중앙 클라우드로 복제함으로써 대역폭 여유를 확보하고 있습니다. 2024년에 시행될 EU 데이터법은 서비스 제공업체에 데이터 이관성(portability)을 의무화하고 있으며, 이를 통해 마이그레이션 위험이 완화되고 하이브리드 도입이 더욱 촉진될 것입니다. 전반적으로 유연한 도입 옵션은 클라우드 백업 시장에서 여전히 주요 구매 기준으로 자리 잡고 있습니다.
지역별 분석
북미는 조기 클라우드 도입과 성숙한 비즈니스 연속성 계획 덕분에 2025년 매출의 35.06%를 차지했습니다. HIPAA, 서번스-옥슬리법 및 각 주의 데이터 유출 관련 법에 따라 규정 준수가 시급한 과제가 된 반면, 하이퍼스케일러의 밀집된 구축으로 지연 시간이 단축되어 리전 내 복구가 가능해졌습니다. 아시아태평양은 2031년까지 연평균 성장률(CAGR) 26.89%로 확대될 것으로 예측되며, 이는 세계에서 가장 빠른 속도입니다. 중국의 ‘개인정보보호법(PIPL)’과 인도의 ‘데이터 보호 및 개인정보 보호법(DPDP)’은 국내 데이터 저장을 의무화하고 있어 아키텍처의 세분화를 초래하는 한편, 지역 밀착형 지출을 촉진하여 양국의 클라우드 백업 시장을 견인하고 있습니다.
유럽의 동향은 GDPR(EU 개인정보보호규정)에 더해, 세밀한 데이터 수출 관리를 의무화하는 표준 계약 조항이 특징입니다. EU 내 가용성 영역에서 데이터를 호스팅하는 공급업체는 조달 과정에서 우선적으로 선정되고 있으며, 불변 아카이브는 기록의 무결성을 훼손하지 않으면서 제17조에 규정된 ‘삭제권’ 요건을 충족하는 데 기여하고 있습니다. 남미, 중동 및 아프리카는 여전히 발전 단계에 있지만 매력적인 시장입니다. 브라질의 LGPD는 GDPR(EU 개인정보보호규정)을 반영하고 있으며, 암호화 및 보고 요건을 추진하고 있습니다. 걸프 국가들은 외국인 직접 투자를 유치하기 위해 주권 클라우드를 구축하고 있습니다.
지연 시간에 민감한 워크로드로 인해 기업들은 데이터를 여러 리전에 복제하고 있습니다. AWS는 전 세계 33개 리전을, Azure는 60개 이상의 리전을 운영하고 있어 세밀한 데이터 저장 위치 선정이 가능해졌습니다. 매장, 공장 또는 휴대전화 기지국에 위치한 엣지·마이크로 데이터센터는 또 다른 계층을 추가하는 것으로, 중앙 저장소와 동기화하기 전에 로컬에서 스냅샷을 생성해야 합니다. 이러한 지리적 특성이 결합되어 클라우드 백업 시장에서 견고한 지역별 파이프라인을 강화하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the cloud backup market size was valued at USD 5.36 billion in 2025 and is estimated to grow from USD 7.13 billion in 2026 to reach USD 21.62 billion by 2031, at a CAGR of 24.84% during the forecast period (2026-2031).
This report is Segmented by Component (Solution, and Services), Deployment Model (Public Cloud, and More), End-User Industry (Banking Financial Services and Insurance, IT and Telecom, and More), Service Provider (Managed Service Provider, and More), Organization Size (Large Enterprises, and Small and Medium-Sized Enterprises), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Cloud Backup Market Trends and Insights
Massive Growth in Data Generation Requiring Affordable, Scalable Storage
Enterprises created 120 zettabytes of data in 2024, straining fixed-capacity arrays. Consumption-based cloud backup aligns cost with active datasets and removes three-year hardware refresh cycles. Hyperscalers' cold object tiers such as Amazon S3 Glacier Instant Retrieval deliver sub-cent-per-gigabyte pricing, enabling decade-long retention without disproportionate spend. Edge caching that transmits only changed blocks mitigates bandwidth limitations, while analytics on backup telemetry support proactive capacity planning. These factors collectively underpin sustained demand for the cloud backup market.
Accelerated Enterprise Adoption of SaaS Platforms Driving Integrated Backup Demand
Microsoft 365 surpassed 400 million paid seats in 2024, yet Microsoft's shared-responsibility model excludes application-layer protection. Enterprises therefore deploy workload-aware tools that snapshot Exchange, SharePoint, and OneDrive data outside the 93-day recycle-bin window. Similar gaps exist for Salesforce and Google Workspace, and the average company now uses 130 SaaS tools. Unified policy engines that orchestrate granular snapshots across disparate APIs have become critical, elevating the cloud backup market as a core pillar of SaaS governance.
Stringent Data-Sovereignty and Cross-Border Transfer Restrictions
China's PIPL forces personal data to remain onshore, while India's DPDP empowers the government to designate restricted categories. European exporters must verify third-country surveillance laws before transfer, inflating due-diligence overhead. These rules drive multinationals to duplicate repositories across jurisdictions, raising infrastructure costs yet stimulating regional spending within the cloud backup market.
Other drivers and restraints analyzed in the detailed report include:
- Rising Enterprise-Wide Cloud Computing Maturity Levels
- Heightened Regulatory Focus on Data-Protection and Resiliency Mandates
- Escalating Hyperscaler Data-Egress Charges Hindering Recovery Economics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solution contracts commanded 63.19% revenue in 2025, yet services are forecast to grow faster at 25.99% CAGR. The cloud backup market size for services reflects rising demand for architecture design, policy scripting, and managed testing. Enterprises that juggle multi-tenant SaaS, container clusters, and legacy mainframes outsource integration to specialists, lifting deal values. Vendors embed AI to classify data and assign retention tiers automatically, tightening compliance posture while lowering storage overhead.
Services growth is reinforced by consumption subscriptions that bundle storage, software, and support. Metallic charges per protected workload, which simplifies procurement for finance teams. Independent validation of backup integrity has become a regulatory staple, boosting third-party audit services. Managed Service Providers with ISO 27001 or SOC 2 certifications capture premium contracts, supporting long-run expansion of the cloud backup market.
Public cloud led 2025 demand at 48.41%, yet hybrid cloud is projected to advance at 25.59% CAGR as firms reconcile in-country mandates with hyperscaler economics. The cloud backup market share for hybrid designs rises when regulators prescribe data localization while boards insist on offsite redundancy. Hybrid topology also supports tiered recovery: mission-critical workloads restore from on-premises copies within minutes, whereas archival data recovers from cloud repositories over hours.
Edge computing widens hybrid relevance. Stores, plants, and towers replicate local snapshots to central clouds during off-peak windows, preserving bandwidth headroom. The EU Data Act, effective in 2024, obliges providers to enable portability, trimming migration risk and further bolstering hybrid adoption. Overall, flexible deployment choice remains a leading purchase criterion in the cloud backup market.
Complete Report Scope:
- By Component
- Solution
- Services
- By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
- By End-User Industry
- Banking, Financial Services and Insurance
- IT and Telecom
- Media and Entertainment
- Retail
- Healthcare
- Manufacturing
- Government and Public Sector
- Education
- Other End-User Industries
- By Service Provider
- Managed Service Provider
- Cloud Service Provider
- Telecom and Communication Provider
- Other Service Providers
- By Organization Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- ASEAN
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America held 35.06% of 2025 revenue thanks to early cloud adoption and mature continuity planning. HIPAA, Sarbanes-Oxley, and state breach laws create compliance urgency, while dense hyperscaler footprints cut latency and enable in-region restores. Asia Pacific is projected to expand at 26.89% CAGR to 2031, the quickest worldwide. China's PIPL and India's DPDP enforce in-country storage, fragmenting architectures yet spurring localized spending that lifts the cloud backup market in both nations.
Europe's landscape is defined by GDPR plus Standard Contractual Clauses that demand granular export controls. Providers hosting data inside EU availability zones enjoy procurement preference, and immutable archives help satisfy Article 17 "right to erasure" requests without compromising record integrity. South America, the Middle East and Africa remain nascent but attractive. Brazil's LGPD mirrors GDPR, driving encryption and reporting requirements; Gulf states are building sovereign clouds to attract foreign direct investment.
Latency-sensitive workloads lead firms to replicate across multiple regions. AWS counts 33 global regions and Azure runs over 60, permitting fine-grained vault placement. Edge micro-data centers in stores, factories, or cell towers add another layer, requiring local snapshots before synchronizing to central repositories. These geographic nuances collectively reinforce robust regional pipelines for the cloud backup market.
- Amazon Web Services, Inc.
- Microsoft Corporation
- IBM Corporation
- Dell Technologies Inc.
- Google LLC
- Veeam Software Group GmbH
- Veritas Technologies LLC
- Commvault Systems, Inc.
- Acronis International GmbH
- Cohesity, Inc.
- Rubrik, Inc.
- Arcserve, LLC
- Barracuda Networks, Inc.
- Backblaze, Inc.
- Carbonite, LLC
- NetApp, Inc.
- Druva Inc.
- Hewlett Packard Enterprise Company
- Oracle Corporation
- Fujitsu Limited
- Cisco Systems, Inc.
- Iron Mountain Incorporated
- Asigra Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Massive Growth in Data Generation Requiring Affordable, Scalable Storage
- 4.2.2 Accelerated Enterprise Adoption of SaaS Platforms Driving Integrated Backup Demand
- 4.2.3 Rising Enterprise-wide Cloud Computing Maturity Levels
- 4.2.4 Heightened Regulatory Focus on Data-Protection & Resiliency Mandates
- 4.2.5 Surge in Adoption of Immutable Storage for Ransomware Insurance Compliance
- 4.2.6 Growing Use of AI-Based Data Classification to Optimize Backup Footprints
- 4.3 Market Restraints
- 4.3.1 Stringent Data-Sovereignty and Cross-Border Transfer Restrictions
- 4.3.2 Persistent Privacy and Security Concerns Around Multi-Tenant Clouds
- 4.3.3 Escalating Hyperscaler Data-Egress Charges Hindering Recovery Economics
- 4.3.4 Scarcity of Edge-Grade Backup Solutions for Operational-Technology Workloads
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solution
- 5.1.2 Services
- 5.2 By Deployment Model
- 5.2.1 Public Cloud
- 5.2.2 Private Cloud
- 5.2.3 Hybrid Cloud
- 5.3 By End-User Industry
- 5.3.1 Banking, Financial Services and Insurance
- 5.3.2 IT and Telecom
- 5.3.3 Media and Entertainment
- 5.3.4 Retail
- 5.3.5 Healthcare
- 5.3.6 Manufacturing
- 5.3.7 Government and Public Sector
- 5.3.8 Education
- 5.3.9 Other End-User Industries
- 5.4 By Service Provider
- 5.4.1 Managed Service Provider
- 5.4.2 Cloud Service Provider
- 5.4.3 Telecom and Communication Provider
- 5.4.4 Other Service Providers
- 5.5 By Organization Size
- 5.5.1 Large Enterprises
- 5.5.2 Small and Medium-Sized Enterprises
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Netherlands
- 5.6.3.7 Russia
- 5.6.3.8 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia and New Zealand
- 5.6.4.6 ASEAN
- 5.6.4.7 Rest of Asia Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Egypt
- 5.6.6.4 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Amazon Web Services, Inc.
- 6.4.2 Microsoft Corporation
- 6.4.3 IBM Corporation
- 6.4.4 Dell Technologies Inc.
- 6.4.5 Google LLC
- 6.4.6 Veeam Software Group GmbH
- 6.4.7 Veritas Technologies LLC
- 6.4.8 Commvault Systems, Inc.
- 6.4.9 Acronis International GmbH
- 6.4.10 Cohesity, Inc.
- 6.4.11 Rubrik, Inc.
- 6.4.12 Arcserve, LLC
- 6.4.13 Barracuda Networks, Inc.
- 6.4.14 Backblaze, Inc.
- 6.4.15 Carbonite, LLC
- 6.4.16 NetApp, Inc.
- 6.4.17 Druva Inc.
- 6.4.18 Hewlett Packard Enterprise Company
- 6.4.19 Oracle Corporation
- 6.4.20 Fujitsu Limited
- 6.4.21 Cisco Systems, Inc.
- 6.4.22 Iron Mountain Incorporated
- 6.4.23 Asigra Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


