

|
시장보고서
상품코드
2124338
지하 유틸리티 매핑 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Underground Utility Mapping - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
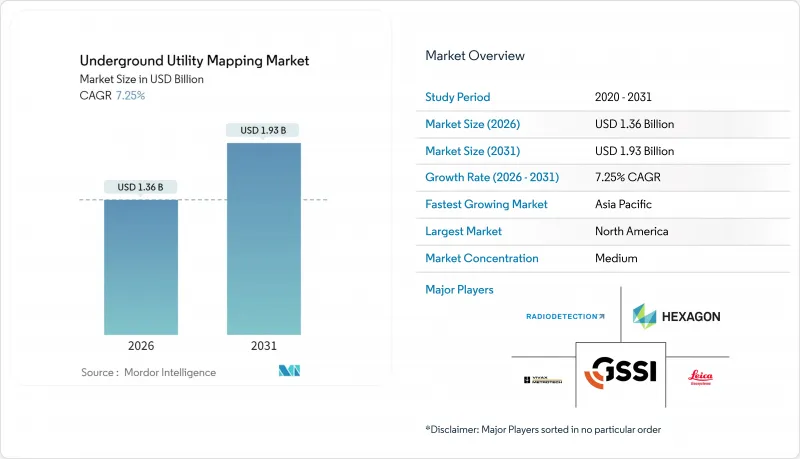
에 의하면, 지하 유틸리티 매핑 시장 규모는 2026년에 13억 6,000만 달러로 추정되고 있어 예측 기간(2026-2031년)에서 CAGR 7.25%로 성장을 지속하여, 2031년에는 19억 3,000만 달러에 이를 전망입니다.
본 보고서는 구성 요소 유형별(솔루션, 서비스), 최종 사용자 산업별(석유 및 가스, 건축 및 건설, 기타),감지 기술별(능동형 무선 주파수(RF) 위치 파악, 수동형 전자기 감지, 고주파 GPR, 기타), 제공 형태별(사내 조사 팀, 조사 업무 외부 위탁 업체, SaaS), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 지하 유틸리티 매핑 시장 동향 및 인사이트
굴착으로 인한 손상에 대한 규제 강화
규제 당국은 권고적인 태도에서 처벌적인 태도로 전환하고 있습니다. 펜실베이니아주의 ‘법 제127호’는 위반 1건당 최대 5만 달러의 벌금을 부과할 수 있도록 허용하고 있으며, 착공 3일 전까지 전자적 위치 확인 요청을 의무화함으로써 매핑이 프로젝트의 기본 일정에 포함되도록 하고 있습니다. 캘리포니아주의 ‘Dig Safe Act(안전 굴착법)’도 유사한 입장을 보이고 있으며, 48시간 이내에 긍정적 응답 기록을 작성하도록 의무화함으로써 정당성을 입증할 수 있는 감사 추적을 확립하고 있습니다. 커먼 그라운드 얼라이언스(Common Ground Alliance)의 기록에 따르면, 2023년 미국에서 발생한 피해 건수는 18만 9,549건, 경제적 손실 총액은 약 300억 달러에 달하여, 비용 절감에 대한 인센티브가 더욱 높아지고 있습니다. 유럽에서는 개정된 ‘건설 제품 규정’에 따라 50만 유로(56만 5,000달러)를 초과하는 프로젝트에 대해 지하 조사가 의무화되면서 매핑에 할당되는 최소 예산이 확대되고 있습니다. 이러한 규제들이 맞물리면서 솔루션 도입 주기가 가속화되고 있으며, 매핑은 단순한 규정 준수 부수 사항에서 핵심적인 리스크 관리 도구로 그 위상이 높아지고 있습니다.
증가하는 FTTH(Fiber-to-the-Home) 구축 규모
미국에서는 2024년에 연결 가구 수가 6,000만 가구를 돌파하고, 2026년까지 7,500만 가구를 목표로 하고 있어, 이로 인해 밀집된 유틸리티 회랑을 피하면서 진행해야 하는 개착 공사가 증가하고 있습니다. 중국은 2027년까지 4억 건의 연결을 계획하고 있으며, 한편 인도의 ‘BharatNet’은 2026년까지 25만 개의 마을 클러스터를 연결할 예정입니다. 광섬유 경로는 대부분의 경우 기존의 가스관, 수도관, 전력선과 평행하게 놓여 있기 때문에 사업자들은 인증된 지하 유틸리티 엔지니어링을 자본 계획에 포함시키고 있습니다. 보험사들은 현재 품질 등급 A 모델을 제시하는 도급업체에 대해 보험료 할인을 제공하고 있으며, 이로 인해 지출 주기가 더욱 촉진되고 있습니다.
고주파 GPR 시스템의 높은 도입 비용
5만-15만 달러 가격대의 시스템은 소규모 계약업체나 지방 자치 단체의 예산을 압박하고 있습니다. 초광대역 플랫폼은 20만 달러에 육박할 수 있으며, 연간 유지보수 계약에는 구매 가격의 12-15%가 추가로 부과됩니다. 수입 관세와 공급업체의 지원 부족으로 인해 신흥국에서 소유 비용이 상승하고 있어, 렌탈 모델이 권장되는 반면 일괄 판매는 제한적입니다.
부문 분석
2025년에는 솔루션이 지하 유틸리티 매핑 시장의 58.63%를 차지했으나, 서비스 매출은 2026년부터 2031년까지 연평균 성장률(CAGR) 9.22%로 증가할 것으로 예측됩니다. 대규모 인프라 소유주들은 현재 사내 인적 자원 부족을 보완하기 위해 탐사, 3D 모델링, 인증 업무를 외부에 위탁하고 있습니다. ASCE 38-22 품질 수준에 따른 제3자 검증을 통해 매핑 비용이 자금 조달 문서에 포함됨에 따라, 프로젝트의 전체 수명 주기 동안 지속적인 서비스 지출이 정착되고 있습니다. 수요가 가장 높은 곳은 공공기관이 채용 동결에 직면하고 있음에도 불구하고 매설물 누락에 대한 법적 책임을 계속 지고 있는 지역으로, 이는 공공기관이 규정 준수를 보장하는 성과 기반 계약을 체결하도록 유도하고 있습니다.
솔루션 부문은 여전히 지중 탐사 레이더(GPR) 장비군과 멀티모달 센서 보유를 선호하는 대형 엔지니어링 컨설팅 기업의 자본 예산의 주축을 이루고 있습니다. 고주파 GPR이 하드웨어 지출의 대부분을 차지하고 있지만, GPR, 전자기파, LiDAR 입력을 결합한 통합 플랫폼은 현장 조사 횟수를 줄이고 사업자의 기술 요건을 완화하기 때문에 주목을 받고 있습니다. 각 벤더들은 현재 총 소유 비용(TCO)을 절감하기 위해 연장 보증 및 클라우드 분석 기능을 패키지로 묶어 제공하고 있으며, 이러한 움직임으로 인해 일회성 장비 판매와 구독 서비스의 경계가 모호해지고 있습니다. 데이터 상호 운용성을 요구하는 소유자가 늘어나는 가운데, 일반적인 GIS 및 BIM 생태계로의 원활한 데이터 업로드를 제공하는 솔루션 제공업체는 장비 교체 주기에서 그 존재감을 강화하고 있습니다.
2025년, 주택 및 상업 프로젝트에서는 굴착 전에 ‘원콜(One-Call)’을 통한 허가 취득이 필수적이기 때문에 건축 및 건설 부문은 지하 유틸리티 매핑 시장 규모의 28.53%를 차지했습니다. 한편, 교통 인프라 부문은 고속도로 확장, 지하철 터널 공사, 고속철도 건설에 있어 타당성 조사 단계부터 지하 유틸리티 엔지니어링이 의무적으로 포함되어야 하기 때문에 연평균 성장률(CAGR) 8.14%로 다른 모든 업종을 상회하는 성장이 예상됩니다. ‘미국 인프라 투자 및 고용법’만 해도 도로 및 교량 공사에 1,100억 달러가 투입되고 있으며, 이로 인해 인증된 위치 확인 업체의 대응 능력을 이미 한계에 다다르게 하고 있는 수년에 걸친 위치 확인 의뢰 파이프라인이 형성되고 있습니다. 인도, 중국, 아세안(ASEAN) 도시의 유사한 메가 프로젝트 역시 이러한 수요 곡선을 재현하고 있으며, 전 세계 서비스 기업들이 현지 측량 업체와의 합작 사업에 참여하도록 촉진하고 있습니다.
전력 배전, 석유 및 가스, 상하수도, 공공 안전 기관이 규제 준수 및 복원력 계획과 관련된 요구를 바탕으로 사용자 기반을 구성하고 있습니다. 전력 회사는 산불 위험을 줄이기 위해 가공 전선을 지하화하고 있으며, 상수도 당국은 납으로 만들어진 급수 지관을 교체하고 있고, 파이프라인 사업자는 PHMSA 규정에 따라 자산의 위치를 명확히 표시해야 합니다. 통신 부문은 FTTH(Fiber-to-the-Home) 구축을 통해 10%대 중반의 점유율을 유지하고 있지만, 서비스 제공 속도는 교통 부문의 장기적인 메가 회랑 계획에 비해 간헐적입니다. 이러한 업종을 종합함으로써 다양한 수익원을 확보할 수 있으며, 사업자는 특정 부문의 경기 변동으로 인한 영향을 완화할 수 있습니다.
지역별 분석
2025년, 북미는 지하 유틸리티 매핑 시장의 33.92%를 차지했습니다. 연방 교통 자금, 주 차원의 과태료 제도, 성숙한 ‘원콜(One-Call)’ 절차 덕분에 매핑은 프로젝트의 전제조건으로 제도화되었습니다. 펜실베이니아주의 ‘법 제127호’와 캘리포니아주의 ‘Dig Safe’ 개정으로 막대한 벌금이 부과됨에 따라, 지하 확인의 중요성이 이사회 차원에서 인식되기 시작했습니다. 캐나다에서는 위치 정보 조회에 대한 리드타임이 단축되고 있으며, 멕시코에서는 니어쇼어링의 물결이 산업 회랑 내 수요를 견인하고 있지만, 법 집행의 불균일성으로 인해 제약을 받고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 10.32%를 나타낼 것으로 예측되며, 이는 지역별로는 가장 빠른 속도입니다. 인도의 1조 4,000억 달러 규모의 ‘국가 인프라 파이프라인’ 계획은 모두 인증된 지하 모델을 필요로 하는 대도시권 및 고속도로 건설 계획을 추진하고 있습니다. 4억 명에게 광섬유를 연결하겠다는 중국의 야심과 활발한 도시 재생 자금이 센서 판매와 서비스 아웃소싱을 활성화하고 있습니다. 아세안(ASEAN)은 지하 유틸리티 엔지니어링을 명시적으로 포함하는 다자간 은행의 대출 조건을 수용하고 있지만, 인력 부족과 고주파 GPR에 대한 수입 관세로 인해 그 진전이 저해되고 있습니다.
유럽, 남미, 중동 및 아프리카가 합쳐져 기타 지역을 구성하고 있습니다. 유럽연합(EU)의 50만 유로(56만 5,000달러)라는 조사 기준액에 따라 회원국 간 수요가 통일되어 있습니다. 한편, 영국에서는 기후 변화에 대한 회복력을 강화하기 위해 가공 전선의 지하 매설이 가속화되고 있습니다. 남미에서는 브라질과 아르헨티나가 상수도관 및 통신 회선의 위치 파악이 필요한 도시 재생 프로그램과 광업 확장을 주도하고 있습니다. NEOM이나 마스달 시티와 같은 중동의 스마트시티 기본 계획에서는 디지털 트윈을 처음부터 구축하고 있으며, 매핑에 대한 지속적인 투자가 보장되고 있습니다. 아프리카는 뒤처져 있지만, 안전 기준이 엄격해진 남아프리카공화국의 광업 지역이나 나이지리아의 도심에서는 회복의 조짐이 보입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the underground utility mapping market size is estimated at USD 1.36 billion in 2026, and is expected to reach USD 1.93 billion by 2031, at a CAGR of 7.25% during the forecast period (2026-2031).
This report is Segmented by Component Type (Solutions, and Services), End-User Industry (Oil and Gas, Building and Construction, and More), Detection Technology (Active Radio-Frequency (RF) Location, Passive Electromagnetic Detection, High-Frequency GPR, and More), Delivery Mode (In-House Survey Teams, Outsourced, and SaaS), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Underground Utility Mapping Market Trends and Insights
Tightening Excavation-Damage Regulations
Regulators have shifted from advisory to punitive postures. Pennsylvania's Act 127 authorizes fines up to USD 50,000 per violation and obliges electronic locate requests three days before breaking ground, embedding mapping into baseline project schedules. California's Dig Safe Act mirrors this stance by mandating the creation of positive-response records within 48 hours, thereby creating a defensible audit trail. The Common Ground Alliance logged 189,549 U.S. damages in 2023, totaling roughly USD 30 billion in economic losses, amplifying the cost-avoidance incentive. Europe now requires subsurface surveys for projects above EUR 500,000 (USD 565,000) under its revised Construction Products Regulation, expanding the minimum mapping budget. Collectively, these mandates accelerate solution purchase cycles and elevate mapping from a compliance afterthought to a core risk-management tool.
Growing Fiber-to-the-Home Rollout Volume
The United States passed 60 million connected premises in 2024 and targets 75 million by 2026, driving trenching projects that must navigate dense utility corridors. China plans 400 million connections by 2027, while India's BharatNet will link 250,000 village clusters by 2026. Because fiber routes often parallel legacy gas, water, and power lines, operators bundle certified subsurface utility engineering into capital plans. Insurers now reward contractors that present Quality Level A models with premium discounts, reinforcing the spending cycle.
High Capital Cost of High-Frequency GPR Systems
Systems priced between USD 50,000 and 150,000 stretch budgets of small contractors and municipal agencies. Ultra-wideband platforms can near USD 200,000, and annual maintenance contracts add 12% to 15% of purchase value. Import tariffs and limited vendor support raise ownership costs in emerging economies, encouraging rental models but limiting outright sales.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Multi-Sensor UAV-Based Mapping Payloads
- Utility ESG Reporting That Requires Buried-Asset Disclosure
- Shortage of Certified Utility-Survey Professionals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services revenue is projected to climb at a 9.22% CAGR between 2026 and 2031, even though solutions commanded 58.63% of underground utility mapping market share in 2025. Large infrastructure owners now outsource detection, 3D modeling, and certification to bridge internal talent shortages. Third-party validation of ASCE 38-22 Quality Levels integrates mapping fees into financing documents, embedding recurring service spend across project lifecycles. Demand is strongest where public agencies face hiring freezes yet remain legally liable for missed utilities, pushing them toward outcome-based contracts that guarantee regulatory compliance.
The solutions segment still anchors capital budgets for heavyweight engineering consultancies that prefer owning ground-penetrating radar fleets and multimodal sensors. High-frequency GPR dominates hardware spend, but integrated platforms that combine GPR, electromagnetic, and LiDAR inputs are gaining traction as they reduce field passes and operator skill requirements. Vendors now bundle extended warranties and cloud analytics to compress total cost of ownership, a move that blurs the line between one-time equipment sales and subscription services. As more owners insist on data interoperability, solution providers that offer seamless uploads into common GIS and BIM ecosystems are tightening their grip on replacement cycles.
Building and construction retained 28.53% of underground utility mapping market size in 2025 because residential and commercial projects must obtain One Call clearances before excavation. Transportation infrastructure, however, is set to outpace all other verticals with an 8.14% CAGR as highway widening, metro tunneling, and high-speed rail mandates embed subsurface utility engineering at the feasibility stage. The U.S. Infrastructure Investment and Jobs Act alone channels USD 110 billion toward road and bridge works, creating a multi-year pipeline of locate requests that already strain certified-locator capacity. Similar megaprojects in India, China, and ASEAN cities are replicating this demand curve, drawing global service firms into joint ventures with local surveyors.
Electric power distribution, oil and gas, water and wastewater, and public-safety agencies round out the user base with needs tied to regulatory compliance and resilience planning. Utilities are burying overhead lines to mitigate wildfire risk, water authorities are replacing lead service laterals, and pipeline operators must mark assets under PHMSA rules. Telecommunications maintains a mid-teens share thanks to fiber-to-the-home builds, yet its service cadence is episodic compared with transportation's long-horizon mega-corridor programs. Collectively, these verticals ensure diversified revenue streams that cushion providers from cyclicality in any single sector.
Complete Report Scope:
- By Component Type
- Solutions
- Ground-Penetrating Radar (GPR)
- Electromagnetic (EM) Locators
- Acoustic and Infra-red System
- Integrated Multi-sensor Platforms
- Services
- Utility Detection and Surveying
- Data Processing and 3D Modelling
- Validation and Certificate
- Solutions
- By End-User Industry
- Public Safety and Emergency Services
- Oil and Gas
- Building and Construction
- Telecommunications
- Electric Power Distribution
- Water and Waste-water Management
- Transportation Infrastructure
- By Detection Technology
- Active Radio-frequency (RF) Location
- Passive Electromagnetic Detection
- High-frequency GPR (500 MHz-3 GHz)
- Ultra-wideband (UWB) GPR
- LiDAR-assisted Subsurface Imaging
- By Device Delivery Mode
- In-house Survey Teams
- Outsourced Survey Service Providers
- Software-as-a-Service Platforms
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America commanded 33.92% of underground utility mapping market share in 2025. Federal transportation funds, state-level fine structures, and mature One Call procedures institutionalize mapping as a prerequisite for projects. Pennsylvania's Act 127 and California's Dig Safe revisions add hefty penalties that elevate subsurface verification to board-level attention. Canada is tightening lead times for location requests, and Mexico's near-shoring wave is driving industrial corridor demand, albeit constrained by uneven enforcement.
Asia-Pacific is forecast to grow at a 10.32% CAGR through 2031, the fastest regional pace. India's USD 1.4 trillion National Infrastructure Pipeline shepherds metro and highway schemes that all require certified underground models. China's ambition to connect 400 million with fiber and vigorous urban-renewal funds energize sensor sales and service outsourcing. ASEAN nations absorb multilateral-bank loan conditions that explicitly include subsurface utility engineering, yet progress is tempered by talent shortages and import duties on high-frequency GPR.
Europe, South America, the Middle East, and Africa collectively form the remainder. The European Union's EUR 500,000 (USD 565,000) survey threshold harmonizes demand across member states, while the United Kingdom accelerates the burial of overhead lines to bolster climate resilience. Brazil and Argentina lead South America via urban-renewal programs and mining expansions that must locate water and telecom lines. Middle Eastern smart-city master plans, such as NEOM and Masdar City, build digital twins from the ground up, ensuring persistent spending on mapping. Africa trails but shows green shoots in South African mining belts and Nigerian urban cores where safety mandates are tightening.
- Hexagon AB
- Leica Geosystems AG
- Geophysical Survey Systems, Inc.
- Radiodetection Ltd.
- Vivax-Metrotech Corp.
- multiVIEW Locates Inc.
- Plowman Craven Ltd.
- Technics Group Ltd.
- Landscope Engineering Ltd.
- Red Laser Scanning Ltd.
- Subterra Utility Mapping Ltd.
- Cardno Ltd.
- Maverick Inspection Ltd.
- McKim & Creed, Inc.
- Underground Services, Inc.
- Badger Daylighting Ltd.
- Vacgroup Aus Pty Ltd.
- Geospatial Corporation
- U-Locate Utility Mapping LLC
- 3D Laser Mapping Ltd.
- Pipehawk plc
- Sensors & Software Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Smart-City Programs Mandating Digital Twin-Ready Subsurface Data
- 4.2.2 Tightening Excavation-Damage Regulations in North America and Europe
- 4.2.3 Growing Fiber-to-the-Home (FTTH) Rollout Volume
- 4.2.4 Adoption of Multi-Sensor UAV-Based Mapping Payloads
- 4.2.5 Utility ESG Reporting That Now Requires Buried-Asset Disclosure
- 4.2.6 Insurtech Discounts for Projects with Certified Subsurface Models
- 4.3 Market Restraints
- 4.3.1 High Capital Cost of High-Frequency Ground-Penetrating Radar Systems
- 4.3.2 Shortage of Certified Utility-Survey Professionals
- 4.3.3 Data-Ownership Disputes Between Municipalities and Contractors
- 4.3.4 Signal Interference in Congested Mega-City Environments
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component Type
- 5.1.1 Solutions
- 5.1.1.1 Ground-Penetrating Radar (GPR)
- 5.1.1.2 Electromagnetic (EM) Locators
- 5.1.1.3 Acoustic and Infra-red System
- 5.1.1.4 Integrated Multi-sensor Platforms
- 5.1.2 Services
- 5.1.2.1 Utility Detection and Surveying
- 5.1.2.2 Data Processing and 3D Modelling
- 5.1.2.3 Validation and Certificate
- 5.1.1 Solutions
- 5.2 By End-User Industry
- 5.2.1 Public Safety and Emergency Services
- 5.2.2 Oil and Gas
- 5.2.3 Building and Construction
- 5.2.4 Telecommunications
- 5.2.5 Electric Power Distribution
- 5.2.6 Water and Waste-water Management
- 5.2.7 Transportation Infrastructure
- 5.3 By Detection Technology
- 5.3.1 Active Radio-frequency (RF) Location
- 5.3.2 Passive Electromagnetic Detection
- 5.3.3 High-frequency GPR (500 MHz-3 GHz)
- 5.3.4 Ultra-wideband (UWB) GPR
- 5.3.5 LiDAR-assisted Subsurface Imaging
- 5.4 By Device Delivery Mode
- 5.4.1 In-house Survey Teams
- 5.4.2 Outsourced Survey Service Providers
- 5.4.3 Software-as-a-Service Platforms
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Hexagon AB
- 6.4.2 Leica Geosystems AG
- 6.4.3 Geophysical Survey Systems, Inc.
- 6.4.4 Radiodetection Ltd.
- 6.4.5 Vivax-Metrotech Corp.
- 6.4.6 multiVIEW Locates Inc.
- 6.4.7 Plowman Craven Ltd.
- 6.4.8 Technics Group Ltd.
- 6.4.9 Landscope Engineering Ltd.
- 6.4.10 Red Laser Scanning Ltd.
- 6.4.11 Subterra Utility Mapping Ltd.
- 6.4.12 Cardno Ltd.
- 6.4.13 Maverick Inspection Ltd.
- 6.4.14 McKim & Creed, Inc.
- 6.4.15 Underground Services, Inc.
- 6.4.16 Badger Daylighting Ltd.
- 6.4.17 Vacgroup Aus Pty Ltd.
- 6.4.18 Geospatial Corporation
- 6.4.19 U-Locate Utility Mapping LLC
- 6.4.20 3D Laser Mapping Ltd.
- 6.4.21 Pipehawk plc
- 6.4.22 Sensors & Software Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


