|
시장보고서
상품코드
2124345
네트워크 암호화 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Network Encryption - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 네트워크 암호화 시장 규모는 2025년 52억 4,000만 달러로 평가되었고, 2026년에는 56억 7,000만 달러로 추정되고, 2026-2031년 CAGR 8.12%로 성장을 지속할 전망이며, 2031년에는 83억 7,000만 달러에 달할 것으로 예측됩니다.

본 보고서는 도입 형태별(클라우드, 온프레미스), 구성 요소별(하드웨어, 솔루션 및 서비스), 조직 규모별(중소기업, 대기업), 최종 사용자 산업별(통신 및 IT, 은행, 금융서비스 및 보험(BFSI), 정부, 미디어 및 엔터테인먼트, 헬스케어, 국방·항공우주, 기타 최종 사용자 산업) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 네트워크 암호화 시장 동향 및 인사이트
네트워크 보안 침해 증가
2024년, 랜섬웨어 공격과 국가가 개입한 침입의 빈도와 교묘함이 증가함에 따라, 이사회는 전송 중인 데이터 채널 전체에 대한 암호화 투자를 가속화했습니다. 미국, 유럽 및 아시아태평양의 일부 관할권에서 정보 유출 공개 법에 따라 보호되지 않은 데이터 유출에 대해 무거운 처벌이 부과됨에 따라, 기업들은 외부 통신은 물론 내부 이스트-웨스트 트래픽도 암호화해야만 합니다. 보험사는 보험 약관을 엄격하게 적용하여, 피보험자가 네트워크 전반에 걸친 암호화 대책의 적용을 입증할 수 있는 경우에만 보험료 할인을 적용하게 되었습니다. 그 결과, 조달 부서는 네트워크 수준의 암호화를 단순한 선택적 보호 수단이 아닌 기본적인 통제 수단으로 취급하게 되었으며, 전체 IT 예산이 긴축되는 상황에서도 지속적인 지출이 촉진되고 있습니다. 도입이 용이한 어플라이언스나 자동화된 정책 엔진을 제공할 수 있는 벤더는 시장 점유율을 빠르게 확대되고 있습니다.
클라우드 기반 워크로드 도입 가속화
클라우드 전환으로 인해 멀티 클라우드 환경 전반에서 워크로드가 몇 초 단위로 시작 및 중지됨에 따라, 암호화의 민첩성이 새롭게 중요시되고 있습니다. 현재 네이티브 클라우드 네트워킹 서비스에는 고급 암호화 기능이 내장되어 있어, 보안 팀은 키 거버넌스를 중앙에서 관리할 수 있는 한편, 용도 소유자는 DevOps의 속도를 유지할 수 있습니다. 서비스 메시 프레임워크는 투명한 TLS 종료를 통합하고 있어, 개발자가 암호화 호출을 코딩할 필요가 없어졌습니다. 종량제 가격 책정으로 중소기업(SME)의 진입 장벽이 낮아져, 자본 투자를 하지 않고도 대기업과 동등한 보안 체제를 구축할 수 있게 되었습니다. 그 결과, 클라우드 중심의 암호화 플랫폼은 두 자릿수 성장을 기록하며, 이를 보완하는 ‘키 관리 서비스(KMAAS)’ 솔루션에 대한 수요를 견인하고 있습니다.
네트워크 암호화 솔루션의 높은 도입 비용
종합적인 도입을 위해서는 대부분의 경우 전용 어플라이언스, 컨설팅 서비스 및 직원 교육이 필요하며, 중견 기업의 경우 프로젝트 비용이 50만 달러에서 500만 달러를 훨씬 초과하는 수준까지 치솟습니다. 신흥국에서는 현지 통화 변동으로 인해 수입 하드웨어 가격이 상승하기 때문에 예산 측면의 압박이 더욱 심각합니다. 게다가 레거시 스위치나 라우터에는 암호화 가속 기능이 내장되어 있지 않은 경우가 있어, 고액의 인프라 갱신을 강요당하기도 합니다. 관리형 서비스는 설비 투자 부담을 줄여주지만, 중소기업의 경우 지속적인 구독료 지불이 여전히 부담으로 작용하고 있습니다. 그 결과, 가격에 민감한 구매자들은 프로젝트를 미루거나 그 범위를 축소하기 때문에 규제 대상 산업 이외의 부문에서는 단기적인 보급이 제한적입니다.
부문 분석
클라우드 도입은 2031년까지 9.87%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측되지만, 2025년 시점에서도 온프레미스 배포는 네트워크 암호화 시장 점유율의 56.74%를 차지했습니다. BFSI(은행 및 금융 및 보험) 및 정부 부문에서 레거시 용도의 방대한 도입 실적과 엄격한 데이터 주권 규정이 온프레미스 수요를 뒷받침하는 한편, 새로운 디지털 서비스에서는 클라우드 네이티브 암호화 솔루션이 표준이 되고 있습니다. 주요 공급업체들은 키 수명 주기 관리 및 인증서 자동 갱신 기능을 번들로 제공하여 보안 팀의 운영 부담을 줄이고 있습니다.
조직이 미션 크리티컬 워크로드를 온프레미스에 유지하면서 개발, 분석, 고객 서비스를 클라우드 백본을 통해 라우팅함에 따라 하이브리드 패턴이 대두되고 있습니다. 이러한 ‘2단 속도’ 아키텍처를 통해 구매자는 기존 투자를 포기하지 않고도 종량제 암호화를 시도해 볼 수 있습니다. 온프레미스 장비부터 퍼블릭 클라우드상의 가상 어플라이언스에 이르기까지 전반에 걸쳐 작동하는 통합 정책 엔진을 제공하는 벤더는 고객 유지율을 높이고 있습니다. 포스트 양자 알고리즘이 주류가 됨에 따라, 클라우드 플랫폼은 더 빠른 업그레이드 주기를 제공하여 장기적인 수요를 호스팅형 암호화 모델로 전환시킬 가능성이 있습니다.
2025년에도 초고속 링크가 라인 레이트 성능을 유지하기 위해 여전히 ASIC 및 FPGA에 의존하고 있기 때문에 네트워크 암호화 시장에서 하드웨어의 점유율은 49.01%를 유지했습니다. 그러나 솔루션 및 서비스 부문은 연평균 성장률(CAGR) 10.05%를 기록하며, 유연하고 소프트웨어 기반 보안으로의 전환을 보여주고 있습니다. 기업들은 인프라스트럭처-어즈-코드(IaC) 워크플로우와 통합되는 API 기반 오케스트레이션을 중시하고 있으며, 이를 통해 몇 초 이내에 터널을 동적으로 생성하거나 정책을 변경할 수 있습니다.
관리형 보안 서비스 제공업체는 위협 감지, 인증서 자동화, 제로 트러스트 세분화를 결합한 번들형 서비스에 암호화 기능을 통합하고 있습니다. 인공지능(AI)은 주요 사용 패턴을 분석하고 인증서 만료일을 예측하여 지원함으로써 예기치 않은 서비스 중단을 줄입니다. 또한 모듈식 라이선싱 체계를 통해 고객은 대규모 시스템 업데이트 없이도 대역폭이나 알고리즘 제품군을 확장할 수 있습니다. 예측 기간 동안 칩 수준의 암호화 블록은 상품화가 진행되는 반면, 차별화 요소는 소프트웨어 분석, 규정 준수 보고 및 보다 광범위한 통합 기능으로 전환될 것입니다.
지역별 분석
북미는 2025년 매출의 33.45%를 차지한 것으로 평가되었으며, 이는 제로 트러스트의 조기 도입, 넉넉한 사이버 보안 예산, 그리고 주요 암호화 벤더 다수가 인근에 위치해 있다는 점이 배경으로 작용합니다. 2026년까지 양자 내성 시스템으로의 전환을 의무화하는 연방 정부의 지침에 따라 국내 내 업그레이드 속도가 더욱 가속화되고 있습니다. 마찬가지로, 미국의 통신 사업자들도 전국 규모의 5G 프로그램에 인라인 암호화를 포함시켜 장비 교체 주기를 촉진하고 있습니다.
아시아태평양은 중국, 인도, 동남아시아의 대규모 클라우드 투자에 힘입어 2031년까지 연평균 성장률(CAGR) 8.86%라는 가장 높은 성장률을 보일 것으로 예측됩니다. 지역 규제 당국이 데이터 거주 규정을 강화하고 있어 기업들은 현지에서 관리되는 키 저장소의 도입을 강요받고 있습니다. 각국 정부는 양자 연구와 5G 인프라에 경제 대책 자금을 투입하고 있으며, 이를 통해 암호화 기능을 갖춘 하드웨어가 간접적으로 지원받고 있습니다. 일본의 금융 기관들은 고전 암호와 격자 암호를 결합한 이중 알고리즘 방식의 시범 운영을 진행 중이며, 이는 포스트 양자암호화로의 전환 물결이 머지않아 도래할 것임을 시사합니다.
유럽은 여전히 중요한 시장이며, GDPR(EU 개인정보보호규정)에 따른 과징금이 암호화에 대한 지속적인 투자를 뒷받침하고 있습니다. 조만간 시행될 ‘사이버 복원력 법’은 보안 조치의 의무화를 커넥티드 제품까지 확대하여, 간접적으로 암호화 채널의 적용 범위를 넓히게 될 것입니다. 독일과 프랑스의 통신 사업자들은 Open RAN 구축에 트래픽 계층 암호화를 통합하고 있는 반면, 스칸디나비아 국가들은 양자 키 배포(QKD) 백본의 초기 시험을 주도하고 있습니다. 중동 및 아프리카 및 남미에서도 도입이 진행되고 있지만, 기술 인력 부족과 예산 제약으로 인해 고객들은 매니지드 서비스나 클라우드 도입 모델로 눈을 돌리고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
제8장 투자 분석
AJY 26.09.09According to Mordor Intelligence, the network encryption market size is expected to grow from USD 5.24 billion in 2025 to USD 5.67 billion in 2026 and is forecast to reach USD 8.37 billion by 2031 at 8.12% CAGR over 2026-2031.
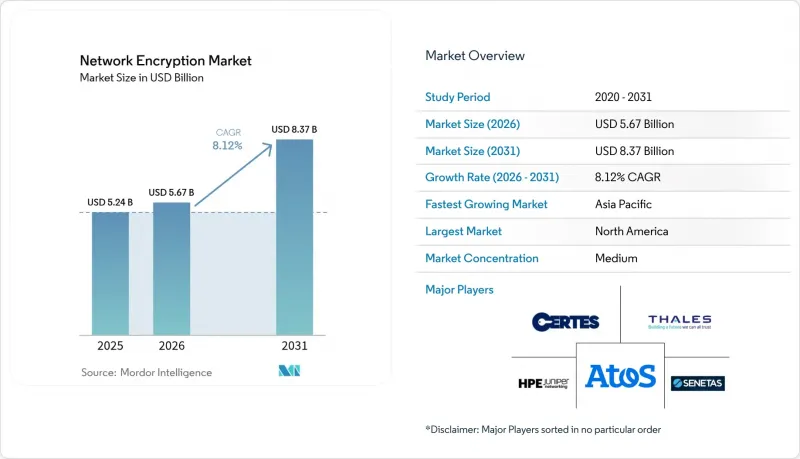
This report is Segmented by Deployment Type (Cloud, On-Premise), Component (Hardware, Solutions and Services), Organization Size (Small and Medium-Sized Enterprises, Large-Sized Enterprises), End-User Industry (Telecom and IT, BFSI, Government, Media and Entertainment, Healthcare, Defence and Aerospace, Other End-User Industries), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Network Encryption Market Trends and Insights
Increasing Number of Network Security Breaches
Ransomware campaigns and state-sponsored intrusions grew in frequency and sophistication during 2024, driving boards to accelerate encryption investments across data-in-motion channels. Breach disclosure laws in the United States, Europe, and several Asia-Pacific jurisdictions impose heavy penalties for unprotected data exposure, prompting enterprises to encrypt internal east-west traffic alongside external communications. Insurance underwriters have tightened policy terms, granting premium discounts only when policyholders can prove ubiquitous encryption coverage. As a result, procurement teams now treat network-level encryption as a baseline control, rather than an optional safeguard, which propels continuous spending even when broader IT budgets are tightened. Vendors able to deliver easy-to-deploy appliances and automated policy engines gain rapid traction.
Accelerating Adoption of Cloud-Based Workloads
Cloud migration places new emphasis on encryption agility, because workloads spin up and down within seconds across multi-cloud footprints. Native cloud networking services now incorporate advanced encryption, enabling security teams to centralize key governance while application owners maintain DevOps velocity. Service mesh frameworks integrate transparent TLS termination, removing the need for developers to code encryption calls. Consumption-based pricing lowers entry barriers for SMEs, enabling them to match the security posture of larger peers without capital purchases. Consequently, cloud-centric encryption platforms experience double-digit growth, driving demand for complementary key management-as-a-service offerings.
High Implementation Cost of Network Encryption Solutions
Comprehensive deployments often require specialized appliances, consulting services, and staff training, driving project outlays from USD 500,000 to well above USD 5 million for mid-sized enterprises. Budget pressure is more acute in emerging economies where local currency fluctuations inflate imported hardware prices. Additionally, legacy switches and routers may lack built-in crypto acceleration, forcing expensive infrastructure refreshes. Managed services do offset capital burdens, but small businesses still struggle with recurring subscription fees. As a result, price-sensitive buyers defer or narrow project scope, limiting near-term penetration in segments outside regulated verticals.
Other drivers and restraints analyzed in the detailed report include:
- Surge in 5G Rollouts Requiring High-Speed Inline Encryption
- Compliance Mandates Such as GDPR and HIPAA
- Performance Overhead and Latency Concerns in High-Speed Networks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud implementations are projected to register the fastest 9.87% CAGR through 2031, yet on-premise deployments still represented 56.74% of the network encryption market share in 2025. The large installed base of legacy applications and stringent data sovereignty rules in BFSI and government sectors anchor on-premise demand, while new digital services default to cloud-native encryption offerings. Major providers bundle key lifecycle management and automated certificate rotation, lowering the operational burden for security teams.
Hybrid patterns emerge as organizations retain mission-critical workloads on-site but route development, analytics, and customer-facing services through cloud backbones. This two-speed architecture allows buyers to experiment with consumption-based encryption without abandoning their existing investments. Vendors that supply unified policy engines capable of extending across on-premises gear and virtual appliances in public clouds gain account stickiness. As post-quantum algorithms become mainstream, cloud platforms offer faster upgrade cycles, potentially tilting long-term volume toward hosted encryption models.
Hardware retained 49.01% of the network encryption market share in 2025, as ultrafast links still rely on ASICs and FPGAs to maintain line-rate performance. Yet the solutions and services segment posts a 10.05% CAGR, illustrating the pivot toward flexible, software-controlled security. Enterprises value API-driven orchestration that integrates with infrastructure-as-code workflows, enabling the dynamic creation of tunnels and policy changes within seconds.
Managed security service providers integrate encryption into bundled offerings that combine threat detection, certificate automation, and zero-trust segmentation. Artificial intelligence assists by analyzing key usage patterns and predicting certificate expirations, reducing unplanned outages. Modular licensing also allows customers to scale bandwidth or algorithm suites without forklift upgrades. Over the forecast period, chip-level crypto blocks will become commoditized, while differentiation will shift to software analytics, compliance reporting, and broader integration capabilities.
Complete Report Scope:
- By Deployment Type
- Cloud
- On-premise
- By Component
- Hardware
- Solutions and Services
- By Organization Size
- Small and Medium-Sized Enterprises
- Large-Sized Enterprises
- By End-User Industry
- Telecom and IT
- BFSI
- Government
- Media and Entertainment
- Healthcare
- Defence and Aerospace
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 33.45% of the revenue in 2025, underpinned by early zero-trust adoption, rich cyber budgets, and proximity to most leading encryption vendors. Federal mandates requiring quantum-resistant migration by 2026 further accelerate domestic upgrades. U.S. carriers likewise bundle inline encryption into nationwide 5G programs, stimulating equipment refresh cycles.
The Asia Pacific is projected to deliver the fastest 8.86% CAGR through 2031, driven by significant cloud investments in China, India, and Southeast Asia. Regional regulators tighten data residency rules, prompting enterprises to deploy locally managed key stores. Governments channel stimulus funds toward quantum research and 5G infrastructure, indirectly subsidizing encryption-capable hardware. Japanese financial institutions are piloting dual-algorithm schemes that combine classical and lattice-based ciphers, signaling an upcoming wave of post-quantum transitions.
Europe remains a pivotal market, as GDPR fines motivate ongoing spending on encryption. The forthcoming Cyber Resilience Act extends mandatory security controls to connected products, indirectly broadening the scope of encrypted channels. Telecom operators in Germany and France are integrating traffic-layer encryption into their Open RAN rollouts, while Scandinavian countries are leading early trials of quantum key distribution backbones. The Middle East and Africa, as well as South America, show rising adoption, although skills shortages and budget constraints push customers toward managed services and cloud deployment models.
- Thales Trusted Cyber Technologies
- Juniper Networks Inc.
- Atos SE
- Certes Networks Inc.
- Senetas Corporation Limited
- Viasat Inc.
- Raytheon Technologies Corporation
- Securosys SA
- PacketLight Networks Ltd.
- Rohde and Schwarz Cybersecurity GmbH
- Colt Technology Services Group Limited
- Ciena Corporation
- Cisco Systems Inc.
- Huawei Technologies Co. Ltd.
- Nokia Corporation
- ADVA Optical Networking SE
- Arista Networks Inc.
- Fortinet Inc.
- Palo Alto Networks Inc.
- Microchip Technology Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors
- 4.3 Market Drivers
- 4.3.1 Increasing Number of Network Security Breaches
- 4.3.2 Accelerating Adoption of Cloud-Based Workloads
- 4.3.3 Surge in 5G Rollouts Requiring High-Speed Inline Encryption
- 4.3.4 Compliance Mandates such as GDPR and HIPAA Driving Encryption Adoption
- 4.3.5 Growing Concern Over Quantum Computing Threats to Classical Cryptography
- 4.3.6 Rising Adoption of Zero Trust Architectures at Data Transport Layer
- 4.4 Market Restraints
- 4.4.1 High Implementation Cost of Network Encryption Solutions
- 4.4.2 Performance Overhead and Latency Concerns in High-Speed Networks
- 4.4.3 Interoperability Issues Across Multi-Vendor Environments
- 4.4.4 Shortage of Skilled Cryptography Professionals
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Type
- 5.1.1 Cloud
- 5.1.2 On-premise
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.2 Solutions and Services
- 5.3 By Organization Size
- 5.3.1 Small and Medium-Sized Enterprises
- 5.3.2 Large-Sized Enterprises
- 5.4 By End-User Industry
- 5.4.1 Telecom and IT
- 5.4.2 BFSI
- 5.4.3 Government
- 5.4.4 Media and Entertainment
- 5.4.5 Healthcare
- 5.4.6 Defence and Aerospace
- 5.4.7 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Thales Trusted Cyber Technologies
- 6.4.2 Juniper Networks Inc.
- 6.4.3 Atos SE
- 6.4.4 Certes Networks Inc.
- 6.4.5 Senetas Corporation Limited
- 6.4.6 Viasat Inc.
- 6.4.7 Raytheon Technologies Corporation
- 6.4.8 Securosys SA
- 6.4.9 PacketLight Networks Ltd.
- 6.4.10 Rohde and Schwarz Cybersecurity GmbH
- 6.4.11 Colt Technology Services Group Limited
- 6.4.12 Ciena Corporation
- 6.4.13 Cisco Systems Inc.
- 6.4.14 Huawei Technologies Co. Ltd.
- 6.4.15 Nokia Corporation
- 6.4.16 ADVA Optical Networking SE
- 6.4.17 Arista Networks Inc.
- 6.4.18 Fortinet Inc.
- 6.4.19 Palo Alto Networks Inc.
- 6.4.20 Microchip Technology Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment