

|
시장보고서
상품코드
2124350
하이드록시아파타이트 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Hydroxyapatite - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
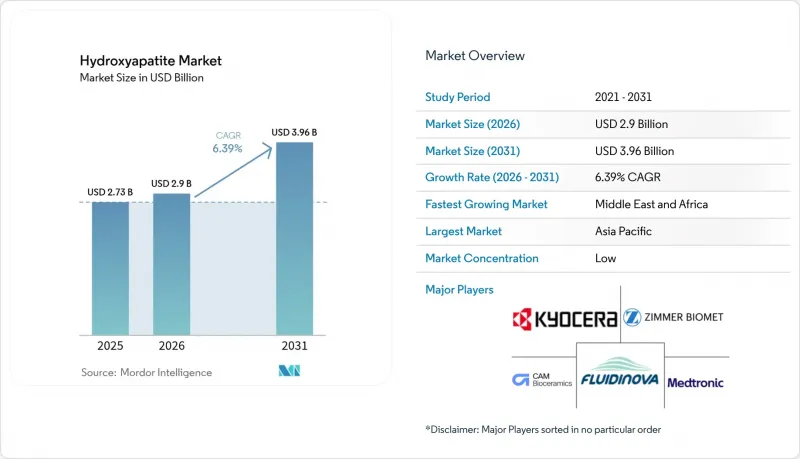
에 의하면, 하이드록시아파타이트 시장 규모는 2025년에 27억 3,000만 달러, 2026년에 29억 달러가 되어, 2031년까지 39억 6,000만 달러에 이를 것으로 예측되며, 2026-2031년까지 CAGR 6.39%로 성장할 전망입니다.
본 보고서는 입자 크기별(나노 크기, 마이크로 크기, 매크로 크기), 공급원별(합성, 생물 유래), 형태별(분말, 과립, 코팅·페이스트), 용도별(치과 치료, 정형외과, 성형외과·미용외과, 기타 산업용), 지역별(아시아태평양, 북미, 유럽, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 하이드록시아파타이트 시장 동향 및 인사이트
고령화가 진행되는 경제권에서의 치과 임플란트 붐
2027년까지 일본, 독일, 이탈리아 주민의 5분의 1 이상이 65세 이상이 될 것으로 예상되며, 탈착식 틀니 대신 HA 코팅이 적용된 임플란트에 대한 수요가 증가하고 있습니다. 임상 연구에 따르면, HA 코팅이 적용된 임플란트 포스트는 코팅되지 않은 티타늄 제품에 비해 치료 기간이 단축되는 것으로 나타났습니다. 이러한 장점 덕분에 보험 적용 체계가 잘 갖춰진 시장에서 프리미엄 가격을 유지할 수 있게 되었습니다. 각 치과 기기 제조업체들은 현재 하악 임플란트 분야에서도 유사한 성공을 목표로 하고 있습니다. 2025년 4월, 일본은 HA 코팅이 적용된 치과 고정체의 보험 적용 범위를 확대했으며, 2028년 이후 연간 시술 건수가 증가할 것으로 예측됩니다. 선견지명을 갖춘 치과 병원에서는 현재 HA 코팅을 디지털 덴티스트리 과정에 통합하고 있으며, 이를 통해 진료 시간 단축과 환자 회전율 향상으로 이어지고 있습니다. 이러한 동향은 하이드록시아파타이트 시장을 뒷받침하며, 부유한 국가에서 꾸준한 수요를 확보하고 있습니다.
정형외과용 임플란트 시술 건수 증가
2025년, 전 세계 고관절 및 무릎 관절 치환술 건수는 대폭 증가했으며, 그 총 건수 중 재수술이 상당한 비중을 차지했습니다. 외과의사들은 척추 고정술 시 장골능 자가골 이식을 피하고, HA가 포함된 케이지를 점점 더 많이 선택하고 있습니다. 이러한 선택으로 인해 수술 시간이 40분 가까이 단축될 뿐만 아니라 감염 위험도 감소합니다. 후외측 고정용 성형 가능한 스캐폴드 등 주입형 HA-콜라겐 퍼티는 임상 현장에서 신뢰를 얻고 있습니다. 아시아태평양에서는 주로 중국과 인도에서 선택적 수술이 증가함에 따라 정형외과용 기기 매출이 크게 증가했습니다. 이러한 수술 건수의 꾸준한 증가와 보험사의 프리미엄 코팅에 대한 수용도 상승이 맞물려 하이드록시아파타이트 시장을 견인하고 있습니다.
임플란트 수술의 높은 비용과 규제상의 장벽
미국에서는 단일 치아 임플란트 비용이 고가입니다. HA 코팅을 추가하면 부품 비용이 더욱 상승합니다. 일상적인 치과 치료는 연방 정부 보험 적용 대상이 아니기 때문에 이러한 가격 체계로 인해 많은 메디케어 수혜자들이 치료를 받지 못하고 있습니다. 정형외과 부문에서는 HA 이식편을 이용한 재수술로 인해 병원의 청구액이 대폭 증가할 가능성이 있습니다. 그러나 민간 보험사들은 특히 90일 이내 재입원을 대상으로 하는 종합적 지급 모델 하에서 이러한 비용을 엄격하게 모니터링하고 있습니다. 각 제조업체는 510(k) 신청 건마다 막대한 비용을 부담하고 있습니다. 이 비용에는 기계적 검사, 생체적합성 검사, 무균성 검증이 포함됩니다. 유럽의 MDR(의료기기 규정)로 인해 CE 마크 취득까지의 기간이 연장되면서, 제품 출시에 따른 현금 흐름 발생이 지연되고 있습니다. 이러한 요인에 더해 고액의 수술 비용과 엄격한 규제 요건이 맞물려, 하이드록시아파타이트 시장의 단기적인 성장을 둔화시키고 있습니다.
부문 분석
나노 크기의 분말은 2031년까지 연평균 성장률(CAGR) 7.09%로 성장할 전망이며, 이는 하이드록시아파타이트 시장 전체의 평균 성장률을 상회하는 수치입니다. 이러한 성장 가속화는 불과 48시간 만에 단백질 흡착을 촉진하는 해당 분말의 표면적에 기인합니다. 치주 외과 의사들은 이러한 분말을 조직 유도막에 활용하여, 섬유성 재생이 아닌 뼈에 의한 충진을 보장합니다. 마이크로 크기의 등급은 2025년에도 여전히 하이드록시아파타이트 시장의 47.65% 점유율을 차지하며 시장을 독점하고 있습니다. 그 충진 밀도로 인해 압축 강도를 확보할 수 있으므로 고관절 스템이나 척추 케이지에 최적입니다.
마이크로 분말용으로 최적화된 습식 침전 플랜트에서는 핵 형성을 유지하는 것이 과제로 대두되고 있습니다. 이러한 제약으로 인해 공급업체는 더 비싼 졸-겔법이나 수열법용 반응 장치에 투자할 수밖에 없습니다. ISO 13779-3는 입자 직경 측정에 관한 지침을 제공하지만, 성능 기준에 대해서는 불충분하므로 구매자가 독자적인 사양을 수립해야 합니다. 특히, 가리비 껍질 유래 나노 HA는 뮤탄스 연쇄상구균에 대해 현저한 항균 효과를 나타내며, 뼈의 성장을 가속하는 동시에 박테리아와 싸우는 이중 역할을 할 가능성이 시사되고 있습니다. EU에서는 화장품에 대한 상한 규제가 마련되어 있지만, 이러한 규제는 현재로서는 임플란트에는 적용되지 않습니다. 그러나 만성 흡입에 관한 지속적인 연구가 향후 규제에 영향을 미칠 가능성이 있습니다. 그 결과, 전문 외과 분야에서 채택이 두드러지는 추세를 보이고 있으며, 일반 치과용도로의 더 광범위한 확대가 기대되고 있습니다.
2025년 생산량 중 합성 생산이 71.85%를 차지하고 있으며, 이는 ISO 13485 품질 관리 시스템의 엄격한 모니터링 하에 Ca/P 비율이 정밀하게 관리되고 있음을 반영합니다. 60-90℃ 범위에서 시행되는 습식 침전법을 통해 질산칼슘과 인산이암모늄이 능숙하게 변환됩니다. 이렇게 얻어지는 범용 등급의 제품은 FOB 중국 가격으로 거래되고 있습니다. 한편, 더 높은 순도를 자랑하는 졸-겔법을 통한 배치 생산 제품은 X선 영상의 선명성이 최우선으로 요구되는 두개안면 시장용으로 공급되고 있습니다.
바이오 유래 하이드록시아파타이트 시장은 연평균 성장률(CAGR) 6.83%로 확대되고 있습니다. 이러한 성장은 주로 순환 경제를 촉진하는 규제와 해양 사료 유래 미량의 스트론튬 및 마그네슘이 가진 골형성 촉진 효과에 기인합니다. 900-1,000℃에서 소성하면 달걀 껍질 폐기물로부터 다공성 HA가 생성됩니다. 한편, 산호 유래 제품은 혈관 침투를 촉진하는 상호 연결된 통로를 갖추고 있지만, CITES 규제로 인한 공급 제약에 직면해 있습니다. 일본산 가리비에서 추출한 분말 ‘쉘 아파타이트(Shell Apatite)’는 2025년에 지역 치과에서 처음 도입되었으며, 현재 CE 인증 획득을 목표로 하고 있습니다. 그러나 광물 내 미량 원소의 편차가 로트 출하 시 과제로 대두되고 있어, 혁신가들은 해결책으로 블록체인 방식의 원산지 기록 도입에 주목하고 있습니다. 요약하자면, 지속가능성에 대한 고려가 중요시됨에 따라 바이오 유래 제품은 단순한 신기함에서 벗어나 하이드록시아파타이트 시장의 핵심 축으로 자리 잡아가고 있습니다.
지역별 분석
2025년 세계 매출에서 아시아태평양의 비중은 39.25%였습니다. 중국의 습식 침전법에 의한 생산 능력 덕분에 유럽 및 미국 제품보다 훨씬 저렴한 범용 분말이 공급되고 있으며, 이는 동남아시아의 예산에 민감한 치과에 점차 보급되고 있습니다. 2025년 4월 일본에서 HA 코팅 치과 임플란트에 대한 보험 적용 범위가 확대됨에 따라 연간 시술 건수가 증가할 것으로 예상되며, Matsumoto Koshou와 같은 국내 졸-겔법 공급업체에 혜택을 줄 전망입니다. 2025년, 한국의 규제 당국은 3D 프린팅된 HA 임플란트의 승인 건수를 두 배로 늘려 적층 가공 기술에 대한 자신감을 보여주었습니다. 한편, 인도에서는 2025년에 정형외과용 의료기기의 성장이 예상되지만, 공립 병원에서는 여전히 자가 이식편이 선호되고 있어 HA 공급업체에게는 과제가 되고 있습니다.
북미에서는 환자 맞춤형 3D 프린팅, HA-콜라겐 퍼티, CaHA 진피 필러 등의 혁신에 힘입어 한 자릿수 중반의 꾸준한 성장이 예상됩니다. Zimmer Biomet의 FDA 승인을 받은 ‘옥스포드 니(Oxford Knee)’는 코팅 내구성 측면에서 새로운 기준을 제시하며, 경쟁사들이 제품을 강화하도록 촉진하고 있습니다. 한편, CMS에 의한 일반 치과 임플란트의 적용 제외로 인해 고령층에서의 채택은 제한되고 있지만, 90일 이내의 합병증 발생률을 일정 수준으로 억제할 수 있다면, 시범 사업으로서의 포괄 지급 제도가 HA 코팅이 적용된 임플란트의 보험 적용으로 가는 길을 열어줄 가능성이 있습니다. 캐나다에서는 도시 지역의 민간 클리닉이 고급 HA 제품을 선호하는 경향이 있는 반면, 지방 병원에서는 코팅되지 않은 금속 임플란트를 계속 사용하는 경우가 많아 주별 의료 제도 간의 격차가 두드러지고 있습니다. 멕시코의 니어쇼어링 추진에 힘입어, 2025년에는 두 개의 다국적 기업이 몬테레이에 HA 코팅 시설을 설립했습니다.
유럽에서는 MDR 2017/745에 따른 승인 절차의 장기화로 어려움을 겪고 있지만, 생체 적합성을 중시하는 자세는 HA가 본래 지닌 장점과 부합합니다. 독일, 영국, 프랑스의 높은 인공관절 치환술 시행률은 유럽 HA 수요의 상당 부분을 차지하고 있습니다. 중동 및 아프리카에서는 ‘사우디 비전 2030’에 따른 의료 투자의 뒷받침을 받아 연평균 성장률(CAGR) 6.47%의 성장이 예상됩니다. 이러한 재정적 지원에 힘입어 각 정형외과용 의료기기 제조업체들은 리야드에 거점을 설립하는 움직임을 보이고 있으며, 민관 파트너십을 통해 고품질 HA 임플란트 도입에 적극적인 신규 병원 건설이 진행되고 있습니다. 남미에서는 환율 변동에 직면해 있지만, 특히 상환 모델이 안정화된다면 브라질의 방대한 인구가 잠재적 시장이 될 것으로 전망됩니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the hydroxyapatite market size is projected to be USD 2.73 billion in 2025, USD 2.9 billion in 2026, and reach USD 3.96 billion by 2031, growing at a CAGR of 6.39% from 2026 to 2031.
This report is Segmented by Particle Size (Nano-Sized, Micro-Sized, and Macro-Sized), Source (Synthetic and Bio-Derived), Form (Powder, Granules, and Coatings and Pastes), Application (Dental Care, Orthopedics, Plastic and Cosmetic Surgery, and Other Industrial Uses), and Geography (Asia-Pacific, North America, Europe, and More). Market Forecasts are Provided in Terms of Value (USD).
Global Hydroxyapatite Market Trends and Insights
Dental-Implant Boom in Aging Economies
By 2027, over one-fifth of residents in Japan, Germany, and Italy will be aged 65 and older, spurring a demand for tooth replacements that leans towards HA-coated fixtures instead of removable dentures. Clinical studies indicate that HA-coated posts reduce healing time compared to their uncoated titanium counterparts. This advantage helps maintain their premium pricing in markets backed by reimbursements. Dental-device companies are now aiming for comparable success with mandibular implants. In April 2025, Japan expanded its insurance coverage for HA-coated dental fixtures, projecting an addition of procedures annually starting in 2028. Proactive clinics are now integrating HA coatings with digital dentistry processes, leading to reduced chair time and increased patient turnover. These trends bolster the Hydroxyapatite market, ensuring steady demand in affluent economies.
Orthopedic Implant Volume Growth
In 2025, the global count for hip and knee arthroplasties saw significant growth, with revisions constituting a notable portion of the total. Surgeons are increasingly opting for HA-integrated cages in spinal fusions, steering clear of iliac crest autografts. This choice not only slashes operating time by nearly 40 minutes but also diminishes the risk of infections. Injectable HA-collagen putties, such as moldable scaffolds for posterolateral fusion, have gained clinical trust. The Asia-Pacific region witnessed substantial growth in orthopedic device revenue, largely driven by a rise in elective procedures in China and India. This consistent growth in surgical volumes, paired with payers' growing acceptance of premium coatings, propels the Hydroxyapatite market forward.
High Implant Procedure Cost and Regulatory Hurdles
In the U.S., single-tooth implants are expensive. Adding HA coatings further increases the component cost. This pricing structure often sidelines many Medicare beneficiaries, as routine dental care isn't federally covered. In orthopedics, revisions using HA grafts can significantly inflate hospital bills. Private insurers, however, closely monitor these costs, especially under bundled-payment models that target 90-day readmissions. Manufacturers face a hefty price tag for each 510(k) submission. This cost covers mechanical tests, biocompatibility panels, and sterility validations. Europe's MDR has extended CE-mark timelines, pushing back cash flows from product launches. These factors, combined with high surgical costs and extensive regulatory requirements, are dampening the short-term growth of the Hydroxyapatite market.
Other drivers and restraints analyzed in the detailed report include:
- Biocompatibility Advantage Over Metallic Substitutes
- 3D Printing Enabling Patient-Specific HA Implants
- Toxicology Debate on Nano-Hydroxyapatite
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Nano-sized powders are on track for a 7.09% CAGR through 2031, outpacing the average growth of the Hydroxyapatite market. This accelerated growth is attributed to their surface area, which enhances protein adsorption within just 48 hours. Periodontal surgeons utilize these powders in guided-tissue membranes, ensuring a bony fill instead of a fibrotic repair. Micro-sized grades, still dominant with 47.65% hydroxyapatite market share in 2025. Their packing densities enable them to achieve a compressive strength, making them ideal for hip stems and spinal cages.
Wet-precipitation plants, optimized for micro-powders, face challenges in maintaining nucleation. This limitation drives suppliers to invest in more expensive sol-gel or hydrothermal reactors. While ISO 13779-3 provides guidelines on particle-size assays, it falls short on performance thresholds, leaving buyers to establish their own specifications. Notably, nano-HA derived from Japanese scallop shells demonstrates impressive antimicrobial efficacy against Streptococcus mutans, suggesting its potential dual role in promoting bone growth and combating bacteria. Although the EU has imposed cosmetic caps, these regulations haven't yet extended to implants. However, ongoing studies on chronic inhalation could influence future regulations. As a result, there's a pronounced trend of adoption in specialized surgical channels, with expectations of a broader rollout in mainstream dental applications.
Synthetic production claimed 71.85% of 2025 volume, reflecting the stringent control over the Ca/P ratio, all under the watchful eye of ISO 13485 quality systems. The wet precipitation method, operating between 60-90 °C, adeptly transforms calcium nitrate and diammonium phosphate. The resulting commodity grades are priced at FOB China. Meanwhile, sol-gel batches, boasting higher purity, cater to craniofacial markets where radiographic clarity is paramount.
Bio-derived hydroxyapatite is growing at a 6.83% CAGR. This growth is largely attributed to mandates promoting a circular economy and the osteogenic advantages of trace strontium and magnesium, both sourced from marine feeds. When calcined between 900-1,000 °C, eggshell waste produces a porous form of HA. On the other hand, coral-based variants, while boasting interconnected channels that expedite vascular ingrowth, grapple with supply constraints due to CITES regulations. Shell Apatite, a powder derived from Japanese scallops, made its debut in local dental clinics in 2025 and is now pursuing CE certification. However, the variability in mineral trace elements poses challenges in lot release, prompting innovators to turn to blockchain-style provenance logs for solutions. In summary, as sustainability credentials gain prominence, bio-routes are transitioning from being mere novelties to becoming foundational pillars in the Hydroxyapatite market.
Complete Report Scope:
- By Particle Size
- Nano-sized
- Micro-sized
- Macro-sized (greater than 1 µm)
- By Source
- Synthetic (wet, sol-gel, hydrothermal)
- Bio-derived (egg-shell, coral, bovine, fish-scale)
- By Form
- Powder
- Granules
- Coatings and Pastes
- By Application
- Dental Care
- Orthopedics
- Plastic and Cosmetic Surgery
- Other Industrial Uses (catalysts, chromatography, water-treatment)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific contributed 39.25% of the 2025 share of global sales. China's wet-precipitation capacity offers commodity powders at prices significantly lower than their Western counterparts, making inroads into budget-conscious clinics in Southeast Asia. An insurance expansion in April 2025 for HA-coated dental implants in Japan is set to boost annual cases, benefiting domestic sol-gel suppliers like Matsumoto Koshou. In 2025, South Korea's regulators doubled the approvals for 3D-printed HA implants, showcasing their confidence in additive manufacturing. Meanwhile, India, despite witnessing growth in orthopedic devices in 2025, continues to prefer autografts in public hospitals, posing a challenge for HA vendors.
North America sees steady mid-single-digit growth, driven by innovations like patient-specific 3D prints, HA-collagen putties, and CaHA dermal fillers. Zimmer Biomet's FDA-approved Oxford knee has set a new standard for coating durability, pushing competitors to enhance their offerings. While CMS's exclusion of routine dental implants limits their adoption among seniors, pilot bundled-payments might pave the way for reimbursing HA-coated fixtures, provided they maintain a complication rate within 90 days. In Canada, urban private clinics lean towards premium HA products, but rural hospitals often stick to uncoated metals, highlighting a divide in the provincial healthcare system. Mexico's push for near-shoring saw two multinationals establish HA-coating facilities in Monterrey in 2025.
Europe grapples with extended approvals under MDR 2017/745, yet its emphasis on biocompatibility resonates with HA's inherent advantages. High arthroplasty rates in Germany, the UK, and France account for a significant portion of Europe's HA demand. The Middle East and Africa, buoyed by Saudi Vision 2030's healthcare investment, is witnessing 6.47% CAGR growth. This financial push is motivating orthopedic OEMs to establish hubs in Riyadh, with public-private partnerships facilitating the creation of new hospitals that are keen on premium HA implants. South America, despite grappling with currency fluctuations, sees Brazil's sizable population as a potential market, especially once reimbursement models find stability.
- Berkeley Advanced Biomaterials
- Bio-Rad Laboratories
- CAM Bioceramics
- Cerabone (Botiss)
- CGbio
- Clarion Pharmaceutical Co.
- Fluidinova
- Hoya Technosurgical Corporation (HOYA Corporation)
- KYOCERA Corporation
- Medtronic
- Merz North America Inc. (Merz Biomaterials)
- Regenity
- Reneuco Berhad (Granulab Malaysia SDN.BHD)
- SANGI Co. Ltd
- SigmaGraft Biomaterials
- Taihei Chemical Industrial Co. Ltd
- Tomita Pharmaceutical Co. Ltd
- Zimmer Biomet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Dental-implant boom in ageing economies
- 4.2.2 Orthopedic implant volume growth
- 4.2.3 Biocompatibility advantage over metallic substitutes
- 4.2.4 Government push for safer biomaterials
- 4.2.5 3-D printing enabling patient-specific HA implants
- 4.3 Market Restraints
- 4.3.1 High implant procedure cost
- 4.3.2 Stringent FDA and CE approvals
- 4.3.3 Toxicology debate on nano-HAp in oral-care cosmetics
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Particle Size
- 5.1.1 Nano-sized
- 5.1.2 Micro-sized
- 5.1.3 Macro-sized (greater than 1 µm)
- 5.2 By Source
- 5.2.1 Synthetic (wet, sol-gel, hydrothermal)
- 5.2.2 Bio-derived (egg-shell, coral, bovine, fish-scale)
- 5.3 By Form
- 5.3.1 Powder
- 5.3.2 Granules
- 5.3.3 Coatings and Pastes
- 5.4 By Application
- 5.4.1 Dental Care
- 5.4.2 Orthopedics
- 5.4.3 Plastic and Cosmetic Surgery
- 5.4.4 Other Industrial Uses (catalysts, chromatography, water-treatment)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Berkeley Advanced Biomaterials
- 6.4.2 Bio-Rad Laboratories
- 6.4.3 CAM Bioceramics
- 6.4.4 Cerabone (Botiss)
- 6.4.5 CGbio
- 6.4.6 Clarion Pharmaceutical Co.
- 6.4.7 Fluidinova
- 6.4.8 Hoya Technosurgical Corporation (HOYA Corporation)
- 6.4.9 KYOCERA Corporation
- 6.4.10 Medtronic
- 6.4.11 Merz North America Inc. (Merz Biomaterials)
- 6.4.12 Regenity
- 6.4.13 Reneuco Berhad (Granulab Malaysia SDN.BHD)
- 6.4.14 SANGI Co. Ltd
- 6.4.15 SigmaGraft Biomaterials
- 6.4.16 Taihei Chemical Industrial Co. Ltd
- 6.4.17 Tomita Pharmaceutical Co. Ltd
- 6.4.18 Zimmer Biomet
7 Market Opportunities and Future Outlook
- 7.1 White-space and unmet-need assessment


