

|
시장보고서
상품코드
2124355
아스팔트 포장기 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Asphalt Pavers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
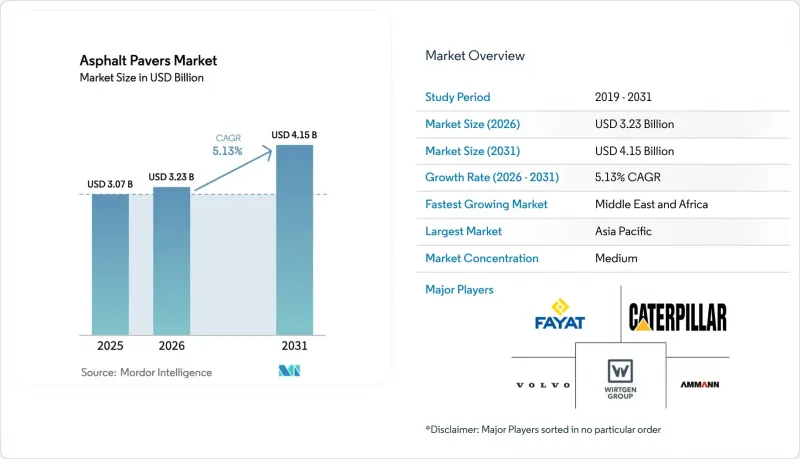
에 의하면, 아스팔트 포장기 시장 규모는 2025년 30억 7,000만 달러로 평가되었고, 2026년에는 32억 3,000만 달러로 추정되고, 2026-2031년 CAGR 5.13%로 성장을 지속할 전망이며, 2031년까지 41억 5,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 유형별(크롤러식 포장기, 휠식 포장기 등), 포장 폭별별(1.5m 미만, 1.5-2m, 3m 이상), 용도별(고속도로 및 주요 도로, 도시 도로 및 시가지 도로 등), 최종 사용자별(정부 및 공공기관, 민간 건설 도급업체 등), 지역별(북미 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(대수)의 관점에서 제시되어 있습니다.
세계의 아스팔트 포장기 시장 동향 및 인사이트
아시아태평양의 도로 건설 및 도시화 급증
급속한 도시화로 인해 아시아태평양에서는 고속도로 및 시도로 건설 프로젝트가 잇따르고 있습니다. 중국 광둥성에서는 2025년까지 12,000km의 신규 고속도로를 완공할 계획이며, 인도는 2027년까지 17,000km의 도로 개량을 목표로 하고 있어, 이에 따라 크롤러식 기계의 수주 잔고는 향후 수년 동안 확보될 전망입니다. ‘일대일로’의 자금 지원에 힘입어 인도네시아와 베트남에서는 간선 도로 입찰이 지원되고 있으며, 2025년에는 각각 50억 달러를 넘는 규모가 될 전망입니다. 한편, 인도의 지방 도시에서는 인근 도로 공사를 위해 소형 포장 기계가 도입되고 있습니다. 아시아개발은행(ADB)의 추산에 따르면, 아시아 개발도상국에서는 2030년까지 연간 1조 7,000억 달러의 인프라 투자가 필요할 것으로 예상되며, 이에 따라 아스팔트 포장기 시장은 절대적인 대수 성장 측면에서 유럽 및 미국 지역을 앞지를 것으로 확실시되고 있습니다.
북미의 인프라 자금 조달 가속화
미국의 ‘인프라 투자 및 고용법’에서는 도로 및 교량에 1,100억 달러가 배정되어 있으며, 2025년 중반까지 자금의 약 76%를 이미 지출해야 합니다. 각 주 교통국은 예방적 유지보수를 중시하고 있어, 얇은 층 오버레이용 스크리드 및 스프레이 본딩식 포장기 수요가 증가하고 있습니다. 캐나다의 ‘Investing in Canada’ 프로그램에서는 대중교통, 그린 인프라, 사회 인프라에 335억 캐나다 달러가 투입되고 있으며, 한랭지용 패키지를 갖춘 크롤러식 포장기로의 사양 전환이 진행되고 있습니다. 웜 믹스 아스팔트의 의무화로 인해 10℃라는 낮은 기온에서도 포장이 가능해졌으며, 작업 기간이 4-6주 연장되어 연간 기계 가동률이 향상되고 있습니다.
첨단 포장기의 막대한 초기 투자 및 유지관리 비용
텔레매틱스 기능을 탑재한 크롤러식 포장기는 45만-65만 달러의 가격대에 있어, 많은 소규모 도급업체에게는 구입이 어려운 가격입니다. 센서군, 유압 시스템, 임베디드 소프트웨어에는 OEM 인증 서비스 제공업체가 필요하기 때문에 유지보수 요건이 더욱 복잡해지고 있지만, 지방에서는 이러한 서비스 제공업체를 찾기가 드뭅니다. 수입 관세와 금융 접근 제한으로 인해 신흥국의 총 소유 비용은 더욱 상승하고 있으며, 구매자들은 고급 전자 장비가 탑재되지 않은 기본 모델로 눈을 돌리고 있습니다. 중국 브랜드는 기능을 축소한 기계를 대폭 할인된 가격에 제공하고 있지만, 기술적 격차로 인해 규제가 엄격한 시장에서의 매력은 줄어들고 있습니다.
부문 분석
2025년 매출액 중 크롤러식 포장 기계가 56.36%를 차지했으며, 연약한 노반이나 급경사에서의 주행 성능에 대한 시공업체의 신뢰도가 높음을 알 수 있습니다. 도시 지역의 노면 재포장에서는 신속한 이동으로 인해 유휴 시간을 단축할 수 있기 때문에 휠식이 여전히 선호되고 있습니다. 그러나 크롤러식 모델에 고속 주행 모드가 추가됨에 따라 그 시장 점유율은 축소되는 추세입니다. 스크리드 부문은 2031년까지 연평균 성장률(CAGR)이 6.88%로 두드러지게 나타나며, 얇은 층 오버레이 및 접착식 마모층을 중시하는 포장 유지보수 예산에 힘입고 있습니다. 미국 각 주의 유지 관리 지출로 인해 2025년 고속도로 자금의 상당 부분이 예방적 유지 관리에 할당되면서, 신축식 스크리드의 수주가 증가했습니다. 이러한 수요로 인해 온도 변동에 따라 탬퍼의 진동 빈도를 자동으로 보정하는 지능형 스크리드의 매력이 높아졌습니다.
2025년에는 전동식 크롤러형 포장기가 등장하여 야간 포장 시 소음 저감 및 인구 밀집 도시의 제로 배출 규제 준수가 기대되고 있습니다. 이에 대응하여 휠식 포장기는 경쟁력을 유지하기 위해 선회 반경 축소 및 반자율 주행 기능 도입을 추진하고 있습니다. 스크리드 공급업체들은 현재 포장층의 밀도와 온도를 측정하는 센서를 탑재하고 있으며, 프로젝트 소유주에게 감사 대응이 가능한 보고서를 제공하는 동시에 애프터서비스용 소프트웨어의 수익을 확대되고 있습니다. 기종 카테고리의 융합은 볼트온식 모듈을 통해 고속도로, 일반 도로, 오버레이 공사 등 각 업무를 전환할 수 있는 다기능 플랫폼의 등장을 예고하고 있습니다.
표준 폭 2.4-2.55m 기종은 2025년 매출의 35.87%를 차지했으며, 대부분의 지역에서 단일 차선 고속도로 사양에 부합합니다. 그러나 공항 활주로나 다차선 고속도로에서는 더 빠른 포장 작업과 콜드 조인트(cold joint) 감소가 요구되기 때문에 폭 2.55m를 초과하는 기종은 연평균 성장률(CAGR) 7.58%로 성장하고 있습니다. 중국에서는 향후 자율주행 트럭 도입을 위한 3.75m의 차선 폭 요건으로 인해 더 넓은 스크리드가 요구되고 있으며, 한 번에 2개 차선을 시공할 수 있는 모델이 개발되고 있습니다. 1.5m 미만의 소형 기종은 자전거 도로나 보행자 전용 구역을 담당하며, 자동차 통행 금지 구역을 확대하는 유럽의 도시 계획의 혜택을 받고 있습니다.
공항 입찰에서는 항공사의 지연 비용이 시간당 5만-10만 달러에 달한다는 점이 끊임없이 지적되어 왔으며, 이는 끊임없는 처리 능력을 갖춘 광폭 포장 기계에 대한 투자를 정당화하는 근거가 되고 있습니다. 유럽의 OEM 업체들은 이 기회를 활용하여 2025년에는 주력 기종이 프랑크푸르트와 암스테르담에서 주목받는 활주로 공사를 수주했습니다. 자카르타나 호치민시의 좁은 도심 골목길에서는 1.5m 미만의 포장 기계에 대한 수요가 증가하고 있으며, 아시아 제조업체들은 경량 고무 트랙을 채택한 설계로 이 절호 시장을 활용하고 있습니다. 구매자들은 현재 정가가 아닌 프로젝트 전체의 경제성을 기준으로 기종 카테고리를 평가하고 있으며, 용도의 긴급도에 따라 수요가 더욱 세분화되고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 37.92%를 차지했으며, 인도의 ‘바라트마라’ 고속도로 계획과 중국의 지방 고속도로를 견인력으로 삼아 연평균 성장률(CAGR) 5.09%로 확대되고 있습니다. 중동 및 아프리카는 절대적인 규모로는 작지만, 석유 자금을 활용한 국가 계획이 다차선 간선 도로나 공항 확장에 자금을 공급하고 있어 2031년까지 연평균 성장률(CAGR) 6.57%로 성장을 가속화할 전망입니다. 사우디아라비아는 ‘비전 2030’의 일환으로 교통 인프라에 400억 달러를 배정하고 있으며, UAE는 자율주행차 실증 실험을 지원하기 위해 2,500km에 달하는 연방 고속도로의 현대화를 추진하고 있습니다. ‘일대일로’의 틀에서 자금이 지원되는 사하라 이남 아프리카 프로젝트에서는 저비용의 중국산 포장 기계가 선호되지만, 텔레매틱스 및 배기가스 규제에 대한 대응에서 나타나는 기술 격차로 인해 북미 및 EU 입찰 시장 진출은 제한적인 상황입니다.
북미에서는 지속적인 연방 예산 배분과 웜믹스 아스팔트 및 스프레이 오버레이용 장비가 필요한 주 차원의 기후 변화 적응 프로그램 덕분에 연평균 성장률(CAGR)이 3.15%로 성장을 지속하고 있습니다. 유럽에서는 재정적 제약이 신규 건설에 큰 부담으로 작용하고 있어 연평균 성장률(CAGR)은 2.88%로 소폭에 그치고 있지만, ‘유럽 그린딜’에 따라 지자체들은 야간 작업용 전기 포장기 도입을 추진하고 있습니다. 남미의 2.01%라는 성장률은 환율 변동과 공공 부채의 부담을 반영하고 있지만, 전기차 충전 회랑과 연계된 브라질의 ‘Rota 2030’ 도로 개선 계획이 중기적인 호재로 작용하고 있습니다. 오세아니아는 뉴질랜드의 내진 보강 및 호주의 단계적 인프라 계획에 힘입어 연평균 성장률(CAGR)이 2.89%로 성장을 지속하고, 있습니다.
규제의 차이가 제품 사양을 형성하고 있습니다. EU의 스테이지 V 엔진 규제는 단가를 끌어올리지만, 프리미엄 OEM 제조업체를 보호하는 규정 준수 측면의 진입 장벽을 만들어내고 있습니다. 중동의 구매자들은 사막 기후를 견딜 수 있는 내열성과 방진 기능을 요구합니다. 2024년에 도입된 인도의 IS 16246 규격은 스크리드 가열의 균일성과 다짐 기준을 의무화하고 있어, 저가대 수입품의 유입을 억제하고 있습니다. 이러한 규제의 세분화로 인해 전 세계 제조업체들은 지역별 인증 포트폴리오를 관리할 수밖에 없게 되어, 연구개발비와 재고 보유 비용이 증가하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the asphalt paver market size is expected to grow from USD 3.07 billion in 2025 to USD 3.23 billion in 2026 and is forecast to reach USD 4.15 billion by 2031 at a 5.13% CAGR over 2026-2031.
This report is Segmented by Type (Tracked Pavers, Wheeled Pavers, and More), Paving Range (Less Than 1. 5 M, 1. 5-2. 3 M, and More), Application (Highways and Major Roads, Urban Roads and Streets, and More), End-User (Government and Public Agencies, Private Construction Contractors, and More), and Geography (North America and More). Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Asphalt Pavers Market Trends and Insights
Surge in Road-Building and Urbanization Across APAC
Rapid urbanization is spurring a wave of highway and municipal road projects in the Asia-Pacific. China's Guangdong had plans to complete 12,000 km of new expressways in 2025, and India aims for 17,000 km of upgrades by 2027, guaranteeing multi-year order books for tracked machines. Belt and Road financing is underwriting arterial-road tenders in Indonesia and Vietnam, each exceeding USD 5 billion in 2025, while tier-2 Indian cities are adding compact pavers for neighborhood streets. The Asian Development Bank estimates that developing Asia needs USD 1.7 trillion in annual infrastructure investment through 2030, assuring that the asphalt paver market will outpace Western regions in absolute unit growth.
Accelerated Infrastructure Funding in North America
The U.S. Infrastructure Investment and Jobs Act earmarked USD 110 billion for roads and bridges, with around 76% of the funds already obligated by mid-2025. State transportation departments are emphasizing preventive maintenance, raising demand for thin-overlay screeds and spray-bonded pavers. Canada's Investing in Canada program is injecting CAD 33.5 billion into public transit, green infrastructure, and social infrastructure, guiding specifications toward tracked pavers with cold-weather packages. Warm-mix asphalt mandates enable paving in temperatures as low as 10 °C, adding four to six extra working weeks and lifting annual machine utilization.
High Capital and Maintenance Costs of Advanced Pavers
Telematics-equipped tracked pavers can list between USD 450,000 and USD 650,000, pricing many smaller contractors out of the ownership model. Maintenance needs grow more complex as sensor suites, hydraulics, and embedded software demand OEM-certified service providers, seldom found in rural regions. Import tariffs and limited access to credit further raise the total cost of ownership in emerging economies, pushing buyers toward basic models that skip premium electronics. Chinese brands offer stripped-down machines at a robust discount, but the technology gap narrows their appeal in regulated markets.
Other drivers and restraints analyzed in the detailed report include:
- Integration of Telematics and Grade-Control Boosting ROI
- Warm-Mix Asphalt Adoption Extending Paving Seasons
- Expansion of Equipment Rental Business Model
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tracked pavers captured 56.36% of 2025 revenue, illustrating contractor trust in their traction on soft base layers and steep grades. Wheeled variants remain favored for urban resurfacing because quicker relocation lowers idle time, yet their market share is eroding as tracked models add higher travel-speed modes. The screed segment stands out with a 6.88% CAGR to 2031, propelled by pavement-preservation budgets that emphasize thin overlays and bonded-wearing courses. State maintenance outlays in the United States channeled the majority of 2025 highway funds into preventive treatments, boosting orders for extendable screeds. This demand reinforced the appeal of intelligent screeds that auto-correct tamper frequency for temperature swings.
Electrified tracked machines debuted in 2025, promising quieter night paving and compliance with zero-emission mandates in dense cities. Wheeled pavers have responded with tighter turning radii and semi-autonomous steering to remain relevant. Screed suppliers now integrate sensors that capture mat density and temperature, feeding project owners with audit-ready reports and elevating after-sales software revenue. The convergence of type categories foreshadows multi-role platforms able to toggle between highway, street, and overlay duties through bolt-on modules.
Standard 2.4-2.55 m widths yielded 35.87% of 2025 revenue, matching single-lane highway specifications in most regions. Yet machines above 2.55 m are growing at 7.58% CAGR as airport runways and multi-lane expressways demand faster passes and fewer cold joints. China's 3.75 m lane requirements for future autonomous trucking push even wider screeds, inspiring models that place two lanes in one go. Compact ranges under 1.5 m cover bike paths and pedestrian precincts, benefiting from European city plans that expand car-free zones.
Airport tenders routinely cite airline delay costs of USD 50,000-100,000 per hour, justifying investment in wide pavers capable of relentless throughput. European OEMs have capitalized, with flagship units securing high-profile runway jobs at Frankfurt and Amsterdam during 2025. Narrow urban alleys in Jakarta and Ho Chi Minh City are fueling uptake of sub-1.5 m pavers, a sweet spot that Asian manufacturers are exploiting with lightweight, rubber-track designs. Buyers now evaluate range categories through total project economics rather than sticker price, further segmenting demand by application urgency.
Complete Report Scope:
- By Type
- Tracked Pavers
- Wheeled Pavers
- Screeds
- By Paving Range
- Less than 1.5 m
- 1.5 to 2.3 m
- 2.4 to 2.55 m
- Above 2.55 m
- By Application
- Highways and Major Roads
- Urban Roads and Streets
- Parking Lots and Driveways
- Airport Runways and Taxiways
- By End-User
- Government and Public Agencies
- Private Construction Contractors
- Rental Equipment Companies
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle-East and Africa
- North America
Geography Analysis
Asia-Pacific contributed 37.92% of 2025 revenue and is advancing at a 5.09% CAGR, anchored by India's Bharatmala highway program and provincial expressways in China. Middle East and Africa, though smaller in absolute terms, will accelerate at 6.57% CAGR through 2031 as oil-funded sovereign plans finance multilane corridors and airport expansions. Saudi Arabia earmarked USD 40 billion for transport under Vision 2030, and the UAE is modernizing 2,500 km of federal highways to support autonomous-vehicle pilots. Sub-Saharan African projects financed under Belt and Road terms favor lower-cost Chinese pavers, yet technology gaps in telematics and emission compliance limit penetration in North American and EU tenders.
North America is growing at a 3.15% CAGR thanks to ongoing federal appropriations and state-level climate-resilience programs that call for warm-mix asphalt and spray-overlay gear. Europe registers a modest 2.88% CAGR as fiscal constraints weigh on new build, though the European Green Deal pushes municipalities toward electric pavers for night work. South America's 2.01% rate reflects currency volatility and public-debt overhang, yet Brazil's Rota 2030 road upgrades linked to EV charging corridors provide a mid-term tailwind. Oceania sits at 2.89% CAGR, driven by seismic-resilience retrofits in New Zealand and Australia's rolling infrastructure plan.
Divergent regulation shapes product specifications. The EU's Stage V engine rules raise unit cost but create a compliance moat protecting premium OEMs. Middle Eastern buyers demand high-temperature and dust-filtration features to withstand desert climates. India's IS 16246 standard, introduced in 2024, enforces screed-heating uniformity and compaction thresholds, pruning the influx of low-end imports. Such fragmentation compels global manufacturers to run region-specific certification portfolios, inflating R&D and inventory carrying costs.
- Caterpillar Inc.
- Volvo Construction Equipment AB
- Wirtgen Group
- Fayat Group
- Ammann Group
- Astec Industries Inc.
- XCMG Construction Machinery Co. Ltd.
- SANY Heavy Industry Co. Ltd.
- Komatsu Ltd.
- Zoomlion Heavy Industry Sci-Tech Co. Ltd.
- Sakai Heavy Industries Ltd.
- Shantui Construction Machinery Co. Ltd.
- LeeBoy Inc.
- Sumitomo Construction Machinery Co. Ltd.
- Weiler Inc.
- Mauldin Paving Products
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Road-building and Urbanization Across APAC
- 4.2.2 Accelerated Infrastructure Funding in North America
- 4.2.3 Integration of Telematics and Grade-Control Boosting ROI
- 4.2.4 Warm-Mix Asphalt Adoption Extending Paving Seasons
- 4.2.5 Growing Demand for Compact Pavers in Dense Cities
- 4.2.6 Adoption of Spray-Paver Bonded-Overlay Technology
- 4.3 Market Restraints
- 4.3.1 High Capital and Maintenance Costs of Advanced Pavers
- 4.3.2 Expansion of Equipment Rental Business Model
- 4.3.3 Bitumen-Price Volatility Destabilizing Purchase Cycles
- 4.3.4 Skilled-Operator Shortages for Tech-Intensive Machines
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Type
- 5.1.1 Tracked Pavers
- 5.1.2 Wheeled Pavers
- 5.1.3 Screeds
- 5.2 By Paving Range
- 5.2.1 Less than 1.5 m
- 5.2.2 1.5 to 2.3 m
- 5.2.3 2.4 to 2.55 m
- 5.2.4 Above 2.55 m
- 5.3 By Application
- 5.3.1 Highways and Major Roads
- 5.3.2 Urban Roads and Streets
- 5.3.3 Parking Lots and Driveways
- 5.3.4 Airport Runways and Taxiways
- 5.4 By End-User
- 5.4.1 Government and Public Agencies
- 5.4.2 Private Construction Contractors
- 5.4.3 Rental Equipment Companies
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle-East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 Volvo Construction Equipment AB
- 6.4.3 Wirtgen Group
- 6.4.4 Fayat Group
- 6.4.5 Ammann Group
- 6.4.6 Astec Industries Inc.
- 6.4.7 XCMG Construction Machinery Co. Ltd.
- 6.4.8 SANY Heavy Industry Co. Ltd.
- 6.4.9 Komatsu Ltd.
- 6.4.10 Zoomlion Heavy Industry Sci-Tech Co. Ltd.
- 6.4.11 Sakai Heavy Industries Ltd.
- 6.4.12 Shantui Construction Machinery Co. Ltd.
- 6.4.13 LeeBoy Inc.
- 6.4.14 Sumitomo Construction Machinery Co. Ltd.
- 6.4.15 Weiler Inc.
- 6.4.16 Mauldin Paving Products
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


