

|
시장보고서
상품코드
2124362
최종 사용자 컴퓨팅 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)End User Computing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 최종 사용자 컴퓨팅 시장 규모는 2025년에 131억 7,000만 달러로 평가되었고, 2026년 144억 7,000만 달러에서 2031년까지 232억 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 9.89%를 기록할 전망입니다.
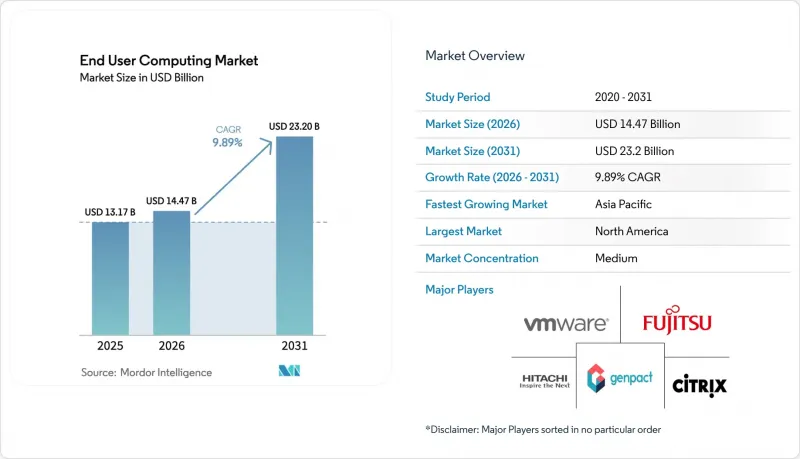
본 보고서는 제품 유형별(가상 데스크톱 인프라 등), 조직 규모별(대기업 등), 도입 형태별(온프레미스, 클라우드, 하이브리드), 최종 사용자 산업별(IT 및 통신, 은행 및 금융 서비스·보험 등), 제공 모델별(가상 데스크톱 인프라 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 최종 사용자 컴퓨팅 시장 동향 및 인사이트
디지털 워크스페이스를 통한 직원 생산성 향상 노력
기업들은 단일 디지털 워크스페이스 내에 가상 데스크톱, 협업 제품군, AI 코파일럿을 통합함으로써 생산성의 개념을 재구성하고 있습니다. 워크플레이스 성숙도가 높은 수준에 도달한 조직에서는 리소스에 대한 신속한 접근, 앱 셀프 서비스, 통합된 보안 제어 덕분에 직원 경험에 대한 긍정적 지표가 57.8% 향상된 것으로 보고되었습니다. 마이크로소프트의 초기 현장 데이터에 따르면, AI 코파일럿은 직원 1인당 매월 약 10시간의 시간을 절약해 주고 있으며, 이는 실질적인 생산성 향상으로 이어지고 있습니다. 그 결과, 기기 간 원활한 전환과 자동화된 워크플로우를 통해 마찰과 번아웃이 완화되어, 혁신, 포용성, 웰빙 측면에서 측정 가능한 개선이 이루어지고 있습니다.
클라우드 기반 데스크톱 및 애플리케이션 가상화 도입 확대
사용량 기반의 데스크톱 호스팅은 자본 투자가 필요 없고 도입 기간을 몇 달에서 며칠로 단축시켜 주기 때문에 빠르게 보급되고 있습니다. Azure Virtual Desktop의 본격적인 운영은 조사 대상 조직의 26%로 이미 확대되었으며, 58%는 향후 2년 이내에 도입을 계획하고 있습니다. 그 배경에는 정책 기반의 확장성,사용량 기반 과금, 그리고 Microsoft 365와의 네이티브 통합이 있습니다. 의료 서비스 제공업체들이 그 이점을 여실히 보여주고 있습니다. 브라우저를 통해 제공되는 데스크톱에서는 로그인에 1분도 걸리지 않아, 임상의들은 IT 관련 대기 시간을 줄이고 환자와 함께 보내는 시간을 더 많이 확보할 수 있게 되었습니다.
EUC와 레거시 용도 및 인프라 통합의 복잡성
은행, 병원, 정부 기관은 여전히 특정 OS 버전에 묶인 두꺼운 클라이언트 용도, 하드코딩된 드라이브 매핑, 또는 시리얼 포트 연결 주변 기기에 의존하고 있습니다. 가상 데스크톱은 이러한 의존성을 재현하면서도 미션 크리티컬한 워크플로우에서 밀리초 단위의 응답 시간을 보장해야 합니다. 그 결과, 통합 프로젝트에는 미들웨어, API, 병렬 테스트 환경이 추가되어 일정이 장기화되고 비용이 증가하게 됩니다. 변경 관리의 미비는 ROI를 더욱 저해합니다. 체계적인 교육을 받지 않고 디지털 워크스페이스로 전환한 직원의 73%는 업무 몰입도가 저하되어 프로젝트가 원점으로 돌아갈 위험이 발생합니다. 기업들은 워크로드를 단계적으로 이전하고, 모놀리식 시스템을 모듈형 서비스로 재구축하며, 도입 과정의 병목 현상을 조기에 파악할 수 있는 사용자 경험 분석을 도입함으로써 이러한 지연을 완화하고 있습니다.
부문 분석
이 솔루션은 2025년 최종 사용자 컴퓨팅 시장에서 60.45%의 점유율을 유지했습니다. 이는 성숙한 VDI 플랫폼, 디바이스 관리 제품군 및 소프트웨어 자산 관리 도구에 의해 뒷받침되었으며, 이들 모두를 합쳐 연간 약 80억 달러의 경상수익을 창출했습니다. 벤더들은 통합 콘솔을 사용하여 엔드포인트, 애플리케이션, 보안을 오케스트레이션하고 있으며, 이를 통해 수천 개에 달하는 자산에 대한 규정 준수 감사가 간소화되고 있습니다. 현재 성장은 매니지드 서비스에 집중되어 있으며, 연평균 성장률(CAGR)은 10.05%로 성장을 지속하고, 있습니다. 이는 기업들이 패치 적용, 확장 및 경험 모니터링을 전문가에게 맡기는 성과 기반 계약을 선호하기 때문입니다.
매니지드 서비스 제공업체는 AI를 활용한 가시성 및 자가 복구 기능을 통합하고 있으며, 이를 통해 고객은 문제 대응형 티켓 처리에서 선제적인 최적화로 전환할 수 있게 됩니다. 예를 들어, 의료 업계의 고객은 ‘Device-as-a-Service(DaaS)’ 번들을 채택하고 있습니다. 이를 통해 자본 지출(Capex)을 예측 가능한 운영 비용(OpEx)으로 전환하고, 36개월마다 갱신되는 주기로 사전 설정된 임상용 워크스테이션을 제공함으로써 헬프데스크 문의 건수를 두 자릿수 비율로 줄이고 있습니다.
2025년, 대기업은 최종 사용자 컴퓨팅 시장 규모의 45.85%를 차지했으며, 수만 명의 사용자를 보호하기 위해 맞춤형 통합, 제로 트러스트 오버레이 및 세계 연합 ID에 의존하고 있습니다. 동시 라이선싱과 사내 전문 인력을 통해 사용자당 운영 비용은 낮아지고 있지만, 하드웨어 교체 요건과 AI 업그레이드 주기로 인해 지속적인 재투자가 불가피합니다.
반면, 중소기업은 클라우드 네이티브 데스크톱을 통해 데이터센터 공간이나 전문 인력이 더 이상 필요하지 않게 되어 연평균 성장률(CAGR) 10.25%로 성장하고 있습니다. 브라우저에서 실행되는 워크스페이스는 48시간 이내에 배포할 수 있으며, 자동 확장, 백업, 규정 준수 템플릿을 갖추고 있습니다. 많은 중소기업에게 Windows 10 지원 종료는 하드웨어 지출을 피하고 Windows 11 지원 환경에 즉시 액세스할 수 있는 클라우드 데스크톱으로 직접 전환하는 계기가 되고 있습니다.
지역별 분석
아시아태평양은 2025년에 최종 사용자 컴퓨팅 시장의 62.40%를 차지한 것으로 평가되었으며, 2026-2031년 지역 전체적으로 연평균 성장률(CAGR) 10.72%를 나타낼 것으로 예측됩니다. Zoho의 조사에 따르면, 아시아태평양의 조직은 디지털 워크플레이스 성숙도 점수에서 66.35%를 달성하여 세계 평균보다 5포인트 높은 수치를 기록했으며, 76%가 ‘고급’ 수준에 도달했습니다. AI 지원 도구(54%) 및 팀 채팅(72%)의 보급률은 ‘모바일 우선’ 사고방식을 여실히 보여주고 있으며, 꾸준한 5G 확산은 엣지 강화형 가상 데스크톱에 유리한 환경을 조성하고 있습니다.
북미에서는 규제 대상 산업에서 VDI 환경이 정착되어 있으며, 사용자 1인당 월 약 10시간의 업무 시간을 절감해 주는 AI 코파일럿의 조기 도입을 주도하고 있습니다. Windows 10 지원 종료에 따라, 최신 엔드포인트 관리 및 DaaS를 중시하는 즉각적인 리프레시 물결이 찾아오고 있습니다. 유럽도 유사한 경향을 보이고 있지만, 엄격한 GDPR(EU 개인정보보호규정) 요건이 더해지면서 다국적 기업들은 현지 데이터 보존과 세계 클라우드의 규모를 양립시키는 하이브리드 구축으로 나아가고 있습니다.
중동 및 아프리카, 라틴아메리카의 신흥 시장에서는 클라우드 데스크톱이 레거시 인프라를 뛰어넘을 수 있는 호기로 인식되고 있습니다. 이용 모델은 예산 제약에 맞추어 조정되고 있으며, 통신 사업자와의 엣지 연동을 통해 몰입형 현장 유지보수 및 원격 지원 시나리오에서 20밀리초 미만의 지연 시간이 실현될 전망입니다. 각국 정부는 데이터 현지화 규정을 법적으로 제정하고 있으며, 세계 플랫폼과 상호 연결 가능한 지역 클라우드 존 및 주권형 VDI 스택을 촉진하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 상황 개요
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the end-User computing market size was valued at USD 13.17 billion in 2025 and estimated to grow from USD 14.47 billion in 2026 to reach USD 23.2 billion by 2031, at a CAGR of 9.89% during the forecast period (2026-2031).
This report is Segmented by Product Type( Virtual Desktop Infrastructure, and More), Organization Size (Large Enterprises, and More), Deployment Mode (On-Premise, Cloud, Hybrid), End User Industry (IT and Telecom, Banking Financial Services and Insurance, and More), Delivery Model (Virtual Desktop Infrastructure, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global End User Computing Market Trends and Insights
Drive to Increase Employee Productivity via Digital Workspaces
Enterprises are reimagining productivity by combining virtual desktops, collaboration suites, and AI copilots inside a single digital workspace. Organizations that reach advanced workplace maturity levels report a 57.8% boost in positive employee experience metrics, thanks to quicker access to resources, app self-service, and uniform security controls. Microsoft's early field data shows AI copilots save roughly 10 hours per employee each month, translating into tangible capacity gains. The result is a measurable uplift in innovation, inclusion, and well-being, as seamless device hopping and automated workflows reduce friction and burnout.
Growing Adoption of Cloud-Based Desktop and Application Virtualization
Consumption-based desktop hosting is scaling fast because it eliminates capital expenditure and shortens deployment timelines from months to days. Azure Virtual Desktop production use already spans 26% of surveyed organizations, with 58% planning rollouts within the next two years, driven by policy-based scaling, pay-as-you-go pricing, and native Microsoft 365 integration. Healthcare providers illustrate the upside: browser-delivered desktops logged sub-minute sign-ins, freeing clinicians to spend more time with patients and less on IT wait states.
Complexity Integrating EUC with Legacy Applications and Infrastructure
Banks, hospitals, and government agencies still depend on thick-client applications tied to specific OS versions, hard-coded drive mappings, or serial-port peripherals. Virtual desktops must replicate these dependencies while guaranteeing millisecond response times in mission-critical workflows. Integration projects therefore add middleware, APIs, and parallel test environments, extending timelines and inflating costs. Change-management gaps further undermine ROI; 73% of employees who move to digital workspaces without structured training feel disengaged, risking project rollback. Firms mitigate the drag by phasing workloads, rewriting monoliths into modular services, and introducing user-experience analytics that flag adoption bottlenecks early.
Other drivers and restraints analyzed in the detailed report include:
- Rising BYOD Policies and Mobile Workforce Requiring Unified Endpoint Management
- Windows-10 End-of-Support Triggering Enterprise PC Refresh Cycles
- High Upfront Transformation Costs for VDI and DaaS Migrations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions retained 60.45% End User Computing market share in 2025, underpinned by mature VDI platforms, device-management suites, and software-asset tools that together generated roughly USD 8 billion in annual recurring revenue. Vendors use unified consoles to orchestrate endpoints, apps, and security, which simplifies compliance audits across thousands of assets. Growth now skews toward managed services, with a 10.05% CAGR, as enterprises prefer outcome-based contracts that offload patching, scaling, and experience monitoring to specialists.
Managed service providers embed AI-driven observability and self-healing capabilities, enabling customers to transition from firefighting tickets to proactive optimization. Healthcare customers, for instance, adopt Device-as-a-Service bundles that convert capex to predictable opex and deliver pre-configured clinical workstations on 36-month refresh cycles, reducing help-desk volumes by double-digit percentages.
Large enterprises controlled 45.85% of End User Computing market size in 2025 and rely on tailored integrations, zero-trust overlays, and global federated identity to secure tens of thousands of users. Concurrent licensing and in-house talent give them lower per-seat operating costs, yet hardware refresh mandates and AI upgrade cycles force continual reinvestment.
SMEs, conversely, expand at 10.25% CAGR because cloud-native desktops remove the need for data-center space or specialized staff. Browser-launched workspaces deploy in under 48 hours and include automatic scaling, backup, and compliance templates. For many SMEs the Windows 10 sunset is a trigger to jump straight to cloud desktops, avoiding hardware outlays and accessing Windows 11-ready environments instantly.
Complete Report Scope:
- By Product Type
- Solutions
- Virtual Desktop Infrastructure
- Device Management
- Unified Communication
- Software Asset Management
- Services
- Solutions
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises
- By Deployment Mode
- On-Premise
- Cloud
- Hybrid
- By End User Industry
- IT and Telecom
- Banking, Financial Services and Insurance
- Healthcare
- Retail
- Government
- Education
- Transportation and Logistics
- By Delivery Model
- Virtual Desktop Infrastructure
- Desktop-as-a-Service
- Cloud Workspaces
- Enterprise Mobility Management
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Southeast Asia
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Rest of Africa
- North America
Geography Analysis
The Asia Pacific controlled 62.40% of the End-User Computing market in 2025 and is projected to post a regional 10.72% CAGR from 2026 to 2031. A Zoho survey reveals that APAC organizations have achieved a 66.35% digital workplace maturity score, five points above the global average, with 76% reaching advanced levels. Penetration of AI-enabled tools (54%) and team chat (72%) epitomizes a mobile-first mentality, while steady 5G rollouts create fertile ground for edge-enhanced virtual desktops.
North America exhibits entrenched VDI estates across regulated sectors and leads the early adoption of AI copilots, which save roughly 10 hours per user per month. The Windows 10 cutoff brings an immediate refresh wave that favors modern endpoint management and DaaS. Europe mirrors the pattern but adds stringent GDPR mandates, steering multinationals toward hybrid deployments that balance local data residency with global cloud scale.
Emerging markets in the Middle East, Africa, and Latin America treat cloud desktops as a leapfrog opportunity to bypass legacy infrastructure. Consumption models align with budget constraints, while telco-edge collaborations promise sub-20-millisecond latency for immersive field maintenance or remote-assistance scenarios. Governments increasingly codify data-localization rules, encouraging regional cloud zones and sovereign VDI stacks that can interconnect with global platforms.
- Omnissa (VMware EUC)
- Citrix Systems Inc.
- Microsoft Corporation
- Amazon Web Services Inc.
- Dell Technologies Inc.
- Lenovo Group Ltd.
- HP Inc.
- Nutanix Inc.
- Fujitsu Ltd.
- Genpact Ltd.
- HCL Infosystems Ltd.
- Infosys Ltd.
- LTIMindtree Ltd.
- NetApp Inc.
- Tech Mahindra Ltd.
- Hitachi
- IGEL Technology GmbH
- Parallels International GmbH
- Nerdio Inc.
- ControlUp Inc.
- Cisco Systems Inc.
- Google LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDCSAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Drive to Increase Employee Productivity via Digital Workspaces
- 4.2.2 Growing Adoption of Cloud-Based Desktop and Application Virtualization
- 4.2.3 Rising BYOD Policies and Mobile Workforce Requiring Unified Endpoint Management
- 4.2.4 Windows-10 End-of-Support Triggering Enterprise PC Refresh Cycles
- 4.2.5 Emergence of AI-Capable Endpoints Enabling On-Device GenAI Workloads
- 4.2.6 Telco Edge-Cloud Partnerships Enabling Ultra-Low-Latency EUC for Field AR-VR
- 4.3 Market Restraints
- 4.3.1 Complexity Integrating EUC with Legacy Applications and Infrastructure
- 4.3.2 High Upfront Transformation Costs for VDI and DaaS Migrations
- 4.3.3 Vendor Consolidation-Driven License Uncertainty (e.g., VMware EUC Divestiture)
- 4.3.4 Data Sovereignty Concerns Hindering Full Cloud EUC Adoption
- 4.4 Impact of Macroeconomic Factors
- 4.5 Industry Value / Supply-Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Solutions
- 5.1.1.1 Virtual Desktop Infrastructure
- 5.1.1.2 Device Management
- 5.1.1.3 Unified Communication
- 5.1.1.4 Software Asset Management
- 5.1.2 Services
- 5.1.1 Solutions
- 5.2 By Organization Size
- 5.2.1 Large Enterprises
- 5.2.2 Small and Medium Enterprises
- 5.3 By Deployment Mode
- 5.3.1 On-Premise
- 5.3.2 Cloud
- 5.3.3 Hybrid
- 5.4 By End User Industry
- 5.4.1 IT and Telecom
- 5.4.2 Banking, Financial Services and Insurance
- 5.4.3 Healthcare
- 5.4.4 Retail
- 5.4.5 Government
- 5.4.6 Education
- 5.4.7 Transportation and Logistics
- 5.5 By Delivery Model
- 5.5.1 Virtual Desktop Infrastructure
- 5.5.2 Desktop-as-a-Service
- 5.5.3 Cloud Workspaces
- 5.5.4 Enterprise Mobility Management
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Southeast Asia
- 5.6.4.6 Rest of Asia Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 North Africa
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Omnissa (VMware EUC)
- 6.4.2 Citrix Systems Inc.
- 6.4.3 Microsoft Corporation
- 6.4.4 Amazon Web Services Inc.
- 6.4.5 Dell Technologies Inc.
- 6.4.6 Lenovo Group Ltd.
- 6.4.7 HP Inc.
- 6.4.8 Nutanix Inc.
- 6.4.9 Fujitsu Ltd.
- 6.4.10 Genpact Ltd.
- 6.4.11 HCL Infosystems Ltd.
- 6.4.12 Infosys Ltd.
- 6.4.13 LTIMindtree Ltd.
- 6.4.14 NetApp Inc.
- 6.4.15 Tech Mahindra Ltd.
- 6.4.16 Hitachi
- 6.4.17 IGEL Technology GmbH
- 6.4.18 Parallels International GmbH
- 6.4.19 Nerdio Inc.
- 6.4.20 ControlUp Inc.
- 6.4.21 Cisco Systems Inc.
- 6.4.22 Google LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


