|
시장보고서
상품코드
2124368
지오마케팅 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Geomarketing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
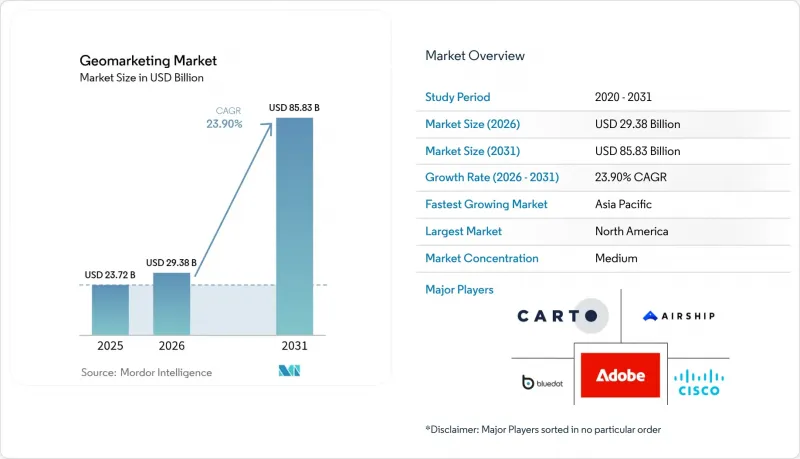
에 의하면, 2026년 지오마케팅 시장 규모는 293억 8,000만 달러로 추정되며, 2025년 237억 2,000만 달러에서 2031년에는 858억 3,000만 달러에 달할 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 23.9%를 기록할 전망입니다.
본 보고서는 구성 요소별(소프트웨어 및 서비스), 도입 형태별(클라우드 및 온프레미스), 장소별(실내 및 실외), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), IT 및 통신, 기타), 조직 규모별(대기업 및 중소기업), 기술별(GPS/휴대폰, BLE 비콘 등), 솔루션 유형별(매핑 및 지오코딩, 위치 정보 분석 및 시각화 등) 그리고 지역별로 분류되어 있습니다.
세계의 지오마케팅 시장 동향 및 인사이트
AI를 활용한 위치 기반 광고의 하이퍼 퍼소나라이제이션
실시간 머신러닝 모델을 통해 개인의 이동 패턴, 체류 시간, 선호하는 장소에 맞추어 광고 크리에이티브를 최적화할 수 있게 되어, 소매업체는 기존의 지오타겟팅 기법에 비해 광고 비용 효율을 최대 40%까지 향상시킬 수 있게 되었습니다. 도착 시간 예측을 통해 주문 이행의 격차가 줄어드는 한편, 컴퓨터 비전 기술을 통해 매장 방문객 수와 인구통계학적 인사이트가 연계되고 있습니다. 이는 Aura Vision이 Flannels에서 전환율을 향상시켜 4.5배의 ROI를 달성한 사례에서도 분명하게 드러납니다. 이러한 기능 덕분에 개인화된 고객 참여는 ‘선택 사항’에서 ‘필수 요소’로 승격되었으며, 지오마케팅 시장은 강력한 성장 궤도를 유지하고 있습니다.
5G의 확산으로 실내 정확도 향상
3GPP Release 18에서 도입된 캐리어 위상 측정을 통해 1미터 미만의 정확도가 실현되어, 과거 GPS가 작동하지 않았던 공항, 쇼핑몰, 공장 등에서도 지오마케팅이 가능해졌습니다. 기업들은 자산의 자동 추적을 통해 15-20%의 생산성 향상을 달성했다고 보고하고 있지만, mm파(mmWave) 인프라에는 고밀도 셀과 설비 투자가 필요합니다. 5G와 BLE, Wi-Fi를 결합한 하이브리드 스택이 종합적인 커버리지를 실현하는 현실적인 수단으로 부상하고 있으며, 실내 위치 정보 솔루션에 대한 단기적인 수요를 뒷받침하고 있습니다.
GDPR(EU 개인정보보호규정)/CCPA에 기반한 엄격한 옵트인 동의
규제 당국은 현재 위치 정보 데이터에 대한 명시적이고 적극적인 동의를 의무화하고 있으며, 이로 인해 기업용 플랫폼의 규정 준수 비용은 50만 달러에서 200만 달러에 달할 가능성이 있습니다. 미국 21개 주에서 유사한 법률이 제정되어 있으며, 위반 건당 최대 1만 달러의 벌금이 부과될 수 있습니다. 지리적 맥락에 따른 동의 배너는 지역별 규정 준수 대응을 지원하지만, 운영상의 부담도 증가시키기 때문에 개인정보 보호 대책은 공급업체의 로드맵에서 계속해서 핵심 과제로 남아 있습니다.
부문 분석
2025년에는 소프트웨어 플랫폼이 매출의 65.55%를 차지했으며, 다양한 데이터 소스를 통합하고 변화하는 개인정보 보호 규정을 준수할 수 있는 클라우드 네이티브의 기능이 풍부한 스택이 지오마케팅 시장에서 선호되고 있음이 부각되었습니다. 지속적인 업데이트를 통해 AI 세분화, 규정 준수 대시보드, API 커넥터가 온프레미스 환경의 번거로움 없이 사용자에게 제공됩니다. 통합 및 관리형 분석을 주도하는 서비스는 기업들이 광범위한 MarTech 아키텍처에 지오마케팅 인사이트를 통합하기 위한 지침을 모색함에 따라 연평균 성장률(CAGR) 26.69%로 확대되고 있습니다. 서비스와 관련된 지오마케팅 시장 규모가 급속히 확대되고 있는 이유는 맞춤형 온보딩, 독자적인 알고리즘 설계, 규제 감사가 여전히 많은 기업 내 기술 역량의 범위를 벗어나기 때문입니다. Oracle의 2025년 클라우드 매출이 117억 달러에 달할 것으로 예상된다는 점은 소프트웨어 및 서비스를 결합한 계약이 턴키 방식의 위치 인텔리전스를 원하는 기업의 요구를 얼마나 잘 충족시키고 있는지를 보여줍니다.
2025년, 클라우드는 지오마케팅 시장에서 70.42%의 점유율을 차지했으며, 25.46%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 이는 브랜드들이 대규모 캠페인을 위해 탄력적인 컴퓨팅 능력과 신속한 확장성을 선호하기 때문입니다. 마이크로소프트 애저의 매출이 31% 증가한 것은 GPU 가속 분석 및 서버리스 지리공간 파이프라인에 대한 수요가 급증하고 있음을 반영합니다. 데이터 주권 규제가 엄격한 분야에서는 온프레미스 환경이 여전히 주류를 이루고 있지만, 비용 측면에서 어려움을 겪고 있습니다. 하드웨어 및 유지보수 비용을 줄이는 기업들은 총 소유 비용(TCO)을 40-60% 절감하고 있습니다. 네트워크 아웃바운드 요금 및 지연 제약으로 인해 특정 저지연 용도는 하이브리드 환경을 유지하고 있지만, 클라우드 보안의 꾸준한 발전으로 워크로드가 멀티테넌트 환경으로 계속 이동함에 따라 지오마케팅 시장 규모는 확대되고 있습니다.
실외 서비스는 GPS의 보급으로 2025년에도 매출의 59.62%를 유지했으나, 실내 위치 파악의 연평균 성장률(CAGR) 26.74%는 자산 추적 및 몰입형 소매에 대한 수요가 증가하고 있음을 보여줍니다. 차이나모바일의 5G 시스템은 커버리지 영역의 90%에서 3-5미터의 정확도를 달성하여 전 세계 시설에 대한 기능적 벤치마크를 확립했습니다. 기업들이 BLE·Wi-Fi·5G 하이브리드 어레이를 도입함에 따라 실내 서비스 분야의 지오마케팅 시장 규모는 확대되고 있으며, 대기열 관리, 실시간 내비게이션, 근접 오퍼가 가능해졌습니다. 도입의 복잡성과 비용은 여전히 장벽으로 남아 있지만, 비콘 가격 하락과 관리형 서비스 번들 제공으로 인해 중견 소매업체와 병원의 진입 장벽은 낮아지고 있습니다.
지역별 분석
북미는 2025년, 성숙한 애드테크 생태계, 광범위한 5G 보급, 그리고 균형 잡힌 개인정보 보호 법규에 힘입어 전 세계 매출의 37.25%를 계속 차지했습니다. Google Cloud는 기업이 기존 데이터 레이크에 공간 인텔리전스를 통합함에 따라 30%의 매출 성장을 기록했습니다. 연방 및 주 차원의 데이터 개인정보 보호 체계는 명시적인 동의를 의무화하면서도 혁신을 허용하고 있어, 이를 통해 정밀한 타겟팅과 옴니채널 어트리뷰션에 대한 지속적인 투자가 보장되고 있습니다. 아시아태평양은 인구 규모에 따른 모바일 보급, 정부의 5G 도입 촉진 정책, 그리고 ‘모바일 우선’ 소매 문화에 힘입어 26.31%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. GSMA의 추산에 따르면, 2023년에 모바일이 지역 GDP에 8,800억 달러를 기여한 반면, 중국, 일본, 말레이시아에서는 AI 및 실내 위치 정보 관련 시범 사업에 자금이 지원되고 있습니다. 듀얼 네트워크 방식의 5G 프레임워크와 위성 백홀 프로젝트를 통해 고정밀 통신 영역이 농촌 지역까지 확대될 것으로 기대되며, 지오마케팅 시장의 기회가 더욱 넓어지고 있습니다. 유럽에서는 GDPR(EU 개인정보보호규정) 준수에 따른 비용이 있음에도 불구하고 꾸준한 진전이 나타나고 있습니다. 기업들은 엣지 처리, 연합 학습, 차등 프라이버시를 도입하여 현지화와 엄격한 규제의 균형을 맞추고 있습니다. 중동 및 아프리카 및 라틴아메리카는 여전히 발전 단계에 있지만, 미래가 기대되고 있습니다. 걸프 국가들의 스마트 시티 투자와 브라질 및 멕시코의 스마트폰 보급률 상승이 시범 도입을 뒷받침하고 있습니다. 인프라 격차와 법적 불확실성으로 인해 당분간 규모 확대는 제한되고 있지만, 도시화와 디지털 결제가 다음 계획 주기에서 지역 밀착형 성장을 위한 비옥한 토대를 마련하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 동향
AJY 26.09.09According to Mordor Intelligence, geomarketing market size in 2026 is estimated at USD 29.38 billion, growing from 2025 value of USD 23.72 billion with 2031 projections showing USD 85.83 billion, growing at 23.9% CAGR over 2026-2031.
This report is Segmented by Component (Software and Services), Deployment (Cloud and On-Premise), Location (Indoor and Outdoor), End-User Industry (BFSI, IT and Telecommunications, and More), Organization Size (Large Enterprises and Small and Medium Enterprises), Technology (GPS/Cellular, BLE Beacons, and More), Solution Type (Mapping and Geocoding, Location Analytics and Visualization, and More), and Geography.
Global Geomarketing Market Trends and Insights
AI-Driven Hyper-Personalization of Location Ads
Real-time machine-learning models now adapt creatives to an individual's movement patterns, dwell time, and venue preferences, enabling retailers to improve ad-spend efficiency by up to 40% compared with traditional geo-targeting methods. Arrival-time predictions shrink fulfillment gaps, while computer vision links foot traffic to demographic insights, as seen when Aura Vision boosted conversion at Flannels and returned a 4.5 X ROI. These capabilities elevate personalized engagement from optional to indispensable and keep the geomarketing market on an aggressive growth trajectory.
Growing 5G Roll-Outs Expand Indoor Accuracy
Carrier-phase measurements introduced in 3GPP Release 18 deliver sub-meter precision, allowing geomarketing in airports, malls, and factories where GPS once failed. Enterprises have documented 15-20% productivity gains via automated asset tracking, though mmWave infrastructure requires dense cells and capital investment. Hybrid stacks blending 5G with BLE and Wi-Fi are emerging as a pragmatic route to comprehensive coverage, reinforcing near-term demand for indoor location solutions.
Stringent Opt-In Consent Under GDPR/CCPA
Regulators now require explicit, affirmative location-data consent, raising compliance costs that range from USD 500,000 to USD 2 million for enterprise platforms. With 21 US states enacting similar laws, fines can touch USD 10,000 per incident. Geo-contextual consent banners aid regional compliance but add operational overhead, keeping privacy at the center of vendor roadmaps.
Other drivers and restraints analyzed in the detailed report include:
- Retail Digital Twins Link Foot-Traffic and Spend
- Mainstream Adoption of Beacons in Quick-Service Restaurants
- Depreciation of Mobile Ad-IDs Lowers Match Rates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software platforms accounted for 65.55% revenue in 2025, underscoring the geomarketing market preference for cloud-native, feature-rich stacks that can ingest varied data sources and comply with changing privacy rules. Continuous updates funnel AI segmentation, compliance dashboards, and API connectors into user hands without on-premise friction. Services, led by integration and managed analytics, accelerate at 26.69% CAGR as enterprises seek guidance on stitching geomarketing insights into sprawling MarTech architectures.The geomarketing market size tied to services climbs quickly because tailored onboarding, custom algorithm design, and regulatory audits remain outside most in-house skill sets. Oracle's 2025 cloud revenue growth to USD 11.7 billion illustrates how bundled software-plus-services agreements satisfy enterprise appetite for turnkey location intelligence.
Cloud held 70.42% share of the geomarketing market in 2025 and posts the highest 25.46% CAGR as brands favor elastic compute and rapid scaling for high-volume campaigns. Microsoft Azure's 31% revenue jump reflects surging demand for GPU-accelerated analytics and serverless geospatial pipelines.On-premise persists in sectors with strict data sovereignty, yet faces cost headwinds; enterprises cutting hardware and maintenance achieve 40-60% savings in total cost of ownership. Network egress fees and latency constraints keep certain low-latency applications hybrid, but incremental cloud security advances continue drawing workloads into multitenant environments, expanding the geomarketing market footprint.
Outdoor services preserved 59.62% revenue in 2025 thanks to ubiquitous GPS, while indoor positioning's 26.74% CAGR showcases demand for asset tracking and immersive retail. China Mobile's 5G system reached 3-5 meter accuracy across 90% of covered space, setting functional benchmarks for venues worldwide.As enterprises embed hybrid BLE-Wi-Fi-5G arrays, the geomarketing market size for indoor services swells, enabling queue management, real-time navigation, and proximity offers. Deployment complexity and cost remain hurdles, but declining beacon prices and managed-service bundles reduce entry barriers for mid-tier retailers and hospitals.
Complete Report Scope:
- By Component
- Software
- Services
- By Deployment
- Cloud
- On-Premise
- By Location
- Indoor
- Outdoor
- By End-User Industry
- BFSI
- IT and Telecommunications
- Retail and E-commerce
- Media and Entertainment
- Travel and Hospitality
- Other End-user Industries
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Technology
- GPS/Cellular
- BLE Beacons
- Wi-Fi/WLAN
- NFC/RFID
- By Solution Type
- Mapping and Geocoding
- Location Analytics and Visualization
- Geo-Fencing and Proximity Marketing
- Real-Time Tracking
- Campaign Planning and Management
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Singapore
- Malaysia
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America maintained 37.25% of global revenue in 2025, underpinned by mature ad-tech ecosystems, broad 5G penetration, and balanced privacy statutes. Google Cloud logged 30% revenue growth as enterprises layered spatial intelligence on existing data lakes. Federal and state data-privacy frameworks mandate explicit consent yet still permit innovation, ensuring continued investment in precision targeting and omni-channel attribution.Asia-Pacific posts the sharpest 26.31% CAGR, fuelled by population-scale mobile adoption, government 5G incentives, and a mobile-first retail ethos. The GSMA estimates mobile contributed USD 880 billion to regional GDP in 2023, while policies in China, Japan, and Malaysia finance AI and indoor-location pilots. Dual-network 5G frameworks and satellite backhaul projects promise to extend high-accuracy coverage into rural areas, widening the geomarketing market opportunity.Europe advances steadily despite GDPR compliance costs. Enterprises adopt edge processing, federated learning, and differential privacy to reconcile localization with regulatory stringency. Middle East and Africa and Latin America remain emergent yet promising: smart-city investments in the Gulf and rising smartphone penetration in Brazil and Mexico catalyze pilot deployments. Infrastructure gaps and legal uncertainty temper immediate scale, but urbanization and digital payments create fertile ground for localized growth in the next planning cycle.
- Adobe Inc.
- Airship Group Inc.
- Bluedot Industries Pty Ltd.
- CartoDB Inc.
- Cisco Systems Inc.
- Cuebiq Inc.
- ESRI Inc.
- Ericsson AB
- Foursquare Labs Inc.
- Galigeo SAS
- Google LLC
- GroundTruth Inc.
- HERE Technologies
- IBM Corporation
- InMarket Media LLC
- Localytics (Upland Software Inc.)
- Mapbox Inc.
- Microsoft Corporation
- Near Intelligence Holdings Inc.
- Oracle Corporation
- PlaceIQ Inc.
- Plot Projects BV
- Precisely (MapInfo)
- Qualcomm Technologies Inc.
- Radar Labs Inc.
- Reveal Mobile Inc.
- Software AG
- TomTom NV
- UberMedia LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI-driven hyper-personalization of location ads
- 4.2.2 Growing 5G roll-outs expand indoor accuracy
- 4.2.3 Retail digital twins link foot-traffic and spend
- 4.2.4 Mainstream adoption of beacons in quick-service restaurants
- 4.2.5 Rideshare and micromobility data monetization
- 4.2.6 MarTech stacks embedding real-time geofencing
- 4.3 Market Restraints
- 4.3.1 Stringent opt-in consent under GDPR/CCPA
- 4.3.2 Depreciation of mobile ad-IDs lowers match rates
- 4.3.3 Indoor triangulation accuracy gaps in large venues
- 4.3.4 High TCO for multi-source data normalization
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment
- 5.2.1 Cloud
- 5.2.2 On-Premise
- 5.3 By Location
- 5.3.1 Indoor
- 5.3.2 Outdoor
- 5.4 By End-User Industry
- 5.4.1 BFSI
- 5.4.2 IT and Telecommunications
- 5.4.3 Retail and E-commerce
- 5.4.4 Media and Entertainment
- 5.4.5 Travel and Hospitality
- 5.4.6 Other End-user Industries
- 5.5 By Organization Size
- 5.5.1 Large Enterprises
- 5.5.2 Small and Medium Enterprises (SMEs)
- 5.6 By Technology
- 5.6.1 GPS/Cellular
- 5.6.2 BLE Beacons
- 5.6.3 Wi-Fi/WLAN
- 5.6.4 NFC/RFID
- 5.7 By Solution Type
- 5.7.1 Mapping and Geocoding
- 5.7.2 Location Analytics and Visualization
- 5.7.3 Geo-Fencing and Proximity Marketing
- 5.7.4 Real-Time Tracking
- 5.7.5 Campaign Planning and Management
- 5.8 By Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Mexico
- 5.8.2 South America
- 5.8.2.1 Brazil
- 5.8.2.2 Argentina
- 5.8.2.3 Chile
- 5.8.2.4 Rest of South America
- 5.8.3 Europe
- 5.8.3.1 Germany
- 5.8.3.2 United Kingdom
- 5.8.3.3 France
- 5.8.3.4 Italy
- 5.8.3.5 Spain
- 5.8.3.6 Russia
- 5.8.3.7 Rest of Europe
- 5.8.4 Asia-Pacific
- 5.8.4.1 China
- 5.8.4.2 India
- 5.8.4.3 Japan
- 5.8.4.4 South Korea
- 5.8.4.5 Singapore
- 5.8.4.6 Malaysia
- 5.8.4.7 Australia
- 5.8.4.8 Rest of Asia-Pacific
- 5.8.5 Middle East and Africa
- 5.8.5.1 Middle East
- 5.8.5.1.1 United Arab Emirates
- 5.8.5.1.2 Saudi Arabia
- 5.8.5.1.3 Turkey
- 5.8.5.1.4 Rest of Middle East
- 5.8.5.2 Africa
- 5.8.5.2.1 South Africa
- 5.8.5.2.2 Nigeria
- 5.8.5.2.3 Rest of Africa
- 5.8.5.1 Middle East
- 5.8.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Adobe Inc.
- 6.4.2 Airship Group Inc.
- 6.4.3 Bluedot Industries Pty Ltd.
- 6.4.4 CartoDB Inc.
- 6.4.5 Cisco Systems Inc.
- 6.4.6 Cuebiq Inc.
- 6.4.7 ESRI Inc.
- 6.4.8 Ericsson AB
- 6.4.9 Foursquare Labs Inc.
- 6.4.10 Galigeo SAS
- 6.4.11 Google LLC
- 6.4.12 GroundTruth Inc.
- 6.4.13 HERE Technologies
- 6.4.14 IBM Corporation
- 6.4.15 InMarket Media LLC
- 6.4.16 Localytics (Upland Software Inc.)
- 6.4.17 Mapbox Inc.
- 6.4.18 Microsoft Corporation
- 6.4.19 Near Intelligence Holdings Inc.
- 6.4.20 Oracle Corporation
- 6.4.21 PlaceIQ Inc.
- 6.4.22 Plot Projects BV
- 6.4.23 Precisely (MapInfo)
- 6.4.24 Qualcomm Technologies Inc.
- 6.4.25 Radar Labs Inc.
- 6.4.26 Reveal Mobile Inc.
- 6.4.27 Software AG
- 6.4.28 TomTom NV
- 6.4.29 UberMedia LLC
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-Space and Unmet-Need Assessment