

|
시장보고서
상품코드
2124387
조달 분석 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Procurement Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
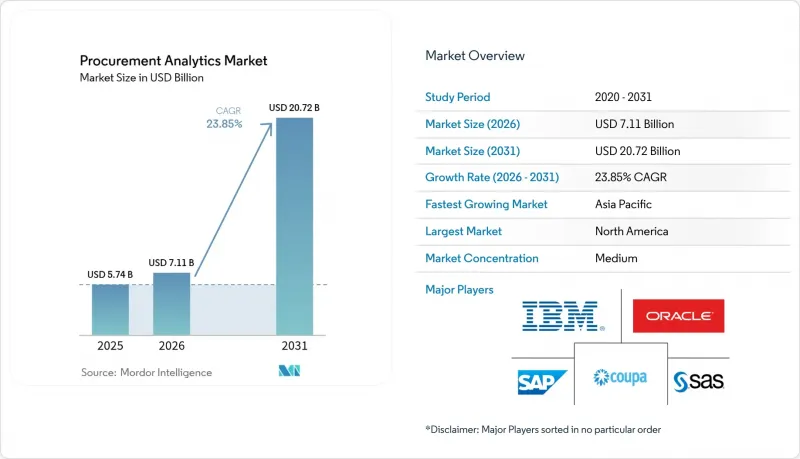
에 의하면, 2026년 조달 분석 시장 규모는 71억 1,000만 달러로 추정되며, 2025년 57억 4,000만 달러에서 2031년에는 207억 2,000만 달러에 달할 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 23.85%를 기록할 것으로 전망됩니다.
본 보고서는 유형별(소프트웨어 및 서비스), 도입 형태별(온프레미스 및 클라우드), 용도별(지출 분석, 리스크 분석, 공급망 분석 등), 최종 사용자 산업별(제조, 운송 및 물류, 소매 및 전자상거래 등), 조직 규모별(대기업 및 중소기업), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 조달 분석 시장 동향 및 인사이트
SaaS를 주축으로 한 조달 제품군의 로드맵
기업들은 파편화된 온프레미스형 도구를 폐지하고, 온디맨드 방식으로 확장 가능하며, 조직 전체의 지출 가시화를 실현하고, 분석 도입 일정을 가속화하는 통합된 클라우드 네이티브 제품군으로 전환하고 있습니다. 도입의 기세는 엔터프라이즈급 인프라에 투자할 자금이 부족했던 중견 기업에서 가장 두드러지지만, 현재는 구독형 가격 책정 및 자동 갱신의 혜택을 누리고 있습니다. 가동 시작 후, 이러한 플랫폼은 분산된 데이터 소스를 통합하고, 조달 프로세스를 최적화하며, 규정 준수를 실시간으로 모니터링하는 머신 러닝 모델의 기반을 마련합니다. 사전 구축된 커넥터나 로우코드 인터페이스를 함께 제공하는 벤더는 가치 실현까지 걸리는 시간을 단축하고, 희소한 통합 인력에 대한 의존도를 최소화할 수 있어 경쟁 우위를 확보하고 있습니다.
소스-투-페이(Source-to-Pay)에 통합된 생성형 AI 코파일럿
발주, 계약, 공급업체 성과 각 워크플로우에 통합된 생성형 AI 모듈은 조달 업무를 사후 대응형에서 인사이트 주도형으로 변화시키고 있습니다. 포춘 500대 기업의 도입 사례에 따르면, AI에 조달 문서 작성, 자유 형식의 지출 데이터 분류, 협상 카드 추출을 맡긴 결과 처리 시간을 두 자릿수만큼 단축했습니다. 하지만 기밀성이 높은 상업 데이터에는 엄격한 거버넌스가 요구되기 때문에 모델에 대한 무제한 접근을 허용하는 기업은 극히 일부에 그치고 있습니다. 이에 대응하여 각 벤더사는 데이터 보호 책임자의 요건을 충족하면서도 혁신을 저해하지 않도록, 정책 기반 접근 제어, 현지화된 언어 모델, 그리고 플랫폼 내 정보 마스킹 기능을 제공함으로써 대응하고 있습니다.
조달 데이터 엔지니어 부족
기업의 58%가 데이터 엔지니어링의 원칙과 카테고리 관리의 미묘한 차이를 모두 이해하는 분석 인력을 채용하는 데 어려움을 겪고 있습니다. 이러한 인력 부족으로 인해 과도한 부담을 안은 팀이 데이터 정제,정규화, 모델 유지보수 업무를 동시에 처리해야 하므로 인건비가 증가하고 도입 주기가 길어지고 있습니다. 일부 기업은 로우코드 데이터 파이프라인을 도입하거나 모델 구축 프로젝트를 벤더에 외주화하여 이러한 격차를 메우려 하고 있지만, 지식 이전은 여전히 고질적인 병목 현상으로 남아 있습니다.
부문 분석
서비스 부문의 수익 기반은 비교적 작지만 연평균 성장률(CAGR) 26.45%로 확대되고 있으며, 숙련된 도입이 지속적인 성과를 가져온다는 점을 기업들이 인식함에 따라 플랫폼의 성장률을 상회하고 있습니다. 자문팀은 고객이 사내에서 재현할 수 없는 데이터 모델 튜닝, 공급업체 온보딩 및 변경 관리에 관한 워크숍을 진행하고 있습니다. 14개 공장에 걸쳐 800개 공급업체를 연계한 존슨 컨트롤즈의 세계 확장은 필요한 통합 작업의 규모를 여실히 드러냈습니다. 따라서 소프트웨어 점유율은 70.62%를 계속 차지하고 있지만, 조달 분석 시장에서 서비스 부문의 규모는 급속히 확대될 것으로 예측됩니다. 교차 교육 이니셔티브, 모범 사례 라이브러리, 성과 연계형 가격 모델은 수수료를 실현된 비용 절감액과 연계함으로써 서비스 이용을 더욱 촉진하고 있습니다. 플랫폼 제공업체들은 셀프 서비스형 설정 마법사를 지속적으로 강화하고 있지만, 데이터 품질에 대한 기대가 높아짐에 따라 전문 서비스에 대한 수요는 여전히 높은 수준을 유지하고 있습니다. 사내에 자문 부서를 보유한 벤더는 라이선스와 서비스 양쪽에서 수익을 창출할 수 있는 반면, 순수 컨설팅 기업은 복잡한 ERP 공존이나 다국어 지원 공급업체 지원 캠페인을 전문으로 합니다. 플랫폼 기능이 표준화됨에 따라, 차별화의 초점은 가치 실현까지의 시간을 단축하는 도입 지원 도구와 도메인별 플레이북으로 이동하고 있습니다.
2025년 수익의 64.35%를 클라우드가 차지했으며, 조달 분석 시장에서 주요 제공 모델로서의 입지가 확고해졌습니다. 하드웨어 교체 회피, 패치 적용 자동화, 사용량에 따른 확장성을 고려하면 경제성은 더욱 향상됩니다. Weinor사가 클라우드 제품군을 도입한 결과, 발주 주기 시간이 최대 41% 단축되었으며, 이는 정규직 직원 1명의 생산성 향상과 맞먹는 수준입니다. 데이터의 현지 보관이 의무화된 규제가 엄격한 산업에서는 온프레미스 환경이 여전히 주류를 이루고 있지만, 이러한 구매자들도 기밀성이 높은 기록을 프라이빗 클라우드에 호스팅하면서 퍼블릭 클라우드의 AI 엔진을 활용하는 하이브리드 모델을 선호하는 경향이 있습니다. 엣지 지원 아키텍처는 차별화 요인으로 부상하고 있으며, 통신 연결이 불안정한 공장 현장에서도 거의 실시간으로 분석이 가능하게 해줍니다. 하이퍼스케일러 및 코로케이션 제공업체와 사전 인증을 획득한 벤더들은 주권 관련 제약 조건을 충족시키면서 고객의 도입을 가속화하고 있습니다. 그 결과, 중소기업이 온프레미스 세대를 완전히 건너뛰게 됨에 따라 조달 분석 시장에서 클라우드 도입의 점유율은 더욱 확대될 전망입니다.
지역별 분석
2025년, 북미는 매출의 36.95%를 차지하며 조달 분석 시장을 주도했습니다. 성숙한 클라우드 인프라, 전문 서비스 제공업체가 구축한 긴밀한 생태계, 그리고 지속되는 관세 불확실성이 기업의 실시간 비용 모델링 엔진 투자를 촉진하고 있습니다. 대학 및 공공 기관의 조사에 따르면, 공급업체의 60% 이상이 관세 관련 우려를 표명하고 있으며, 이로 인해 구매자들은 시나리오 계획용 대시보드 도입을 서두르고 있습니다. 핵심 자재의 리쇼어링에 대한 연방 정부의 장려책이 새로운 변수로 작용하면서, 보조금 추적과 현지 조달 비율 기준을 통합한 분석이 요구되고 있습니다. 아시아태평양은 제조업 주도의 디지털화와 이를 뒷받침하는 전자정부 프로그램 덕분에 26.10%의 연평균 성장률(CAGR)을 달성하고 있습니다. 아시아태평양은 가장 빠른 성장세를 기록하고 있습니다. 중국과 동남아시아의 정부 주도 ‘제조 4.0’ 보조금은 기계 데이터 스트림과 조달 KPI를 연계하는 자동화에 보조금을 지급하고 있습니다. 다국적 OEM 기업들은 싱가포르의 ‘클라우드 퍼스트’ 규제를 활용하기 위해 해당국에 조달 센터를 설립한 후, 아세안 지역 전체 공장으로 공유 서비스를 확대되고 있습니다. 퍼블릭 클라우드 워크로드에 대해 기존에는 신중한 태도를 보여왔던 일본의 대기업들도, 국내 개인정보 보호 관련 법규를 준수하면서 수년에 걸친 구매 기록을 활용한 AI 모델 훈련을 가능하게 하는 소버린 클라우드 존을 도입하고 있습니다. 유럽의 절대적인 지출액은 북미에 근소한 차이로 뒤를 잇고 있습니다. ESG 준수로 인해 공급망의 투명성은 비용 절감과 마찬가지로 전략적 과제로 이사회에 상정되고 있습니다. 프랑스의 ‘디지털 주권 헌장’은 지역 내에서 호스팅되는 제품군에 대한 수요를 촉진하고 있는 반면, 영국의 브렉시트 이후 관세 환경은 조화로운 관세 분류 도구의 필요성을 높이고 있습니다. 니어쇼어링 계약 수주를 목표로 하는 동유럽 제조업체들은 지정학적 위험 및 물류 리드타임 변동을 정량화하는 위험 분석 모듈에 투자하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 동향
AJY 26.09.09According to Mordor Intelligence, procurement analytics market size in 2026 is estimated at USD 7.11 billion, growing from 2025 value of USD 5.74 billion with 2031 projections showing USD 20.72 billion, growing at 23.85% CAGR over 2026-2031.
This report is Segmented by Type (Software and Services), Deployment (On-Premise and Cloud), Application (Spend Analytics, Risk Analytics, Supply Chain Analytics, and More), End-User Industry (Manufacturing, Transportation and Logistic, Retail and E-Commerce, and More), Organization Size (Large Enterprises and Small and Medium Enterprises), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Procurement Analytics Market Trends and Insights
SaaS-first procurement-suite road-maps
Companies are retiring fragmented on-premise tools in favor of unified, cloud-native suites that scale on demand, enable organization-wide spend visibility, and accelerate analytics roll-out schedules. Adoption momentum is most evident among mid-market firms that lacked the capital for enterprise-grade infrastructure, yet now benefit from subscription pricing and automated updates. Once operational, these platforms consolidate disparate data sources, laying the groundwork for machine-learning models that optimize sourcing events and monitor compliance in real time. Vendors that bundle prebuilt connectors and low-code interfaces are gaining an edge because they shorten time-to-value and minimize reliance on scarce integration talent.
Generative-AI copilots embedded in source-to-pay
Generative AI modules embedded inside requisition, contract, and supplier-performance workflows are transforming procurement from reactive to insight-led operations. Fortune-500 adopters report double-digit cuts in processing time after letting AI draft sourcing documents, classify open-text spend, and surface negotiation levers. Nevertheless, only a minority of enterprises allow unrestricted model access because sensitive commercial data requires rigorous governance. Vendors are responding by shipping policy-based access controls, localized language models, and in-platform redaction features that satisfy data-protection officers without stalling innovation.
Shortage of procurement-data engineers
Fifty-eight percent of enterprises struggle to recruit analytics talent who grasp both data-engineering principles and category-management nuances. The scarcity inflates wage bills and prolongs deployment cycles as over-extended teams juggle cleansing, normalization, and model-maintenance tasks. Some firms offset the gap by adopting low-code data-pipelines or outsourcing model-build projects to vendors, yet knowledge transfer remains a persistent bottleneck.
Other drivers and restraints analyzed in the detailed report include:
- Cloud-native TCO economics for mid-market buyers
- ESG-linked supplier scoring mandates
- "Shadow IT" spend outside ERP integration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services held a comparatively small revenue base but are rising at 26.45% CAGR, outpacing platform growth as enterprises acknowledge that skilled implementation drives sustained outcomes. Advisory teams perform data-model tuning, supplier-onboarding, and change-management workshops that customers cannot replicate internally. Johnson Controls' global roll-out, which linked 800 suppliers across 14 plants, underscored the scale of integration work required. The procurement analytics market size for services is therefore projected to expand rapidly, even though software retains a 70.62% share. Cross-training initiatives, best-practice libraries, and outcome-based pricing models are further boosting service uptake by aligning fees with realized savings.Platform providers continue reinforcing self-service configuration wizards, yet growing data-quality expectations keep professional services in demand. Vendors with embedded advisory arms can monetize both license and services streams, while pure-play consultancies specialize in complex ERP co-existence or multi-lingual supplier-enablement campaigns. As platform functionality standardizes, differentiation tilts toward implementation accelerators and domain-specific playbooks that cut time-to-value.
Cloud accounts for 64.35% of 2025 revenue, confirming its status as the dominant delivery model for the procurement analytics market. The economics improve when factoring in avoided hardware refreshes, automated patching, and usage-based scaling. Weinor's adoption of a cloud suite trimmed requisition cycle times by up to 41%, equating to a full-time employee's productivity gain. On-premise persists in regulated verticals that mandate local data residency, but even these buyers favor hybrid models that host sensitive records in private clouds while consuming AI engines from public clouds.Edge-ready architecture is emerging as a differentiator, enabling near-real-time analytics at factory sites with intermittent connectivity. Vendors that pre-certify with hyperscalers and colocation providers accelerate customer deployments while satisfying sovereignty constraints. Consequently, the procurement analytics market share of cloud deployments is set to widen further as smaller firms leapfrog on-premise generations altogether.
Complete Report Scope:
- By Type
- Software
- Services
- By Deployment
- On-Premise
- Cloud
- By Application
- Spend Analytics
- Risk Analytics
- Supply Chain Analytics
- Contract Management
- Demand Forecasting
- Supplier Performance Management
- By End-user Industry
- Manufacturing
- Transportation and Logistics
- Retail and E-commerce
- BFSI
- IT and Telecommunication
- Healthcare and Life Sciences
- Energy and Utilities
- Other End-user Industries
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Singapore
- Malaysia
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America led the procurement analytics market with 36.95% revenue in 2025. Mature cloud infrastructure, a dense ecosystem of specialized service providers, and continued tariff uncertainty encourage enterprises to invest in real-time cost-modeling engines. Universities and utilities confirm that more than 60% of their suppliers express tariff-related concerns, pushing buyers to deploy scenario-planning dashboards. Federal incentives for reshoring critical materials add another dimension, requiring analytics that integrate subsidy tracking and local-content thresholds.Asia-Pacific delivers 26.10% CAGR due to manufacturing-led digitization and supportive e-governance programs. Asia-Pacific posts the fastest growth. Government-led manufacturing 4.0 grants in China and South-East Asia subsidize automation that pairs machine-data streams with procurement KPIs. Multinational OEMs locate sourcing centers in Singapore to tap its cloud-first regulations, then extend shared services across ASEAN plants. Japanese conglomerates, historically cautious about public-cloud workloads, are adopting sovereign-cloud zones that satisfy domestic privacy statutes while enabling AI model training on multi-year purchasing archives.Europe ranks close behind North America in absolute spend. ESG compliance drives analytics to the boardroom, where supply-chain transparency becomes as strategic as price savings. France's digital-sovereignty charter propels demand for regionally hosted suites, while the United Kingdom's post-Brexit customs landscape amplifies the need for harmonized tariff-classification tools. Eastern European manufacturers, aiming to capture near-shoring contracts, invest in risk-analytics modules that quantify geopolitical exposure and logistics lead-time variability.
- SAP SE
- Oracle Corporation
- IBM Corporation
- SAS Institute Inc.
- Coupa Software Inc.
- Zycus Inc.
- Jaggaer LLC
- GEP Worldwide LLC
- Ivalua Inc.
- Basware Oyj
- Sievo Oy
- SpendHQ LLC
- Proactis Holdings PLC
- Rosslyn Data Technologies PLC
- Simfoni Analytics Ltd.
- Spendscape by McKinsey
- Bridgei2i Analytics Solutions
- Genpact Ltd.
- Accenture PLC
- Deloitte Touche Tohmatsu Ltd.
- Infosys Ltd.
- Capgemini SE
- WNS Global Services
- Xoomworks Procurement
- Infor Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 SaaS-first procurement-suite road-maps
- 4.2.2 Generative-AI copilots embedded in Source-to-Pay
- 4.2.3 Cloud-native TCO economics for mid-market buyers
- 4.2.4 ESG-linked supplier scoring mandates
- 4.2.5 Predictive risk analytics for near-shoring strategies
- 4.2.6 Autonomous purchasing bots for tail-spend
- 4.3 Market Restraints
- 4.3.1 Shortage of procurement-data engineers
- 4.3.2 "Shadow IT" spend outside ERP integration
- 4.3.3 Data-sovereignty regulations limiting cross-border hosting
- 4.3.4 Multi-tenant cost models challenged by Gen-AI GPU pricing
- 4.4 Industry Value Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
- 4.7 Industry Attractiveness - Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Type
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment
- 5.2.1 On-Premise
- 5.2.2 Cloud
- 5.3 By Application
- 5.3.1 Spend Analytics
- 5.3.2 Risk Analytics
- 5.3.3 Supply Chain Analytics
- 5.3.4 Contract Management
- 5.3.5 Demand Forecasting
- 5.3.6 Supplier Performance Management
- 5.4 By End-user Industry
- 5.4.1 Manufacturing
- 5.4.2 Transportation and Logistics
- 5.4.3 Retail and E-commerce
- 5.4.4 BFSI
- 5.4.5 IT and Telecommunication
- 5.4.6 Healthcare and Life Sciences
- 5.4.7 Energy and Utilities
- 5.4.8 Other End-user Industries
- 5.5 By Organization Size
- 5.5.1 Large Enterprises
- 5.5.2 Small and Medium Enterprises (SMEs)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Singapore
- 5.6.4.6 Malaysia
- 5.6.4.7 Australia
- 5.6.4.8 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Egypt
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 SAP SE
- 6.4.2 Oracle Corporation
- 6.4.3 IBM Corporation
- 6.4.4 SAS Institute Inc.
- 6.4.5 Coupa Software Inc.
- 6.4.6 Zycus Inc.
- 6.4.7 Jaggaer LLC
- 6.4.8 GEP Worldwide LLC
- 6.4.9 Ivalua Inc.
- 6.4.10 Basware Oyj
- 6.4.11 Sievo Oy
- 6.4.12 SpendHQ LLC
- 6.4.13 Proactis Holdings PLC
- 6.4.14 Rosslyn Data Technologies PLC
- 6.4.15 Simfoni Analytics Ltd.
- 6.4.16 Spendscape by McKinsey
- 6.4.17 Bridgei2i Analytics Solutions
- 6.4.18 Genpact Ltd.
- 6.4.19 Accenture PLC
- 6.4.20 Deloitte Touche Tohmatsu Ltd.
- 6.4.21 Infosys Ltd.
- 6.4.22 Capgemini SE
- 6.4.23 WNS Global Services
- 6.4.24 Xoomworks Procurement
- 6.4.25 Infor Inc.
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-Space and Unmet-Need Assessment


