

|
시장보고서
상품코드
2124390
중쇄지방산(MCT) 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Medium Chain Triglycerides (MCT) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
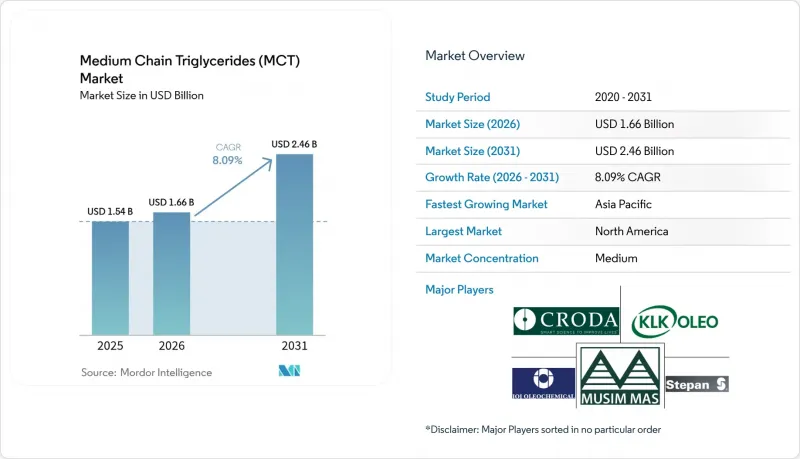
에 의하면, 중쇄지방산(MCT) 시장 규모는 2025년 15억 4,000만 달러에서 2026년에는 16억 6,000만 달러로 확대되어 2026-2031년까지 CAGR 8.09%로 성장을 지속하여, 2031년에는 24억 6,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 형태별(건조, 액체), 공급원별(코코넛 오일, 팜 커널 오일, 기타), 지방산 유형별(카프릴산(C8), 카프르산(C10), 라우르산(C12),카프로산(C6)), 용도별(식음료, 퍼스널케어 및 화장품, 기타), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 중쇄지방산(MCT) 시장 동향 및 인사이트
스포츠 및 퍼포먼스 영양 부문에서 MCT의 활용 확대
카프릴산을 주성분으로 하는 오일은 수 분 이내에 케톤체를 생성하여 혈당의 급격한 상승을 유발하지 않으면서 지구력을 유지할 수 있기 때문에 운동선수들은 장쇄 지방산이나 단순 탄수화물 대신 MCT가 함유된 젤, 샷, 파우더를 점점 더 많이 이용하고 있습니다. 고령자를 대상으로 한 임상 연구에 따르면, MCT의 매일 섭취는 근육의 질을 향상시키는 동시에 포도당 산화를 감소시키는 것으로 나타났으며, 이는 회복과 건강한 노화에 대한 시너지 효과를 기대할 수 있음을 시사합니다. 조사에 따르면, 스포츠 영양 제품 구매자의 상당수가 ‘클린 라벨’ 식생활 철학에 부합하고 인지도가 높은 단일 원산지 유래 지질에 대해 다소 비싼 가격을 지불할 의사가 있는 것으로 밝혀졌습니다. 브랜드 소유자들은 현재 성능 특성을 차별화하기 위해 포장 전면 표시를 통해 특정 사슬 길이 비율을 명시하고 있으며, 이로 인해 가공업체들은 더욱 엄격한 분획 및 순도 사양을 충족해야 할 필요가 생겼습니다. 북미의 수탁 제조업체에 따르면, 부드러운 식감과 저장 안정성을 확보하기 위해 액상 MCT를 채택한 케토 친화적인 즉석 음료의 주문이 두 자릿수 성장세를 보이고 있습니다. 운동선수용 제품 라인에서 환경·사회·지배구조(ESG) 목표를 달성하면서 비용을 관리하기 위해, RSPO 인증을 획득한 지속 가능한 팜 커널 오일 공급망이 활용되고 있습니다.
케토제닉 다이어트와 저탄수화물 다이어트의 확산
케토제닉 식단에 대한 관심이 확산되면서, 소비자들이 혈중 케톤체를 빠르게 높여주는 식재료를 찾게 되었고, 식료품점 매대도 크게 변화하고 있습니다. 카프릴산을 주성분으로 하는 트리카프릴린은 기존 코코넛 오일에 비해 가장 효율적인 케톤 생성 반응을 일으키기 때문에 농축 드롭 및 샷 제품에서 압도적인 점유율을 차지하고 있습니다. 의료 전문가들은 현재 간질 환자를 위해 MCT가 풍부한 식단 계획을 구성하고 있습니다. 이는 중쇄지방산(MCT)이 함유된 제품이라면 발작 억제에 지장을 주지 않으면서도 기존 케토제닉 요법보다 더 많은 탄수화물을 섭취할 수 있기 때문입니다. 소셜 미디어상의 레시피 인플루언서들이 이러한 임상적 지지를 뒷받침하고 있어, 미국, 캐나다, 서유럽의 일반 가정에 대한 보급이 가속화되고 있습니다. 아시아 도시권 소비자들도 이 추세에 동참하고 있으며, 전자상거래 플랫폼에서는 MCT 오일과 글루코만난 섬유를 결합한 저탄수화물 스타터 팩이 판매되고 있어, 지역 정제업체들은 소용량 SKU 및 향이 첨가된 제품 라인업을 확대되고 있습니다. 이러한 식생활의 변화는 견고한 기본 수요를 유지하고 계절적 변동을 완화함으로써 수직 통합형 생산자의 수익원을 안정시키고 있습니다.
코코넛 오일과 팜 커널 오일의 가격 변동
기상 조건에 기인한 공급 충격으로 인해 원료 가격이 빈번하게 상승하고 있습니다. 통계 모델에 따르면, 팜 커널 오일 가격이 1% 상승하면 구매자가 두 원료를 대체하여 사용하는 결과, 코코넛 오일 수요가 1.89% 증가하여 가격 변동이 더욱 확대되는 것으로 나타났습니다. 팜유 공급의 두 축인 인도네시아와 말레이시아의 불안정한 강우량은 생과실의 수확량을 감소시켜 정제유 및 오일케미칼 제품의 가격에도 파급 효과를 미칩니다. 이러한 가격 급등은 식품 제조업체와 3개월간 고정 가격 계약을 맺고 있는 MCT 정제업체의 매출 총이익률을 압박합니다. 농장과의 수직 통합은 자연스러운 헤지 수단이 되지만, 농지를 보유하지 않은 소규모 가공업체는 금융 파생상품이나 장기 공급 계약에 의존할 수밖에 없으며, 이로 인해 운전 자금 수요가 증가할 가능성이 있습니다.
부문별 분석
2025년에는 액상 제품이 매출의 77.10%를 차지하며 압도적인 선두를 달리고 있습니다. 이 격차는 스포츠 음료, RTD 커피, 의료용 영양 브랜드가 빠르게 녹고 따르기 쉬운 형태를 선호함에 따라 더욱 확대될 전망입니다. 액체 하위 카테고리는 연평균 성장률(CAGR) 8.74%로 성장하여 분말 제품을 앞지를 것으로 예측됩니다. 지구력 운동선수를 대상으로 한 원샷 앰플은 이러한 추세를 여실히 보여줍니다. 제형 개발자들은 유화제를 사용하지 않고도 등장성 프로파일을 구현함으로써 라벨 표기를 단순하게 유지하고 있습니다. 반면, 분말 제품은 낮은 수분 함량과 긴 유통 기한이 중요한 바, 베이커리 믹스, 소포장 제품에 적합합니다. 분무 건조 및 캡슐화 기술의 발전으로 지질 함량이 대폭 향상되었으며, 유효 지질 1그램당 비용이 절감되었습니다. 그러나 부피 밀도나 식감에 대한 제약과 같은 과제로 인해, 이러한 분말 제품은 여전히 특수한 용도로만 제한되고 있습니다. 레시틴 캐리어를 이용한 응집 과립과 같은 혁신 기술을 통해 인스턴트 음료 시장으로의 진출이 확대될 가능성이 있습니다.
코코넛 오일은 소비자의 호의적인 평가와 필리핀, 인도네시아, 인도에 걸친 오랜 공급망 덕분에 2025년에도 75.60%의 점유율을 유지했습니다. 이러한 지배적인 지위 뒤에서는 팜 커널 오일이 빠르게 점유율을 확대하고 있으며, 후자의 연평균 성장률(CAGR)은 8.56%로 예측됩니다. 말레이시아의 정제 업체들은 의약품 등급의 C8/C10 분획을 공급하기 위해 미드스트림 공정 분획 기술에 투자하고 있으며, 브랜드 소유자들의 선입견을 서서히 해소해 나가고 있습니다. 마카우바나 합성 에스테르와 같은 대체 원료는 채택이 제한적이긴 하지만, 기후 변화에 강한 수확량 특성으로 인해 주목을 받고 있습니다. 다국적 기업들은 기후 리스크를 헤지하고 지방산 조성을 균일화하기 위해 여러 원료를 혼합하는 전략을 시범적으로 도입하고 있으며, 이는 금세기 말까지 공급 다각화가 표준이 될 것이라는 신호라고 할 수 있습니다.
지역별 분석
2025년, 북미는 매출의 37.90%를 차지했습니다. 이 지역은 명확하게 정의된 FDA의 GRAS(일반적으로 안전하다고 인정되는) 판정의 혜택을 받고 있어, 카테고리를 초월한 신속한 채택이 가능해졌습니다. 마찬가지로, 캐나다의 기능성 식품 규제도 MCT 보충제의 출시를 원활하게 하여 이 지역의 리더십을 공고히 하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 8.76%로 가장 빠르게 성장하고 있는 지역입니다. 중국의 ‘이중 순환’ 정책은 고부가가치 유지화학제품의 국내 생산을 촉진하고 있으며, KLK의 장쑤성 정제소 확장 등 투자를 뒷받침하고 있습니다. 인도 및 인도네시아의 출생률 상승은 유아용 조제분유에 대한 견조한 수요를 뒷받침하고 있는 반면, 일본의 고령화는 임상 영양 제품의 소비를 촉진하고 있습니다. 2024년에는 베트남과 태국에서 정제 코코넛유 수입 관세가 인하되어 아세안(ASEAN) 역내 무역이 촉진될 뿐만 아니라, 현지 혼합 업체들의 입고 비용도 감소했습니다.
유럽에서는 기술 주도형 시장이 유지되고 있습니다. 독일, 프랑스, 영국에서는 약물 전달 플랫폼 및 코스메슈티컬 용도로 고순도 MCT가 조달되고 있습니다. EU의 2024년 신규 식품 승인으로 규제 확실성이 확립되었으나, 곧 시행될 ‘산림 파괴 규제’로 인해 비분리 팜 커널 원료의 규정 준수 장벽이 높아지고 있습니다. 그 결과, 공급업체들은 위성을 활용한 추적성 시스템 도입을 가속화하고 있습니다. 동유럽의 가공업체들은 흑해 회랑을 경유하여 생코코넛 오일 수입을 늘리고, RSPO 프리미엄 요금을 회피하기 위해 국내에서 분획 처리를 실시했습니다. 이 방식은 비용 절감으로 이어지지만, 엄격한 사내 지속가능성 감사가 요구됩니다.
남미에서는 브라질의 스포츠 영양 부문이 확대되고 있으며, 국내 마카우바 농장이 향후 원료 공급의 안정성을 보장하고 있어 꾸준한 성장이 예상됩니다. 중동 및 아프리카는 여전히 발전 단계에 있지만, 의료용 영양 식품 입찰 및 걸프협력회의(GCC) 국가들에서의 할랄 인증을 받은 퍼스널케어 제품 출시를 통해 시장이 점차 열리고 있습니다. 아프리카 대륙 자유무역지대(AfCFTA)의 무역 우대 조치로 인해 향후 10년 동안 현지 분할 거점이 육성될 가능성이 있지만, 인프라 및 원료 확보에 있어서는 아직 초기 단계에 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트의 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the medium chain triglycerides market size is expected to grow from USD 1.54 billion in 2025 to USD 1.66 billion in 2026 and is forecast to reach USD 2.46 billion by 2031 at 8.09% CAGR over 2026-2031.
This report is Segmented by Form (Dry, Liquid), Source (Coconut Oil, Palm Kernel Oil, Others), Fatty Acid Type (Caprylic (C8), Capric (C10), Lauric (C12), Caproic (C6)), Application (Food and Beverage, Personal Care and Cosmetics, Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Medium Chain Triglycerides (MCT) Market Trends and Insights
Growing Usage in Sports & Performance Nutrition
Athletes increasingly replace long-chain fats and simple carbohydrates with MCT-fortified gels, shots, and powders because caprylic-dominant oils generate ketones within minutes, sustaining endurance without glycemic spikes. Clinical work in older adults shows that daily MCT supplementation enhances muscle quality while lowering glucose oxidation, hinting at crossover benefits for recovery and healthy aging. Research highlights that a significant portion of sports-nutrition buyers are willing to pay a premium for recognizable, single-origin lipids that align with clean-label diets. Brand owners now list specific chain-length ratios on front-of-pack claims to differentiate performance profiles, pushing processors toward tighter fractionation and purity specifications. North American contract-manufacturers report double-digit order growth for keto-friendly ready-to-drink beverages that rely on liquid MCTs for smooth mouthfeel and shelf stability. Sustainable palm kernel supply chains that carry RSPO certification are being tapped to manage cost while meeting Environmental, Social, and Governance (ESG) targets in athlete-focused product lines.
Rising Adoption of Ketogenic & Low-Carb Diets
Widespread interest in ketogenic eating is re-shaping grocery aisles as shoppers seek ingredients that elevate circulating ketone bodies quickly. Caprylic-dominant tricaprylin delivers the most efficient ketogenic response compared with traditional coconut oil, driving its dominance in concentrated drops and shots. Medical professionals now prescribe MCT-enriched meal plans to epilepsy patients because medium-chain triglyceride formulations allow higher carbohydrate intake than classical ketogenic protocols without compromising seizure control. Social-media recipe influencers amplify this clinical endorsement, accelerating household penetration in the United States, Canada, and Western Europe. Asian urban consumers are joining the trend as e-commerce platforms bundle MCT oil with glucomannan fibers in low-carb starter packs, prompting regional refiners to add smaller SKUs and flavored variants. The dietary shift sustains robust baseline demand and mitigates seasonality, anchoring revenue streams for vertically integrated producers.
Volatile Coconut & Palm Kernel Oil Prices
Weather-driven supply shocks frequently lift feedstock prices. Statistical modelling shows that a 1% uptick in palm kernel oil prices can push coconut-oil demand higher by 1.89% as buyers substitute between the two inputs, amplifying volatility. Erratic rainfall in Indonesia and Malaysia, the twin pillars of palm supply, depresses fresh-fruit bunch yields and spills into refined-oleochemical pricing. Such spikes compress gross margins for MCT refiners that operate on three-month fixed-price contracts with food manufacturers. Vertical integration into plantations offers a natural hedge, but smaller processors without acreage must rely on financial derivatives or long-term supply agreements, which can raise working-capital requirements.
Other drivers and restraints analyzed in the detailed report include:
- Expansion in Personal Care & Cosmetics Applications
- MCTs in Lipid-Based Drug Delivery Systems
- Availability of Alternative Functional Lipids
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Liquid products accounted for 77.10% sales in 2025, a commanding lead that will widen as sports-drink, RTD coffee, and medical-nutrition brands prefer pourable formats for quick dispersion. The liquid sub-category is projected to grow at 8.74% CAGR, outpacing powders. One-shot ampoules targeting endurance athletes illustrate the trend: formulators achieve isotonic profiles without emulsifiers, preserving label simplicity. In contrast, powders cater to bars, bakery mixes, and sachets, where low moisture and long shelf life matter. Advancements in spray-drying and encapsulation have significantly improved oil-load capacity, reducing the cost per gram of active lipid. However, challenges like bulk density and mouth-feel limitations continue to confine these powders to specialized applications. Innovations such as agglomerated granules with lecithin carriers could expand penetration into instant beverages.
Coconut oil retained a 75.60% share in 2025 thanks to positive consumer perception and long-standing supply chains across the Philippines, Indonesia, and India. That dominance masks rapid palm kernel oil gains: the latter is forecast at 8.56% CAGR. Malaysian refiners are investing in mid-stream fractionation to supply pharmaceutical-grade C8/C10 cuts, eroding brand-owner prejudice. Alternative feedstocks like macauba and synthetic esters are gaining attention due to their climate-resilient yields, despite their limited adoption. Multinationals trial blended-source strategies to hedge climate risks and harmonize fatty-acid spectra, a sign that supply diversification will become standard by the decade's end.
Complete Report Scope:
- By Form
- Dry
- Liquid
- By Source
- Coconut Oil
- Palm Kernel Oil
- Others
- By Fatty Acid Type
- Caprylic (C8)
- Capric (C10)
- Lauric (C12)
- Caproic (C6)
- By Application
- Food and Beverage
- Personal Care and Cosmetics
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Turkey
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- South Africa
- Nigeria
- Egypt
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
North America captured 37.90% revenue in 2025. The region benefits from well-defined FDA GRAS rulings, enabling swift cross-category adoption. Canadian functional-food regulations similarly streamline MCT-supplement launches, cementing regional leadership.
Asia-Pacific is the fastest-growing territory at 8.76% CAGR. China's dual-circulation policy encourages domestic production of high-value oleochemicals, catalyzing investments such as KLK's expanded refinery in Jiangsu. Rising birth rates in India and Indonesia underpin robust infant-formula demand, while Japan's aging population fuels clinical-nutrition consumption. Import duties on refined coconut oil were cut in Vietnam and Thailand during 2024, facilitating intra-ASEAN trade and lowering landed costs for local blenders.
Europe maintains a technology-driven market. Germany, France, and the United Kingdom source high-purity MCTs for drug-delivery platforms and cosmeceuticals. The EU's 2024 novel-food approvals cement regulatory certainty, yet the imminent Deforestation Regulation raises compliance hurdles for non-segregated palm-kernel material; as a result, suppliers are accelerating satellite-based traceability systems. Eastern European processors increasingly import raw coconut oil via the Black Sea corridor, then fractionate internally to sidestep RSPO premium charges, a tactic that trims cost yet demands stringent in-house sustainability audits.
South America shows steady growth as Brazil's sports-nutrition category broadens and domestic macauba plantations promise future feedstock resilience. Middle East & Africa remain nascent but are opening via medical-nutrition tenders and halal-certified personal-care launches in the Gulf Cooperation Council states. Trade incentives in the African Continental Free Trade Area may foster local fractionation hubs over the next decade, though infrastructure and feedstock availability remain early-stage.
- AAK AB
- ABITEC
- Acme-Hardesty
- Barlean's Organic Oils, LLC
- BASF SE
- ConnOils
- CREMER OLEO GmbH & Co. KG
- Croda International Plc
- Henry Lamotte Oils GmbH
- IOI Oleo GmbH
- Jarrow Formulas Inc.
- Kerry Group plc
- KLK Oleo
- Musim Mas Group
- Oleon NV
- Stepan Company
- Sternchemie GmbH & Co. KG
- The Nisshin OilliO Group Ltd.
- Vitaflo International Ltd.
- Wilmar International Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing usage of MCTs in sports and performance nutrition
- 4.2.2 Rising adoption of ketogenic and low-carb diets
- 4.2.3 Expansion in personal care and cosmetics applications
- 4.2.4 MCTs in lipid-based drug delivery systems
- 4.2.5 Premium infant formula demand in Asia
- 4.3 Market Restraints
- 4.3.1 Volatile coconut and palm kernel oil prices
- 4.3.2 Availability of alternative functional lipids
- 4.3.3 Sustainability certification costs for palm sourcing
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Form
- 5.1.1 Dry
- 5.1.2 Liquid
- 5.2 By Source
- 5.2.1 Coconut Oil
- 5.2.2 Palm Kernel Oil
- 5.2.3 Others
- 5.3 By Fatty Acid Type
- 5.3.1 Caprylic (C8)
- 5.3.2 Capric (C10)
- 5.3.3 Lauric (C12)
- 5.3.4 Caproic (C6)
- 5.4 By Application
- 5.4.1 Food and Beverage
- 5.4.2 Personal Care and Cosmetics
- 5.4.3 Other Applications
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Malaysia
- 5.5.1.6 Thailand
- 5.5.1.7 Indonesia
- 5.5.1.8 Vietnam
- 5.5.1.9 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Turkey
- 5.5.3.8 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Colombia
- 5.5.4.4 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Qatar
- 5.5.5.4 South Africa
- 5.5.5.5 Nigeria
- 5.5.5.6 Egypt
- 5.5.5.7 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 AAK AB
- 6.4.2 ABITEC
- 6.4.3 Acme-Hardesty
- 6.4.4 Barlean's Organic Oils, LLC
- 6.4.5 BASF SE
- 6.4.6 ConnOils
- 6.4.7 CREMER OLEO GmbH & Co. KG
- 6.4.8 Croda International Plc
- 6.4.9 Henry Lamotte Oils GmbH
- 6.4.10 IOI Oleo GmbH
- 6.4.11 Jarrow Formulas Inc.
- 6.4.12 Kerry Group plc
- 6.4.13 KLK Oleo
- 6.4.14 Musim Mas Group
- 6.4.15 Oleon NV
- 6.4.16 Stepan Company
- 6.4.17 Sternchemie GmbH & Co. KG
- 6.4.18 The Nisshin OilliO Group Ltd.
- 6.4.19 Vitaflo International Ltd.
- 6.4.20 Wilmar International Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


