

|
시장보고서
상품코드
2124396
디지털 오디오 워크스테이션 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Digital Audio Workstation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 디지털 오디오 워크스테이션(DAW) 시장 규모는 40억 1,000만 달러로 추정되며, 2025년 36억 7,000만 달러에서 2031년에는 61억 9,000만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 9.12%를 기록할 전망입니다.
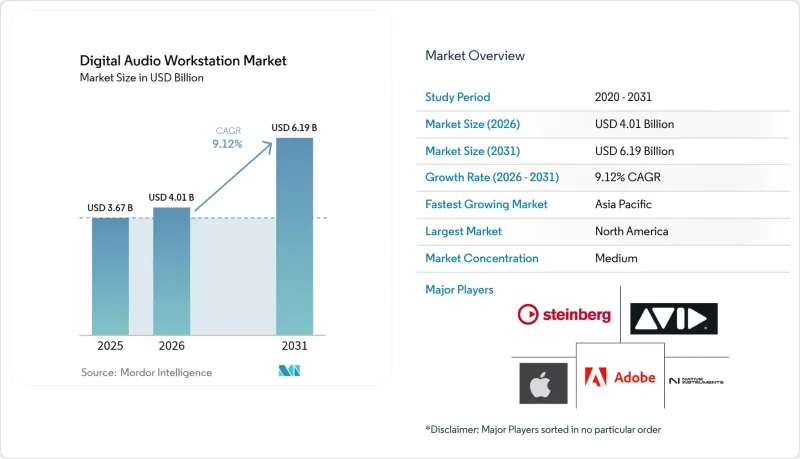
본 보고서는 구성 요소별(소프트웨어 및 서비스), 운영 체제별(macOS, Windows, 기타 운영 체제), 도입 형태별(온프레미스/영구 라이선스 및 클라우드/SaaS), 최종 사용자별(교육 기관 및 음악 학교, 팟캐스트 및 컨텐츠 크리에이터 등), 용도별(음악 제작 및 마스터링 등), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 디지털 오디오 워크스테이션 시장 동향 및 인사이트
인디 음악 프로듀서들 사이에서 클라우드 기반 DAW로의 전환이 확대되고 있습니다.
크리에이터들이 합리적인 가격의 워크스테이션이나 낮은 사양의 하드웨어에서도 작동하며, 기기 간에 세션을 동기화할 수 있는 환경을 추구함에 따라 클라우드 채택이 확대되고 있습니다. Image-Line사의 ‘FL Cloud’는 69종의 악기와 이펙트를 묶은 단계별 구독제를 도입하고 있으며, SaaS형 서비스가 일회성 라이선스를 대체하고, 스토리지 및 업데이트 관리 부담을 경감시키고 있음을 보여줍니다. 자동 버전 관리, 실시간 협업, 기기에 구애받지 않는 액세스 기능은 모바일 우선(Mobile First)을 지향하는 뮤지션들에게 지지를 받고 있습니다. 불법 복제 위험 감소와 지속적인 수익 창출 또한 벤더들이 클라우드 전략을 우선시하는 요인이 되고 있습니다. 사용자 입장에서는 서로 다른 도시에서 지연을 최소화하며 공동 제작할 수 있는 기능 덕분에 클라우드 워크플로가 단순한 신기함에서 필수품으로 변화하고 있으며, 이는 디지털 오디오 워크스테이션 시장의 중기적 성장을 뒷받침하고 있습니다.
OTT 및 게임 스튜디오가 주도하는 몰입형 공간 오디오 제작에 대한 수요 급증
현재 스트리밍 플랫폼에서는 주력 작품의 출시 시 Dolby Atmos 믹싱이 필수로 자리 잡았으며, 한편 주력 게임에서는 사실감을 높이기 위해 오브젝트 기반 오디오가 채택되고 있습니다. Steinberg Nuendo의 네이티브 Dolby Atmos 렌더러와 Netflix의 라우드니스 프리셋은 벤더들의 이러한 움직임을 여실히 보여주고 있습니다. L-Acoustics사의 ‘L-ISA Studio’는 오브젝트 믹싱을 최대 16개 출력까지 확장하여 소규모 시설에서의 활용 범위를 넓히고 있습니다. 몰입형 경험이 당연시됨에 따라, 채널 기반 오소링, 헤드 트래킹을 통한 모니터링, 자동 다운믹싱을 간소화하는 DAW가 경쟁 우위를 확보하며 디지털 오디오 워크스테이션 시장에 장기적인 활력을 불어넣고 있습니다.
프리미엄 및 오픈소스 DAW의 보급이 유료 라이선스를 잠식하고 있습니다.
Reaper의 저가 요금제와 Audacity의 무료 기능 세트로 인해, 상용 벤더들은 기본적인 녹음 및 편집을 넘어서는 부가가치를 입증해야만 하는 상황에 처해 있습니다. 브라우저 기반 도구는 특히 가격에 민감한 지역에서 전환 장벽을 더욱 낮추고 있습니다. 벤더들은 비용을 분산시키는 구독 요금제로 대응하고 있지만, 영구 라이선스에 익숙한 사용자들의 저항에 여전히 직면해 있습니다. 이러한 경쟁으로 인해 디지털 오디오 워크스테이션 시장의 단기적인 수익화 가능성은 낮아지고 있습니다.
부문 분석
2025년 매출의 84.40%를 소프트웨어가 차지했으며, 이는 엔드투엔드 워크플로우 및 생태계 제어에서 소프트웨어가 중심적인 역할을 하고 있음을 여실히 보여줍니다. 서비스 부문은 규모는 작지만, 크리에이터들이 클라우드 스토리지, AI 마스터링, 협업 허브에 요금을 지불함에 따라 연평균 성장률(CAGR) 11.32%로 확대되고 있습니다. 2025년, 소프트웨어는 디지털 오디오 워크스테이션 시장 점유율의 84.40%를 차지했으며, FL Cloud의 단계적 플러그인 번들 등 부가가치 서비스가 벤더 종속성을 심화시키고 있습니다. 크리에이터들이 기기 간에 세션을 이동함에 따라, 통합된 클라우드 라이브러리와 자동 백업 기능을 통해 일회성 구매자가 정기 구독자로 전환되고 있습니다. 그 결과 발생하는 정기 수익은 기능의 신속한 배포를 촉진하여 디지털 오디오 워크스테이션 시장의 성장을 유지하고 있습니다.
서비스 이용 확대는 마스터링이나 스템 분리를 온라인 엔진에 아웃소싱하는 애호가들 사이의 기술 격차도 반영하고 있습니다. 애플의 2단계 가격 정책(Mac 버전은 199.99달러의 영구 라이선스, iPad 버전은 월 4.99달러)은 벤더들이 기기의 이용 사례에 맞추어 가격을 유연하게 조정하고 있음을 보여줍니다. 2031년까지는 수익성이 높은 서비스가 소프트웨어의 상품화를 완화하고, 디지털 오디오 워크스테이션 시장 전체에서 혼합 모델 접근 방식을 강화할 것으로 보입니다.
Windows는 폭넓은 오디오 인터페이스 드라이버 지원과 스튜디오 워크플로우에 확고히 자리 잡은 덕분에 56.40%의 점유율을 유지하고 있습니다. 그러나 모바일 우선 크리에이터와 Arm 기반 노트북이 점차 그 점유율을 잠식하고 있어, 다른 OS 플랫폼의 연평균 성장률(CAGR)을 12.18%로 끌어올리고 있습니다. 2025년 시점에서 디지털 오디오 워크스테이션 시장 규모의 56.40%를 Windows 기기가 차지했으나, Steinberg의 ‘SpectraLayers 12’와 같은 ARM 네이티브 버전이 등장함에 따라 향후 멀티 아키텍처화가 진행될 것으로 예측됩니다. 스마트폰 및 태블릿은 컨텐츠 제작의 기회를 확대하고 있으며, 터치 조작에 최적화된 UI와 클라우드 동기화가 요구되고 있습니다.
현재 크로스 플랫폼 호환성은 구매 결정의 중요한 요소로 자리 잡고 있으며, 사용자들은 데스크톱과 모바일 기기 모두에서 품질 저하 없이 동일한 세션을 열 수 있기를 기대하고 있습니다. 원활한 전환을 실현하는 벤더는 추가 지출을 유도하고, 기기 생태계 전반으로의 보급을 촉진함으로써 디지털 오디오 워크스테이션 시장을 주도하게 될 것입니다.
지역별 분석
북미는 할리우드, 내슈빌, 그리고 게임 및 OTT 스튜디오의 밀집된 네트워크에 힘입어 2025년 매출의 34.70%를 차지했습니다. 안정적인 광대역, 조기 5G 도입, 1인당 크리에이티브 소프트웨어 지출이 높은 점이 프리미엄 제품 채택을 뒷받침하고 있습니다. 그러나 시장 포화와 상승하는 구독 요금에 대한 반발이 추가적인 성장을 억제하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 11.32%를 기록하며 성장 동력으로 자리 잡고 있으며, 중국의 30억 달러 규모 디지털 음악 부문과 모바일 우선 크리에이터 문화가 이를 주도하고 있습니다. 스마트폰 보급률과 숏폼 동영상 생태계가 크로스 디바이스 워크플로우에 대한 수요를 끌어올리며 디지털 오디오 워크스테이션 시장을 확대시키고 있습니다. 정부 주도의 5G 커버리지 확대와 젊은 인구 구성은 클라우드 도입을 가속화하고 있지만, 신흥국에서는 하드웨어 가격 부담이 여전히 장벽으로 작용하고 있습니다.
유럽은 성숙해 가면서도 혁신적인, 균형 잡힌 시장 특성을 보이고 있습니다. 강력한 지적재산권 집행이 프리미엄 가격 책정을 뒷받침하는 한편, 공공 예술 지원금은 클래식 음악 및 방송 시장에 특화된 틈새 DAW의 존속을 지탱하고 있습니다. 라틴아메리카 및 중동 및 아프리카(MEA) 지역은 절대적인 지출액은 낮지만 크리에이터들의 열의가 높은 것이 특징입니다. 입문자층에서는 프리미엄 모델이나 모바일 전용 앱이 주류를 이루고 있으며, 지역에 최적화된 결제 모델을 도입한 벤더들이 향후 업그레이드 수요를 선점할 준비를 갖추고 있습니다. 전반적으로 지리적 다양성으로 인해 디지털 오디오 워크스테이션 시장은 특정 지역의 경기 침체 영향을 덜 받으며, 차별화된 시장 진출 전략이 촉진되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, digital audio workstation market size in 2026 is estimated at USD 4.01 billion, growing from 2025 value of USD 3.67 billion with 2031 projections showing USD 6.19 billion, growing at 9.12% CAGR over 2026-2031.
This report is Segmented by Component (Software, and Services), Operating System (macOS, Windows, Other Operating System), Deployment Mode (On-Premise/Perpetual License, and Cloud/SaaS), End User (Education and Music Schools, Podcast and Content Creators, and More), Application (Music Production and Mastering, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Digital Audio Workstation Market Trends and Insights
Growing Shift Toward Cloud-Based DAWs Among Independent Music Producers
Cloud adoption is climbing as creators seek affordable workstations that run on modest hardware and sync sessions across devices. Image-Line's FL Cloud introduced tiered subscriptions that bundle 69 instruments and effects, illustrating how SaaS offerings replace one-time licenses while cutting storage and update overhead. Automatic versioning, real-time collaboration, and device-agnostic access resonate with mobile-first musicians. Reduced piracy risk and recurring revenue also encourage vendors to prioritize cloud roadmaps. For users, the ability to co-produce from different cities with minimal latency has turned cloud workflows from novelty to necessity, reinforcing a medium-term boost to the digital audio workstation market.
Demand Surge for Immersive Spatial-Audio Production Driven by OTT and Gaming Studios
Streaming platforms now mandate Dolby Atmos mixes for flagship releases, while flagship games rely on object-based audio for realism. Steinberg Nuendo's native Dolby Atmos renderer and Netflix loudness presets demonstrate vendor responses. L-Acoustics' L-ISA Studio extends object mixing to 16 outputs, broadening access for smaller facilities. As immersive experiences become an expectation, DAWs that simplify channel-based authoring, head-tracking monitoring, and automated down-mixing gain competitive advantage, adding long-term momentum to the digital audio workstation market.
Prevalence of Freemium and Open-Source DAWs Eroding Paid Licenses
Reaper's low-cost plan and Audacity's no-cost feature set force commercial publishers to prove added value beyond basic tracking and editing. Browser-based tools further lower switching barriers, particularly in price-sensitive regions. Vendors counter with subscription tiers that amortize costs yet still face resistance from users familiar with perpetual licenses. This competitive tug reduces near-term monetization potential for the digital audio workstation market.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of AI-Assisted Composition Tools by Home-Studio Creators
- Rising Podcast Monetization Creating Need for Turn-Key Editing Suites
- High GPU/CPU Requirements Limiting Mobile and Emerging-Market Adoption
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software accounted for 84.40% of 2025 revenue, underscoring its centrality to end-to-end workflows and ecosystem control. Services, though smaller, are expanding 11.32% CAGR as creators pay for cloud storage, AI mastering, and collaboration hubs. Software captured 84.40% of the digital audio workstation market share in 2025, while value-added services such as FL Cloud's tiered plug-in bundles deepen vendor lock-in. As creators migrate sessions among devices, integrated cloud libraries and automated backups transform one-time purchasers into recurring subscribers. The resulting annuity revenue encourages rapid feature rollouts that keep the digital audio workstation market growing.
Service uptake also reflects skill-set gaps among hobbyists who outsource mastering or stem separation to online engines. Apple's dual-pricing-USD 199.99 perpetual on Mac or USD 4.99 monthly on iPad-illustrates how vendors flex price to match device use cases. By 2031, higher-margin services will cushion software commoditization, reinforcing a mixed-model approach across the digital audio workstation market.
Windows retained a 56.40% foothold thanks to broad audio-interface driver support and entrenched studio workflows. Yet mobile-first creators and Arm-based laptops are chipping away, pushing other OS platforms to a 12.18% CAGR. Windows machines controlled 56.40% of the digital audio workstation market size in 2025, but native Arm builds like Steinberg SpectraLayers 12 hint at a multi-architecture future. Smartphones and tablets expand content creation moments, requiring touch-optimized UIs and cloud sync.
Cross-platform parity now shapes buying decisions; users expect the same session to open on desktop and handheld devices without compromise. Vendors that deliver seamless migrations will capture incremental spend, spreading adoption across device ecosystems and lifting the digital audio workstation market.
Complete Report Scope:
- By Component
- Software
- Services
- By Operating System
- macOS
- Windows
- Other Operating System
- By Deployment Mode
- On-Premise/Perpetual License
- Cloud/SaaS
- By End User
- Professional Audio Engineers and Mixers
- Music and Post-Production Studios
- Electronic and Independent Musicians
- Education and Music Schools
- Podcast and Content Creators
- By Application
- Music Production and Mastering
- Film/TV/OTT Post-Production
- Game-Audio and Immersive Media
- Podcasting and Live-Streaming
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Israel
- Africa
- South Africa
- Nigeria
- Egypt
- Middle East
- North America
Geography Analysis
North America commanded 34.70% of 2025 revenue, supported by Hollywood, Nashville, and a dense network of game and OTT studios. Stable broadband, early 5G rollouts, and high per-capita spending on creative software underpin premium adoption. However, market saturation and pushback against rising subscription fees temper incremental growth.
Asia-Pacific is the growth engine with 11.32% CAGR, led by China's USD 3 billion digital-music sector and mobile-first creator culture. Smartphone penetration and short-form-video ecosystems push cross-device workflow demand, enlarging the digital audio workstation market. Government-backed 5G coverage and youth demographics accelerate cloud adoption, though hardware affordability remains a friction point in emerging economies.
Europe occupies a balanced profile-mature yet innovative. Strong IP enforcement supports premium pricing, while public arts funding sustains niche DAWs tailored to classical and broadcast markets. Latin America and MEA log lower absolute spend but exhibit high creator enthusiasm. Freemium and mobile-only apps dominate entry, positioning vendors with localized payment models to capture future upgrades. Collectively, geographic diversity insulates the digital audio workstation market from single-region downturns and encourages differentiated go-to-market tactics.
- Apple Inc.
- Avid Technology Inc.
- Adobe Inc.
- Steinberg Media Technologies GmbH
- Ableton AG
- Native Instruments GmbH
- Image-Line BV (FL Studio)
- PreSonus Audio Electronics Inc.
- MAGIX Software GmbH
- Propellerhead Software AB (Reason Studios)
- BandLab Technologies (Cakewalk)
- Harrison Consoles Inc.
- Cockos Inc. (REAPER)
- MOTU Inc.
- iZotope Inc.
- Bitwig GmbH
- Tracktion Software Corporation
- Acoustica Inc.
- Soundtrap (Spotify AB)
- Ohm Force
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Shift Toward Cloud-Based DAWs Among Independent Music Producers
- 4.2.2 Demand Surge for Immersive Spatial-Audio Production Driven by OTT and Gaming Studios
- 4.2.3 Adoption of AI-Assisted Composition Tools by Home-Studio Creators
- 4.2.4 Rising Podcast Monetization Creating Need for Turn-Key Editing Suites
- 4.2.5 5G Roll-outs Enabling Low-Latency Remote Collaboration Workflows
- 4.2.6 Proliferation of Subscription-Based Pricing Expanding Paid User Base
- 4.3 Market Restraints
- 4.3.1 Prevalence of Freemium and Open-Source DAWs Eroding Paid Licenses
- 4.3.2 High GPU/CPU Requirements Limiting Mobile and Emerging-Market Adoption
- 4.3.3 Complex IP and Sample-Clearance Regulations Increasing Compliance Costs
- 4.3.4 Hardware Supply-Chain Volatility Causing Audio-Interface Shortages
- 4.4 Technological Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry Intensity
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Operating System
- 5.2.1 macOS
- 5.2.2 Windows
- 5.2.3 Other Operating System
- 5.3 By Deployment Mode
- 5.3.1 On-Premise/Perpetual License
- 5.3.2 Cloud/SaaS
- 5.4 By End User
- 5.4.1 Professional Audio Engineers and Mixers
- 5.4.2 Music and Post-Production Studios
- 5.4.3 Electronic and Independent Musicians
- 5.4.4 Education and Music Schools
- 5.4.5 Podcast and Content Creators
- 5.5 By Application
- 5.5.1 Music Production and Mastering
- 5.5.2 Film/TV/OTT Post-Production
- 5.5.3 Game-Audio and Immersive Media
- 5.5.4 Podcasting and Live-Streaming
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Israel
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Egypt
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Strategic Developments
- 6.2 Vendor Positioning Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.3.1 Apple Inc.
- 6.3.2 Avid Technology Inc.
- 6.3.3 Adobe Inc.
- 6.3.4 Steinberg Media Technologies GmbH
- 6.3.5 Ableton AG
- 6.3.6 Native Instruments GmbH
- 6.3.7 Image-Line BV (FL Studio)
- 6.3.8 PreSonus Audio Electronics Inc.
- 6.3.9 MAGIX Software GmbH
- 6.3.10 Propellerhead Software AB (Reason Studios)
- 6.3.11 BandLab Technologies (Cakewalk)
- 6.3.12 Harrison Consoles Inc.
- 6.3.13 Cockos Inc. (REAPER)
- 6.3.14 MOTU Inc.
- 6.3.15 iZotope Inc.
- 6.3.16 Bitwig GmbH
- 6.3.17 Tracktion Software Corporation
- 6.3.18 Acoustica Inc.
- 6.3.19 Soundtrap (Spotify AB)
- 6.3.20 Ohm Force
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


