|
시장보고서
상품코드
2124405
음성 복제 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Voice Cloning - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
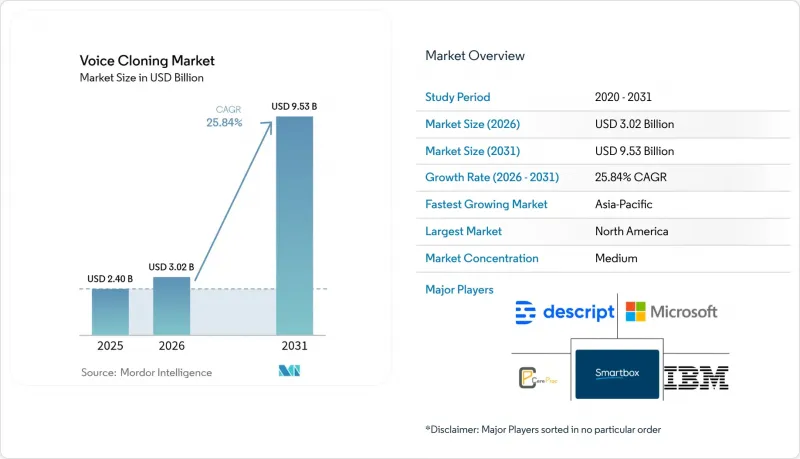
에 의하면, 음성 복제 시장 규모는 2025년에 24억 달러로 평가되었고 2026년에는 30억 2,000만 달러에서 성장하여 2031년까지 95억 3,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 25.84%를 나타낼 전망입니다.
본 보고서는 배포 유형별(On-Premise, 클라우드),구성 요소별(솔루션, 서비스), 음성 복제 기술별(연결형 TTS, 신경망 및 딥러닝 기반 TTS, 기타), 용도별(챗봇 및 음성 어시스턴트, 기타), 최종 사용자 산업별(IT 및 통신, 은행, 금융서비스 및 보험(BFSI), 기타), 지역별로 분류되어 있습니다.
전 세계 음성 복제 시장 동향 및 인사이트
북미 스트리밍 플랫폼의 미디어 현지화에서 AI 생성 개인 맞춤형 음성 채택
주요 스트리밍 스튜디오에서는 현재, 원본 배우의 음성적 특징을 유지한 신경망 음성 복제 기술을 사용하여 현지화된 대사를 생성함으로써 다국어 버전을 동시에 첫 공개하고 있습니다. 제작팀에 따르면, 기존 보이스오버 워크플로우에서 전환한 결과 비용을 40% 절감하고 더빙 주기를 60% 단축할 수 있었습니다고 합니다. 이러한 새로운 경제성 덕분에 소규모 카탈로그 작품에서도 고품질의 현지화를 실현할 수 있게 되어 전 세계적인 도달 범위가 확대되고 있습니다. 2024년에는 신규 가입자의 60% 이상을 해외 시청자가 차지함에 따라, 고품질이면서 확장 가능한 음성 워크플로우에 대한 투자가 경영진 차원의 최우선 과제가 되었습니다. 경쟁 압박으로 인해 도입이 지연되던 기업들도 급속한 현대화를 피할 수 없게 되었으며, 음성 복제 시장은 두 자릿수 성장세를 지속하고 있습니다.
아시아 소매 산업에서 대화형 커머스를 위한 음성 복제 기술의 급속한 도입
중국, 일본, 한국의 소매업체들은 쇼핑 앱 내에 브랜드 고유의 음성 캐릭터를 통합하여 구매 과정을 유도하고 있습니다. 주요 전자상거래 플랫폼에서 진행된 시범 프로젝트에서는 전환율이 23% 향상되었습니다. 음성 복제는 오프라인 소매점에서 제공되는 조언이라는 요소를 재현하면서도, 수백만 건의 동시 세션을 처리할 수 있는 확장성을 실현하고 있습니다. 모바일 쇼핑 이용자는 핸즈프리로 조작할 수 있게 됨으로써 작은 화면에서 조작하는 번거로움이 줄어듭니다. 아시아태평양은 이미 전 세계 모바일 커머스 매출의 60% 이상을 차지하고 있으며, 대화형 음성 기술은 단순한 신기함에서 필수품으로 진화하고 있습니다. 이 지역의 선도적 역할은 세계 브랜드들이 검증된 모델을 모방함에 따라 전 세계로 확산될 것으로 예측됩니다.
딥페이크 음성 사기로 인한 BFSI 산업의 KYC 규정 준수 비용 급증
2024년에는 음성 사기 시도가 138% 급증하며, 은행과 보험사가 사용하는 1세대 음성 생체 인증 시스템의 취약성이 드러났습니다. 금융 기관들은 현재 모든 고위험 통화에 대해 생체 확인, 행동 분석, 강화된 수동 심사를 중복하여 실시했습니다. 이러한 조치로 인해 거래당 검증 비용이 증가하고 고객의 대기 시간이 길어지면서, 음성 복제 기술이 약속했던 효율성 향상이 부분적으로 저해되고 있습니다. 이에 대응해 미국과 유럽의 규제 당국은 KYC 지침을 개정하여 합성 음성에 대한 명확한 규제를 포함시키고 있으며, 이로 인해 규정 준수 업무가 더욱 증가하고 있습니다. 여러 세계 은행은 음성 전용 보안 강화로 인해 지난 1년간 규정 준수 관련 총 지출이 27% 증가했다고 보고하고 있습니다. 감지 도구나 워터마크 기술이 성숙해지기 전까지는 많은 기업이 고객 대응 워크플로우에 새로운 음성 복제 기술 도입을 연기하거나 제한할 것으로 보입니다.
부문 분석
2025년 음성 복제 시장 규모 중 클라우드 호스팅형 플랫폼은 10억 3,000만 달러를 차지하여 매출 점유율의 42.80%에 해당하며, 2031년까지 연평균 성장률(CAGR) 29.82%로 확대되고 있습니다. 유연한 리소스 확장, 전 세계 에지 노드, 종량제 요금제 덕분에 클라우드는 새로운 시범 도입 시 기본 선택지가 되고 있습니다. 벤더의 로드맵에서는 현재 왕복 100밀리초 이하의 실시간 스트리밍 품질이 우선시되고 있어, 기존의 지연에 대한 우려는 점차 해소되고 있습니다. 서비스 수준 계약(SLA)에서는 99.9%의 가동률이 보장되어, 컨택 센터나 라이브 방송과 같은 중요한 이용 사례에서 안심감을 제공합니다. 또한 클라우드 생태계 덕분에 번역이나 감정 분석과 같은 관련 AI 서비스에 대한 접근도 간소화되어, 제품 관리자의 통합 부담이 줄어들고 있습니다. 금융 서비스 및 의료 분야의 데이터 상주 요건으로 인해 On-Premise 도입은 여전히 매출의 57.20%를 차지하고 있습니다. 이러한 구매자들은 생체 인식 데이터에 대한 엄격한 관리가 필요하며, 피크 시간대 수요에 대응하기 위해 사내 GPU 클러스터와 하이브리드 오케스트레이션을 결합하여 클라우드의 버스트 용량을 활용하는 경우가 많습니다. 주요 공급업체들은 Docker 호환 음성 엔진과 Kubernetes Helm 차트를 제공하여 DevOps 팀이 음성 복제 기능을 기존 CI/CD 워크플로에 통합할 수 있도록 하고 있습니다. 엣지 컴퓨팅은 지연 시간에 민감한 작업을 위해 고객 소유의 게이트웨이에 추론 모듈을 배치하는 한편, 훈련을 클라우드로 집중시킴으로써 경계를 더욱 모호하게 만들고 있습니다. 개인정보 보호형 연합 학습이 성숙해짐에 따라, 완전한 On-Premise 환경에서 하이브리드 환경으로의 전환은 계속될 것이며, 음성 복제 시장에서 순수한 On-Premise 환경의 점유율은 시간이 지남에 따라 축소될 것으로 보입니다.
2025년 매출 중 솔루션이 71.10%를 차지했지만, 서비스 부문은 연평균 성장률(CAGR) 28.93%로 성장하여 소프트웨어 라이선스의 22.61%를 상회하고 있습니다. 기업들은 현재 도입 거버넌스, 모델 미세 조정, 규정 준수 대책 설계에 중점을 두고 있으며, 이 모든 분야에 전문적인 컨설팅이 요구되고 있습니다. 도입 파트너 기업들은 언어학자, 윤리학자, DevSecOps 엔지니어로 구성된 다분야 팀을 구성하여, 음성 복제 전략을 브랜드 및 법적 요건에 부합하도록 조정하고 있습니다. 새로운 서비스 제공 사례로는 향후 분쟁에 대비해 화자의 권리를 기록하는 ‘보이스 DNA 감사’ 등이 있습니다. 한편, 플랫폼 벤더들은 신경망을 통한 재현성의 한계를 끊임없이 넓혀가고 있습니다. 트랜스포머 기반 엔진은 30초 미만의 참조 음성만으로도 실용적인 클론을 생성할 수 있어, 탤런트 에이전시나 의료 분야에서의 도입 프로세스가 효율화됩니다. 저 비트레이트 코덱 최적화를 통해 고조파의 세부 정보를 손상시키지 않으면서 대역폭을 60% 줄여, 자동차 인포테인먼트 시스템에서의 무선 전송을 가능하게 합니다. 거버넌스 모듈은 모든 합성 요청을 암호 해시로 로그에 기록하여, 새롭게 제정되고 있는 AI 감사법을 충족하는 불변의 증빙 기록을 생성합니다. 이러한 진전으로 인해 서비스 매출이 확대되는 가운데에도 솔루션 부문의 수익 하한선이 강화되어, 음성 복제 시장 내의 균형이 유지되고 있습니다.
지역별 분석
북미는 실리콘밸리의 연구 클러스터와 할리우드의 미디어 수요를 견인력으로 삼아 2025년 수익의 38.70%를 차지했습니다. 스트리밍 플랫폼은 신경망 더빙 워크플로우를 표준화하여 전 세계 제작사에 파급되는 사실상의 품질 기준을 확립하고 있습니다. 규제 당국의 모니터링이 두드러집니다. 연방거래위원회(FTC)가 주최하는 ‘보이스 클로닝 챌린지’에서는 기술자들에게 컨텐츠 인증 솔루션 제안을 요구하고 있으며, 이러한 움직임으로 인해 벤더들은 워터마크 기능을 기본적으로 통합하도록 압력을 받고 있습니다. 규제가 강화되고 있음에도 불구하고 벤처 자금 조달은 여전히 호조를 보이며, 기업의 자금 조달 파이프라인을 뒷받침하는 활기찬 스타트업 생태계를 유지하고 있습니다. 아시아태평양은 성장의 원동력이며, 2031년까지 연평균 성장률(CAGR) 27.42%를 기록할 전망입니다. 중국은 방언에 대한 유연한 대응이 요구되는 방대한 전자상거래 생태계의 견인 아래, 다국어 복제 기술 연구를 주도하고 있습니다. 일본의 헬스테크 기업들은 고령자에 맞춘 합성 음성을 도입하여 고령화 사회에서 발생하는 의사소통의 격차 해소에 힘쓰고 있습니다. 한국의 게임 퍼블리셔들은 실시간 캐릭터 음성 모핑을 실험하고 있으며, 새로운 참여 유도 방식에 관심이 쏠리고 있습니다. 인도는 언어적으로 복잡하면서도 유망한 시장으로, 지역 언어 지원을 통해 수억 명의 신규 사용자를 확보할 가능성이 있습니다. 이러한 동향들이 맞물려 아시아태평양은 음성 복제 시장에서 가장 빠르게 발전하고 있는 지역이 되었습니다. 유럽의 초점은 거버넌스와 접근성에 맞추어져 있습니다. EU의 AI 법안에는 합성 음성 사용 시 공개를 의무화하는 투명성 조항이 도입되어, 공급업체는 감사 대시보드를 제공해야 합니다. 유럽 접근성 법은 공공 디지털 서비스에 대한 수요를 더욱 공고히 하고 있습니다. 독일 산업계에서는 공장 현장에 음성 대응 로봇 도입을 검토하고 있는 반면, 영국에서는 주요 은행에서 복제 음성을 활용한 고객 서비스 담당자 검사 운영이 이루어지고 있습니다. 규정 준수 관련 장애물로 인해 판매 주기는 길어지겠지만, 궁극적으로는 신뢰도를 높여 유럽 대륙 전역 시장에서 지속적인 보급을 보장할 것입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the voice cloning market size was valued at USD 2.40 billion in 2025 and estimated to grow from USD 3.02 billion in 2026 to reach USD 9.53 billion by 2031, at a CAGR of 25.84% during the forecast period (2026-2031).
This report is Segmented by Deployment Type (On-Premise, Cloud), Component (Solution, Service), Voice-Cloning Method (Concatenative TTS, Neural and Deep-Learning-Based TTS, and More), Application (Chatbots and Voice Assistants and More), End-User Vertical (IT and Telecommunications, BFSI, and More), and Geography.
Global Voice Cloning Market Trends and Insights
Adoption of AI-generated Personal Voices for Media Localization by North-American Streaming Platforms
Major streaming studios now release multi-language premieres simultaneously by rendering localized dialogue with neural voice clones that preserve the original actor's vocal fingerprint. Production teams report 40% cost savings and 60% faster dubbing cycles after switching from traditional voice-over workflows. The new economics allow smaller catalog titles to secure high-quality localization, widening global reach. As international viewers contributed more than 60% of new subscriptions in 2024, investing in premium yet scalable voice workflows became a board-level priority. Competitive pressure is forcing late adopters to modernize rapidly, sustaining double-digit momentum in the voice cloning market.
Rapid Integration of Voice Cloning in Conversational Commerce across Asian Retail
Chinese, Japanese, and Korean retailers embed branded voice personalities inside shopping apps to guide purchasing journeys. Pilot projects boosted conversion rates by 23% on flagship e-commerce platforms. Voice cloning restores the advisory element of brick-and-mortar retail, yet scales to millions of concurrent sessions. Mobile shoppers benefit from hands-free navigation, reducing friction on small screens. With Asia Pacific already accounting for more than 60% of global mobile commerce revenue, conversational voice is evolving from novelty to necessity. This regional lead will ripple outward as global brands mimic proven templates.
Deepfake Voice Fraud Escalating KYC Compliance Costs for BFS
Voice fraud attempts surged 138% in 2024, exposing gaps in first-generation voice biometric systems used by banks and insurers. Financial institutions now layer liveness checks, behavioral analytics, and stepped-up manual reviews onto every high-risk call. These countermeasures raise per-transaction verification costs and prolong customer wait times, eroding some of the efficiency gains that voice cloning promised. Regulators in the United States and Europe have responded by updating KYC guidelines to include explicit controls for synthetic speech, adding more compliance tasks. Several global banks report that voice-specific security upgrades have lifted overall compliance spending by 27% in the past year. Until detection and watermarking tools mature, many firms will defer or limit new voice cloning deployments in customer-facing workflows.
Other drivers and restraints analyzed in the detailed report include:
- Accessibility Mandates Driving Synthetic Speech in European Public Digital Services
- SaaS Voice-API Monetization Accelerating Cloud Deployments Worldwide
- High GPU Compute Costs Hindering SME Adoption of Real-time Neural Synthesis
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud-hosted platforms represented USD 1.03 billion of the voice cloning market size in 2025, equal to 42.80% revenue share, and are advancing at a 29.82% CAGR to 2031 Flexible resource scaling, global edge nodes, and pay-as-you-go billing make cloud the default choice for new pilots. Vendor roadmaps now prioritize real-time streaming quality at sub-100 ms round-trip, dissolving historical latency concerns. Service level agreements offer 99.9% uptime, reassuring critical use cases in contact centers and live broadcasts. Cloud ecosystems also simplify access to adjacent AI services like translation and sentiment analysis, lowering integration friction for product managers. On-premise installations still command 57.20% revenue share owing to data residency mandates in financial services and healthcare. These buyers require airtight control of biometric data and often pair internal GPU clusters with hybrid orchestration to tap burst cloud capacity for peak demand. Leading suppliers are shipping Docker-ready voice engines and Kubernetes Helm charts, letting DevOps teams integrate voice cloning into existing CI/CD workflows. Edge computing further blurs boundaries by placing inference modules on customer-owned gateways for latency-sensitive tasks while centralizing training in the cloud. As privacy preserving federated learning matures, migration paths from strictly on-premise to hybrid footprints will continue, shrinking pure on-prem holdings over time within the voice cloning market.
Solutions captured 71.10% of 2025 revenue, yet services are climbing at 28.93% CAGR versus 22.61% for software licences Enterprises now emphasize deployment governance, model fine-tuning, and compliance policy design, all of which demand specialized consulting. Implementation partners staff multidisciplinary teams of linguists, ethicists, and DevSecOps engineers to align voice cloning strategies with brand and legal requirements. New service offerings include voice DNA audits that catalog speaker rights for future disputes. Meanwhile, platform vendors keep pushing the envelope on neural fidelity. Transformer-based engines can build a viable clone from under 30 s of reference audio, streamlining onboarding for talent agencies and medical use cases. Low-bit-rate codec optimization cuts bandwidth by 60% without clipping harmonic detail, enabling over-the-air delivery in automotive infotainment. Governance modules now log every synthesis request with cryptographic hashes, creating immutable trails that satisfy emerging AI audit laws. These advances reinforce the solutions segment's revenue floor even as service billings expand, maintaining balance inside the voice cloning market.
Complete Report Scope:
- By Deployment Type
- On-Premise
- Cloud
- By Component
- Solution
- Service
- By Voice-Cloning Method
- Concatenative TTS
- Parametric/Statistical TTS
- NeuralandDeep-Learning-based TTS
- By Application
- ChatbotsandVoice Assistants
- AccessibilityandAssistive Technologies
- DigitalandInteractive Games
- DubbingandLocalization
- Customer ServiceandIVR
- Voice ProstheticsandPersonalized Speech
- By End-user Vertical
- ITandTelecommunications
- BFSI
- HealthcareandLife Sciences
- MediaandEntertainment
- Education
- TravelandTourism
- RetailandE-commerce
- GovernmentandDefense
- By Geography
- North America
- United States
- Canada
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America commanded 38.70% of 2025 revenue, anchored by Silicon Valley research clusters and Hollywood media demand. Streaming platforms standardize neural dubbing workflows, setting de facto quality bars that ripple through global production houses. Regulatory scrutiny is palpable: the Federal Trade Commission's Voice Cloning Challenge invites technologists to propose content authentication solutions, a move that pressures vendors to embed watermarking natively.Despite tighter oversight, venture funding remains buoyant, sustaining a vibrant startup pipeline that feeds enterprise procurement pipelines. Asia Pacific is the growth engine, posting a 27.42% CAGR through 2031. China spearheads multilingual cloning research, driven by its vast e-commerce ecosystems, which require dialect agility. Japanese health-tech firms are deploying synthetic voices tailored for senior citizens, addressing the communication gaps of an aging population. South Korean game publishers experiment with real-time character voice morphing, spotlighting new engagement mechanics. India presents a fertile, linguistically complex market where regional language support can unlock hundreds of millions of new users. Together, these dynamics position Asia Pacific as the fastest-advancing region in the voice cloning market. Europe's narrative centers on governance and accessibility. The EU AI Act introduces transparency clauses that obligate disclosures when synthetic voices are used, compelling vendors to ship audit dashboards. The European Accessibility Act further entrenches demand within public digital services. Germany's industrial sector explores voice-enabled robotics on factory floors, while the United Kingdom pilots cloned-voice customer reps across leading banks. Although compliance hurdles extend sales cycles, they ultimately elevate trust, ensuring sustained uptake across continental markets.
- Microsoft Corporation
- Amazon Web Services, Inc.
- Google LLC
- IBM Corporation
- Apple Inc.
- Baidu, Inc.
- Descript, Inc.
- Acapela Group SA
- CereProc Ltd.
- Resemble AI, Inc.
- VocaliD, Inc.
- ElevenLabs, Inc.
- LumenVox LLC
- iSpeech, Inc.
- Smartbox Assistive Technology Ltd.
- WellSaid Labs, Inc.
- ReadSpeaker Holding BV
- NeoSpeech, Inc.
- Sonantic Ltd.
- rSpeak Technologies Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study AssumptionsandMarket Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Adoption of AI-generated Personal Voices for Media Localization by North-American Streaming Platforms
- 4.2.2 Rapid Integration of Voice Cloning in Conversational Commerce across Asian Retail
- 4.2.3 Accessibility Mandates Driving Synthetic Speech in European Public Digital Services
- 4.2.4 SaaS Voice-API Monetization Accelerating Cloud Deployments Worldwide
- 4.2.5 Growing Adoption of Multilingual Digital Advertising
- 4.2.6 The Emergence of Digital Avatars
- 4.3 Market Restraints
- 4.3.1 Deepfake Voice Fraud Escalating KYC Compliance Costs for BFSI
- 4.3.2 High GPU Compute Costs Hindering SME Adoption of Real-time Neural Synthesis
- 4.3.3 Fragmented Regulation Across Regions is Restraining the Growth
- 4.3.4 Ethical Consent Hurdles Raising Concerns Over Unauthorized Use of Personal Voice Data and Complicating Adoption
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory or Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers/Consumers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Impact of COVID-19 on the Voice Cloning Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Type
- 5.1.1 On-Premise
- 5.1.2 Cloud
- 5.2 By Component
- 5.2.1 Solution
- 5.2.2 Service
- 5.3 By Voice-Cloning Method
- 5.3.1 Concatenative TTS
- 5.3.2 Parametric/Statistical TTS
- 5.3.3 NeuralandDeep-Learning-based TTS
- 5.4 By Application
- 5.4.1 ChatbotsandVoice Assistants
- 5.4.2 AccessibilityandAssistive Technologies
- 5.4.3 DigitalandInteractive Games
- 5.4.4 DubbingandLocalization
- 5.4.5 Customer ServiceandIVR
- 5.4.6 Voice ProstheticsandPersonalized Speech
- 5.5 By End-user Vertical
- 5.5.1 ITandTelecommunications
- 5.5.2 BFSI
- 5.5.3 HealthcareandLife Sciences
- 5.5.4 MediaandEntertainment
- 5.5.5 Education
- 5.5.6 TravelandTourism
- 5.5.7 RetailandE-commerce
- 5.5.8 GovernmentandDefense
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Spain
- 5.6.3.5 Italy
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 South Africa
- 5.6.5.4 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, ProductsandServices, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 Amazon Web Services, Inc.
- 6.4.3 Google LLC
- 6.4.4 IBM Corporation
- 6.4.5 Apple Inc.
- 6.4.6 Baidu, Inc.
- 6.4.7 Descript, Inc.
- 6.4.8 Acapela Group SA
- 6.4.9 CereProc Ltd.
- 6.4.10 Resemble AI, Inc.
- 6.4.11 VocaliD, Inc.
- 6.4.12 ElevenLabs, Inc.
- 6.4.13 LumenVox LLC
- 6.4.14 iSpeech, Inc.
- 6.4.15 Smartbox Assistive Technology Ltd.
- 6.4.16 WellSaid Labs, Inc.
- 6.4.17 ReadSpeaker Holding BV
- 6.4.18 NeoSpeech, Inc.
- 6.4.19 Sonantic Ltd.
- 6.4.20 rSpeak Technologies Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-spaceandUnmet-need Assessment